 MetaTrader 5
 Sistemi Esperti
 Indicatori
 Script
 Librerie
 Archiviazione
Guarda come scaricare robot di trading gratuitamente
Ci trovi su Facebook!
Unisciti alla nostra fan page
Unisciti alla nostra fan page
Ti è piaciuto lo script? Provalo nel Terminale MetaTrader 5

FTNP - indicatore per MetaTrader 5

- Visualizzazioni:
- 6025
- Valutazioni:
- Pubblicato:
- Aggiornato:
-
 Ti stai perdendo delle opportunità di trading:
- App di trading gratuite
- Oltre 8.000 segnali per il copy trading
- Notizie economiche per esplorare i mercati finanziari
Registrazione AccediAccetti la politica del sito e le condizioni d’uso
Se non hai un account, registrati -
 Hai bisogno di un robot o indicatore basato su questo codice? Ordinalo su Freelance
Vai a Freelance
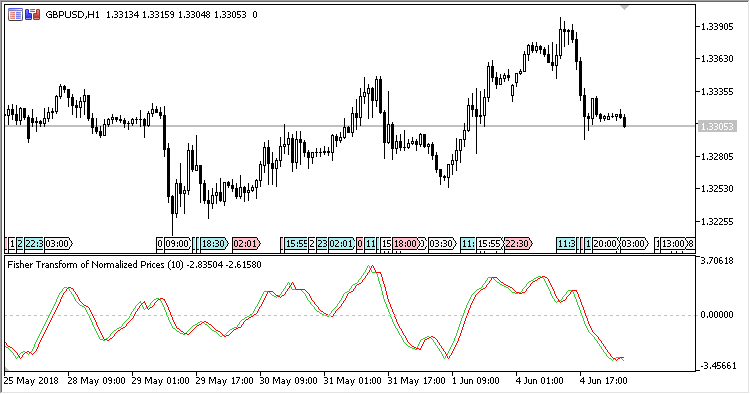
An oscillator using Fischer Transform of normalized prices.
Normalizing price flows by Fischer Transform allows you to detect the peak oscillations of the indicator line, which indicate the trend resersal points.
The indicator has two input parameters:
- Period - calculation period
- Applied price - calculation price
Calculation:
Fisher = 0.5*(Log((1+V) / (1-V)) + PrevFisher)
Trigger = PrevFisher
where:
V = (2/3) * ((Price - MinPrice) / (MaxPrice - MinPrice) - 0.5 + PrevV)
MinPrice, MaxPrice - the minimum and the maximum prices within the Period range Period
Log - natural logarithm
Tradotto dal russo da MetaQuotes Ltd.
Codice originale https://www.mql5.com/ru/code/20997
AbsolutelyNoLagLwma_x2_cloud_HTF
Two indicators AbsolutelyNoLagLwma from different timeframes, the area between lines being filled with a cloud, the color of which corresponds with the trend direction on the market
ColorXDerivative
Indicator Derivative additionally smoothed and made as a color histogram