MT5 Trade Copier: Managing Swap Rate Differences Between Brokers in Copy Trading

Product link:
https://www.mql5.com/en/ market/product/191385
Most discussions about MT5 copy trading focus on execution speed, spread, slippage, and synchronization. However, another important factor can gradually affect the performance of copied trades: swap.
Swap, also known as overnight financing, is a charge or credit that may be applied when a position remains open through the broker's daily rollover. Because the Sender and Receiver accounts may use different brokers, their swap conditions can be significantly different even when the trades themselves are copied correctly.
This means that two accounts can receive exactly the same trade signals and still produce different results over time.
1. What Is Swap in MT5 Trading?
Swap is an overnight financing adjustment applied by the broker when a position remains open beyond the relevant rollover time.
Depending on the instrument, broker, direction, and account conditions, swap can be:
- A charge deducted from the account
- A credit added to the account
- Calculated using points
- Calculated using a percentage
- Calculated using a monetary financing rate
The exact calculation is determined by the broker and the trading conditions of the specific symbol.
For currency pairs, swap is often related to interest-rate differentials between the two currencies, together with the broker's pricing and financing conditions. For indices, commodities, metals, and other instruments, the financing calculation can be different.
2. Why Swap Matters in Copy Trading
In a normal trade copier, the Receiver executes trades on its own trading account. The Receiver therefore incurs the costs applicable to its own broker.
The Receiver does not automatically inherit the Sender broker's swap conditions.
Sender Broker | | Same Trade v Trade Copier | v Receiver Broker | +---- Receiver's Spread +---- Receiver's Commission +---- Receiver's Swap +---- Receiver's Execution
This distinction is fundamental.
A Sender may pay a relatively small overnight financing charge while the Receiver may pay substantially more for the same symbol and direction.
3. A Simple Example
Imagine that a Sender holds a position for two weeks.
| Cost | Sender | Receiver |
|---|---|---|
| Trade | Copied | Copied |
| Entry | Similar | Similar |
| Exit | Similar | Similar |
| Swap | Low | High |
The trading activity may appear almost identical, but the Receiver can end the period with a materially different net result because its accumulated financing cost is different.
This is not necessarily a synchronization failure. It is a difference in the trading conditions of the two accounts.
4. Swap Is Especially Important for Longer-Term Strategies
Swap becomes more significant as the holding period increases.
It can be particularly relevant for:
- Carry-trade strategies
- Swing trading
- Position trading
- Strategies holding trades for several days
- Strategies holding positions for weeks or months
- Instruments with relatively high financing costs
For a strategy that normally opens and closes positions within the same trading day and does not pass through the broker's rollover, swap may have little or no practical impact.
For overnight strategies, however, it should be included in the overall cost analysis.
5. The Receiver's Swap Is What Matters to the Receiver
One of the most important principles in copy trading is:
Sender swap ≠ Receiver swap
The Sender's financing conditions do not determine the Receiver's financing conditions.
The Receiver account uses its own broker's:
- Swap Long
- Swap Short
- Swap calculation method
- Rollover schedule
- Triple-swap rules
Therefore, when evaluating a Receiver account, traders should examine the actual swap conditions available on that account.
6. Swap Long and Swap Short
Swap conditions can differ depending on the direction of the position.
| Position | Relevant Swap |
|---|---|
| Buy | Swap Long |
| Sell | Swap Short |
This becomes particularly important when Reverse Mode is enabled.
A Sender may hold a Buy while a Receiver using Reverse Mode holds a Sell. The Receiver is then exposed to the Receiver broker's short-side financing condition, not the Sender's long-side swap.
7. Reverse Mode Can Change the Swap Profile
Reverse Mode changes the direction of the copied position.
Sender: BUY Receiver: SELL
Because the direction changes, the applicable swap condition can also change.
For example, if the Receiver broker has:
Swap Long  = -X
Swap Short = +Y
the Receiver's financing result can differ substantially from the Sender's, even before considering any other trading costs.
This is another reason why Reverse Mode should be evaluated using the Receiver's actual broker conditions rather than assuming that the reversed trade has the same cost structure.
8. Triple Swap and Rollover
Many brokers apply a multiple-day financing adjustment on one specific rollover day to account for the financing associated with the weekend or other non-trading days.
This is commonly known as triple swap.
The exact day and calculation can vary between brokers and instruments, so traders should verify the current specification for the relevant symbol.
For example, a position that normally incurs one day's financing may receive a larger adjustment during the broker's designated triple-swap rollover.
Normal rollover: 1 × daily swap Triple-swap rollover: multiple days' financing
For a large or long-held position, this can make a noticeable difference to account performance.
9. Why Triple Swap Can Be Important in Copy Trading
Suppose the Sender holds a position through a triple-swap rollover and the Receiver does the same.
Both accounts may experience financing adjustments, but the amounts do not necessarily match.
Possible reasons include:
- Different swap rates
- Different position volumes
- Different symbol specifications
- Different broker rollover times
- Different financing policies
- Different account conditions
Therefore, even perfectly synchronized positions can accumulate different overnight costs.
10. How to Check Swap Conditions in MT5
MT5 provides symbol information that can be used to inspect trading conditions for the instrument available on the Receiver terminal.
Depending on the broker and terminal configuration, traders can inspect the symbol's specification and relevant swap information.
Important values to review include:
- Swap Long
- Swap Short
- Swap type or calculation method
- Swap day or rollover information
- Contract specifications
The important point is to inspect the Receiver symbol, not only the Sender symbol.
11. Symbol Mapping and Swap Differences
Symbol mapping can create another layer of complexity.
For example:
Sender:
XAUUSD

Receiver:
XAUUSDm
Even though the symbols may represent the same underlying market, their trading specifications can differ.
These specifications may include:
- Swap values
- Contract size
- Digits
- Point size
- Trading sessions
- Minimum volume
- Volume step
- Stop Level
Therefore, symbol mapping should always be considered together with the Receiver broker's actual trading conditions.
12. Swap Is Not a Copier Synchronization Error
One important distinction is that swap normally does not represent a trade-copying failure.
The copier may successfully replicate:
- Entry
- Volume
- Stop Loss
- Take Profit
- Modifications
- Partial closes
- Full closures
Yet the Receiver can still have a different net result because its broker applies different financing costs.
In other words:
Trade synchronization ≠ Cost synchronization
A trade copier can synchronize trading events, but it cannot make two independent brokers use identical financing conditions.
13. Swap and Position Size
Swap is generally affected by the position size and the broker's calculation method.
This means lot management can indirectly affect the financing cost.
For example, if one Receiver uses:
Fixed Lot = 0.10
while another uses:
Balance Ratio = larger calculated volume
their accumulated swap charges or credits can be different even if both copy the same Sender trade.
Therefore, swap should be evaluated together with the Receiver's volume configuration.
14. Swap and Balance-Ratio Lot Management
Balance-ratio scaling can create different position sizes between Sender and Receiver accounts.
A larger Receiver position can produce a larger absolute financing cost if the swap is charged in a volume-dependent manner.
This does not mean balance-ratio scaling is inappropriate. It simply means that financing costs should be included when evaluating the resulting account behavior.
15. Swap and Maximum Lot Cap
A maximum lot cap limits the maximum position volume that COPYLATOR can use according to the configured volume rules.
Because swap can be volume-dependent, limiting excessive position size can also limit the absolute amount of financing exposure associated with oversized copied positions.
However, a Max Lot Cap is not itself a swap-management feature and does not guarantee a specific financing cost.
16. Time Filters and Overnight Swap
Time-based trading restrictions can also be relevant.
If a trading strategy is intended to operate only during certain hours, a Receiver can use its configured time controls to restrict when copying is permitted.
For strategies that do not require overnight exposure, a properly designed schedule may help reduce the number of positions that remain open through rollover.
However, automatically closing trades at a specific time changes the strategy's execution and should be tested before being used in live trading.
17. Auto-Close and the Trade-Off With Overnight Exposure
Suppose a strategy normally holds positions overnight but the Receiver has unusually high financing costs.
A trader may consider closing positions before rollover.
This can reduce or eliminate some overnight financing exposure, but it introduces a different trade-off:
- The trade may close before a favorable overnight move.
- The original strategy's holding period is changed.
- The Receiver's results may diverge from the Sender for reasons other than swap.
Therefore, auto-close should be considered a strategy decision rather than simply a way to remove swap.
18. Swap and Drawdown Protection
Swap can gradually affect account balance and equity.
For long-held positions, accumulated financing charges can contribute to the Receiver's overall account drawdown.
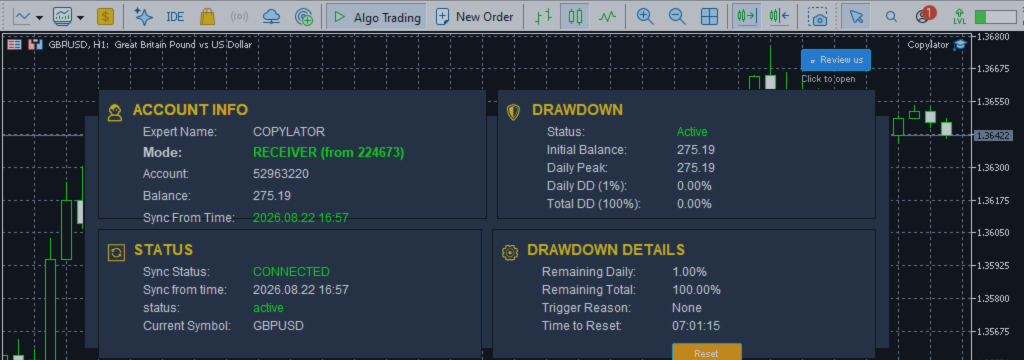
COPYLATOR's drawdown protection operates based on the Receiver account's configured drawdown settings. Therefore, financing costs that affect the Receiver's equity or balance can become part of the Receiver's actual account-level risk picture.
This reinforces the importance of configuring drawdown limits based on the Receiver account rather than simply copying the Sender's risk parameters.
19. Why Swap Differences Are Often Difficult to Notice
Unlike a rejected order, swap usually does not generate an obvious copier error.
The sequence can look completely normal:
Trade opened
     ↓
Trade copied
     ↓
SL/TP synchronized
     ↓
Position remains open
     ↓
Rollover occurs
     ↓
Swap applied
The trading system may therefore appear to be functioning perfectly while the Receiver's balance gradually diverges from the Sender.
20. Performance Reporting Should Separate Swap
When evaluating a copy-trading system, it can be useful to separate different sources of performance divergence.
| Factor | Possible Effect |
|---|---|
| Spread | Different entry/exit cost |
| Slippage | Different execution price |
| Commission | Different transaction cost |
| Swap | Overnight financing cost/credit |
| Lot Size | Different exposure |
| Broker Rules | Different trading behavior |
This makes it easier to determine whether performance differences are caused by the copier, execution conditions, account configuration, or financing costs.
21. Which Strategies Are Most Sensitive to Swap?
Swap sensitivity generally increases with holding time.
Short-Term / Intraday
If positions are normally closed before rollover, swap may have a relatively small role.
Swing Trading
Positions can remain open through multiple rollovers, making swap increasingly relevant.
Position Trading
Long holding periods can make financing costs a significant component of total trade performance.
Carry Strategies
Swap can become a central component of the strategy because the strategy may deliberately seek financing credits or manage financing costs.
22. Practical Example of Long-Term Divergence
Imagine a Sender and Receiver that copy the same position for several weeks.
Same entry Same direction Similar volume Same exit Different swap
The gross trading result may be similar, but the net result can differ because one account accumulates more financing costs.
This is particularly important when the strategy's expected profit per trade is relatively small compared with the accumulated financing cost.
23. Practical Ways to Manage Swap Differences
1. Compare Receiver Broker Swap Conditions
If overnight holding is an important part of the strategy, review the Receiver broker's swap conditions before selecting the account.
2. Check Both Directions
Do not check only Swap Long. If Reverse Mode or both directions are used, Swap Short can also be important.
3. Check Triple-Swap Rules
Identify the broker's designated rollover day and understand how the financing adjustment is applied.
4. Test on Demo
Use the intended Receiver broker and symbol configuration to observe how financing is actually applied.
5. Monitor Long-Running Positions
For trades held over multiple days, periodically review the accumulated swap amount.
6. Include Swap in Performance Analysis
Do not compare Sender and Receiver using gross trade profit alone. Compare net results after applicable trading costs.
24. Demo Testing Procedure
A practical swap test can be performed before live deployment.
- Open the intended Receiver demo account.
- Use the same symbols that will be traded live.
- Copy a small test position.
- Keep the position open through the broker's rollover.
- Check the account history.
- Record the swap charge or credit.
- Repeat for Buy and Sell where relevant.
- Check the broker's triple-swap day.
- Compare the result with the Sender's financing conditions.
This provides practical information about the actual cost structure of the Receiver account.
25. Common Mistakes
Mistake 1: Assuming Same Trade Means Same Net Result
Identical trade direction and entry do not guarantee identical costs.
Mistake 2: Checking Only Spread
Spread is visible at entry, while swap accumulates over time. Both can affect performance.
Mistake 3: Ignoring Reverse Mode
Reverse Mode can change the Receiver's position direction and therefore the applicable swap side.
Mistake 4: Ignoring Triple Swap
A single rollover can create a substantially larger financing adjustment than a normal day.
Mistake 5: Comparing Gross Profit Instead of Net Result
Financing, commissions, spread, and other costs should be considered when comparing Sender and Receiver performance.
26. Swap in Hedging and Netting Accounts
The account's trading model can also affect how positions are represented and managed.
On a Hedging account, multiple positions can exist independently. Each position can accumulate financing according to the broker's applicable rules.
On a Netting account, positions are aggregated into a net position per symbol. Changes in volume and direction can therefore affect the resulting net exposure and the financing associated with that position.
For either account type, the broker's actual symbol and financing rules remain the controlling factor.
27. COPYLATOR and Swap: What the Copier Controls
COPYLATOR can control and synchronize many aspects of the trading process, including:
- Trade replication
- Lot management
- Symbol mapping
- SL/TP synchronization
- Reverse Mode
- Partial Close
- Pending orders
- Direction filters
- Time-based restrictions
- Drawdown protection
However, the Receiver broker remains responsible for the financing conditions applied to the Receiver account.
Therefore:
COPYLATOR controls the copy process.

The Receiver broker controls the Receiver's swap conditions.
28. A Complete Cost Perspective
For professional copy-trading analysis, it is useful to think beyond the trade entry and exit.
COPIED TRADE | +-------------+-------------+ | | | Spread Commission Swap | | | +-------------+-------------+ | Net Result
Two accounts can therefore have identical trade signals but different net results because their cost structures are different.
29. Final Checklist for Managing Swap Differences
- Check the Receiver broker's Swap Long.
- Check the Receiver broker's Swap Short.
- Verify the swap calculation method.
- Check the rollover time.
- Identify the applicable triple-swap day.
- Check swap for the exact Receiver symbol.
- Consider the effect of Reverse Mode.
- Consider position volume and lot-management settings.
- Monitor financing on long-held positions.
- Include swap in performance reports.
- Test overnight positions on demo.
- Review financing costs before deploying long-term strategies live.
Conclusion
Swap is one of the most important hidden differences between Sender and Receiver accounts in MT5 copy trading.
A trade can be copied correctly from beginning to end while the Receiver still produces a different net result because the Receiver broker applies different financing conditions.
This becomes particularly important for swing, position, carry, and other strategies that hold trades through multiple rollovers.
With COPYLATOR, the Receiver can independently manage important aspects of the copy process, including lot sizing, Reverse Mode, symbol mapping, SL/TP synchronization, partial closes, time restrictions, and drawdown protection. However, swap remains a broker-level cost and must be evaluated separately.
The most reliable approach is to evaluate the actual Receiver broker and symbol, test overnight positions on demo, understand triple-swap rules, and include financing costs in the overall performance analysis.
A perfectly synchronized trade is not necessarily a perfectly identical trade economically. Understanding the difference between trade synchronization and cost synchronization is an essential part of professional MT5 copy trading.
Product link:
https://www.mql5.com/en/ market/product/191385