
My previous posts focused mainly on strategy development, optimization and Out-of-Sample validation. This time, I want to show what actually happened during a full trading week.
No selected backtest period and no optimized historical result – just the trades generated during the week.
Weekly Results
During the period shown, ATR Breakout completed 14 trades across GER40, US100 and US500.
Account: FTMO $100,000 Phase 1 Challenge
Net Result: +$1,399.71
Performance: approximately +1.40%
Total Trades: 14
Winning Trades: 6
Losing Trades: 8
Standard Risk: 0.3% per trade
Closed-trade peak-to-trough drawdown: approximately 1.64%
One US100 trade was accidentally executed with approximately 0.5% risk instead of the intended 0.3%. I noticed the incorrect setting and changed it back immediately afterwards.
I am mentioning this deliberately. If I want to document the real development and forward performance of the system, mistakes and adjustments are part of that process as well.
Day-by-Day Performance
The week was far from a straight line upward.
| Date | Daily Result | Cumulative Result |
|---|---|---|
| September 14 | +$576.54 | +$576.54 |
| September 15 | +$935.20 | +$1,511.74 |
| September 16 | -$608.29 | +$903.45 |
| September 17 | -$287.24 | +$616.21 |
| September 18 | +$783.50 | +$1,399.71 |
After a strong start, the system gave back a significant part of its profits during September 16 and 17.
The final trading day shown then recovered a large part of that drawdown and brought the overall result to approximately +1.40%.
For me, this is more informative than simply showing the final weekly profit.
Drawdown During the Week
Based on the sequence of closed trades, the highest reconstructed account balance during the week was approximately:
$101,981.11
The subsequent closed-trade low was approximately:
$100,308.95
This represents a peak-to-trough decline of approximately:
$1,672.16 or 1.64%
An important clarification:
This is a closed-trade peak-to-trough calculation, reconstructed from the trade history. It is not necessarily the official maximum FTMO equity drawdown, because the screenshot does not contain the intratrade floating equity.
Actual equity drawdown may therefore have been higher.
I prefer making that distinction rather than presenting a calculated number as something it is not.
Performance by Market
The individual markets produced very different results:
GER40: +$861.53
US100: -$744.11
US500: +$1,282.29
This was one of the most interesting aspects of the week.
US100 clearly struggled.
GER40 was profitable, while US500 produced the largest positive contribution and compensated for the losses on US100.
This also shows one potential advantage of applying the same underlying system across several indices: not every market necessarily needs to perform well during the same period.
Of course, one week is far too small a sample to draw conclusions about diversification benefits. That will require considerably more forward data.
6 Winners, 8 Losers – Still Profitable
The distribution of winning and losing trades is another interesting point.
Out of 14 trades:
6 were winners
8 were losers
That corresponds to a win rate of approximately 42.9%.
Nevertheless, the overall result was +$1,399.71.
This is a useful practical example of why I do not judge a trading strategy by win rate alone.
A system does not necessarily need to win most of its trades if the relationship between winning and losing trades produces a positive overall expectancy.
Again, 14 trades are nowhere near enough to establish that statistically. It is simply an observation from this particular week.
Full Trade History
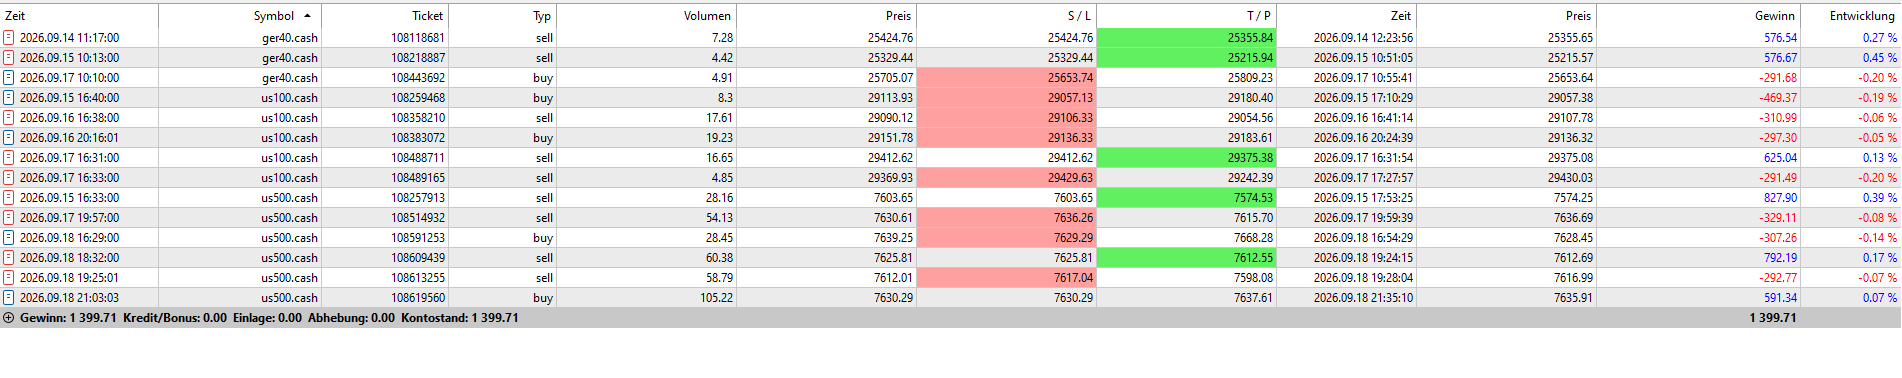
The screenshot above shows all 14 trades included in this update.
I prefer showing the complete history rather than only posting the final +1.40%.
That way, the losing trades, the different markets and the path to the final result remain visible.
Still an FTMO Phase 1 Challenge
The account is currently still in FTMO Phase 1.
A profitable week does not mean the challenge has been passed.
It also does not prove that ATR Breakout will remain profitable in future market conditions.
This is only one week and 14 trades – a very small sample.
For that reason, I want these updates to become a continuing record rather than using one profitable week as a performance claim.
If the next week is negative, that belongs in the record as well.
What I Take Away From This Week
Three things stand out to me.
First, the system finished approximately +1.40% while the standard risk was only 0.3% per trade.
Second, the path was not smooth. The reconstructed closed-trade drawdown reached approximately 1.64% before the strategy recovered.
Third, the markets behaved very differently. US100 lost money, while GER40 and US500 produced enough profit to leave the combined result positive.
For me, the next question is not whether this was a good week.
The more important question is:
What does the same system look like after 50, 100 or several hundred forward trades?
That is what I intend to continue documenting.
TH Systems ATR Breakout
If you are interested in the EA used in this FTMO Challenge, further information and the current settings are available on its MQL5 Market page.
TH Systems ATR Breakout ← link this text to your Market page
TH Systems
Discipline · System · Edge