 MetaTrader 5
 Experts
 지표
 스크립트
 라이브러리
 보관함
당사 팬 페이지에 가입하십시오

Position sizing from risk, using the broker's own tick value and volume step - MetaTrader 5용 라이브러리

- 조회수:
- 53
- 평가:
- 게시됨:
-
 이 코드를 기반으로 한 로봇이나 지표가 필요하신가요? 프리랜스로 주문하세요
프리랜스로 이동


Every lot size calculator that assumes one pip is worth ten dollars is wrong on gold, wrong on indices, wrong on JPY crosses and wrong on any account not denominated in USD - which is exactly where oversizing hurts. This header does the arithmetic from what the server actually publishes for the symbol instead.
What it does 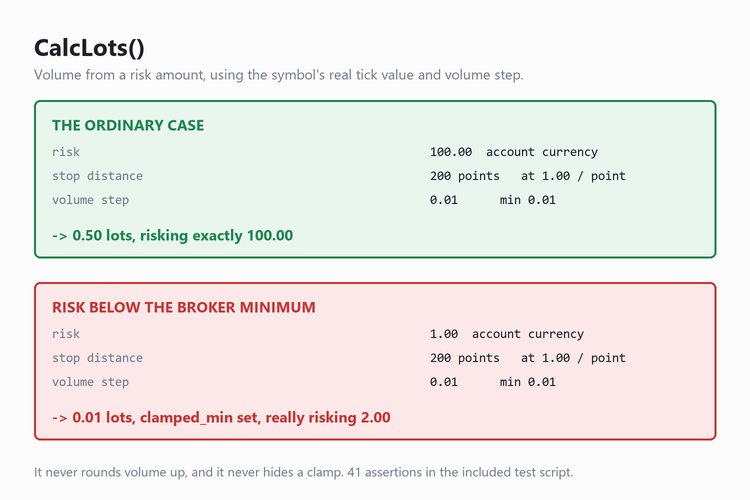
CalcLots() takes a risk amount in account currency, an entry price and a stop price, and returns the volume to trade together with what that volume really risks once the broker's constraints have been applied.
- It always rounds volume DOWN onto the broker's volume step. Rounding up would silently risk more than you asked for, which is the one thing a sizing routine must never do.
- When the requested risk is smaller than the minimum lot it does not pretend. It returns the minimum, sets clamped_min, and reports the risk that position actually carries - which will be larger than the request.
- It is side-agnostic. The stop may sit above or below the entry.
It also returns the stop distance in points and the value of one point per 1.00 lot, so a caller can show its working rather than just a number.
Why the maths is a separate header
Calc.mqh holds no terminal state. It takes a SymbolSpec struct - point, tick size, tick value, volume min/max/step, digits - so the whole of the sizing logic can be exercised offline against synthetic instruments.
SpecFromSymbol() is the only bridge to live data. It reads SYMBOL_TRADE_TICK_VALUE_LOSS first, because that is the figure the server uses when a trade goes against you, which is exactly the side a stop loss sits on; it falls back to SYMBOL_TRADE_TICK_VALUE for brokers that leave the loss variant at zero.
That separation is what makes the included test script possible at all.
The test script
RiskLotCalculatorTests.mq5 runs on any chart, with no broker connection and no history. It asserts 41 cases: volume-step rounding, both clamps and their flags, point value scaling when tick size differs from point size, a 5-digit major, gold, an index with a 0.1 lot step, both trade directions, and every rejection path - zero risk, negative risk, a stop sitting on the entry, and missing tick data.
Drag it onto a chart and read the Experts tab. It ends with ALL PASS, passed=41, failed=0.
Both files are self-contained: drop them in the same folder and the test script compiles as-is.
 Heiken Ashi ATR Blend
 combines smoothed Heiken Ashi candles, ATR-based volatility filtering, and fast/slow EMA trend confirmation to identify potential trend-change signals.
 Smart Loss Exit — early exit for losing positions (ATR adverse excursion, time in trade, EMA invalidation, RSI, money cap) with a CSV journal
Closes losing positions early, before the full stop-loss, when a rule says the trade is not coming back: adverse move beyond N x ATR, too long in loss, EMA trend flipped, RSI against the position, or a money cap. Never touches a position in profit. Observe-only mode journals what would be closed without closing anything. Every exit is written to CSV with the rule, the age and the maximum adverse excursion, so the rules can be tuned from data.
Accelerator Oscillator (AC)
The Acceleration/Deceleration Indicator (AC) measures acceleration and deceleration of the current driving force.
MACD Signals
Indicator edition for new platform.