Hemera
- Experts
-
Minh Truong Pham
 Hi, I'm Pham, a programmer and trader from Vietnam. I write indicators and Expert Advisors for MetaTrader 4 and 5. I write every product myself from scratch, without borrowing third-party code.
How I build and sell EAs - Versão: 1.1
- Ativações: 10
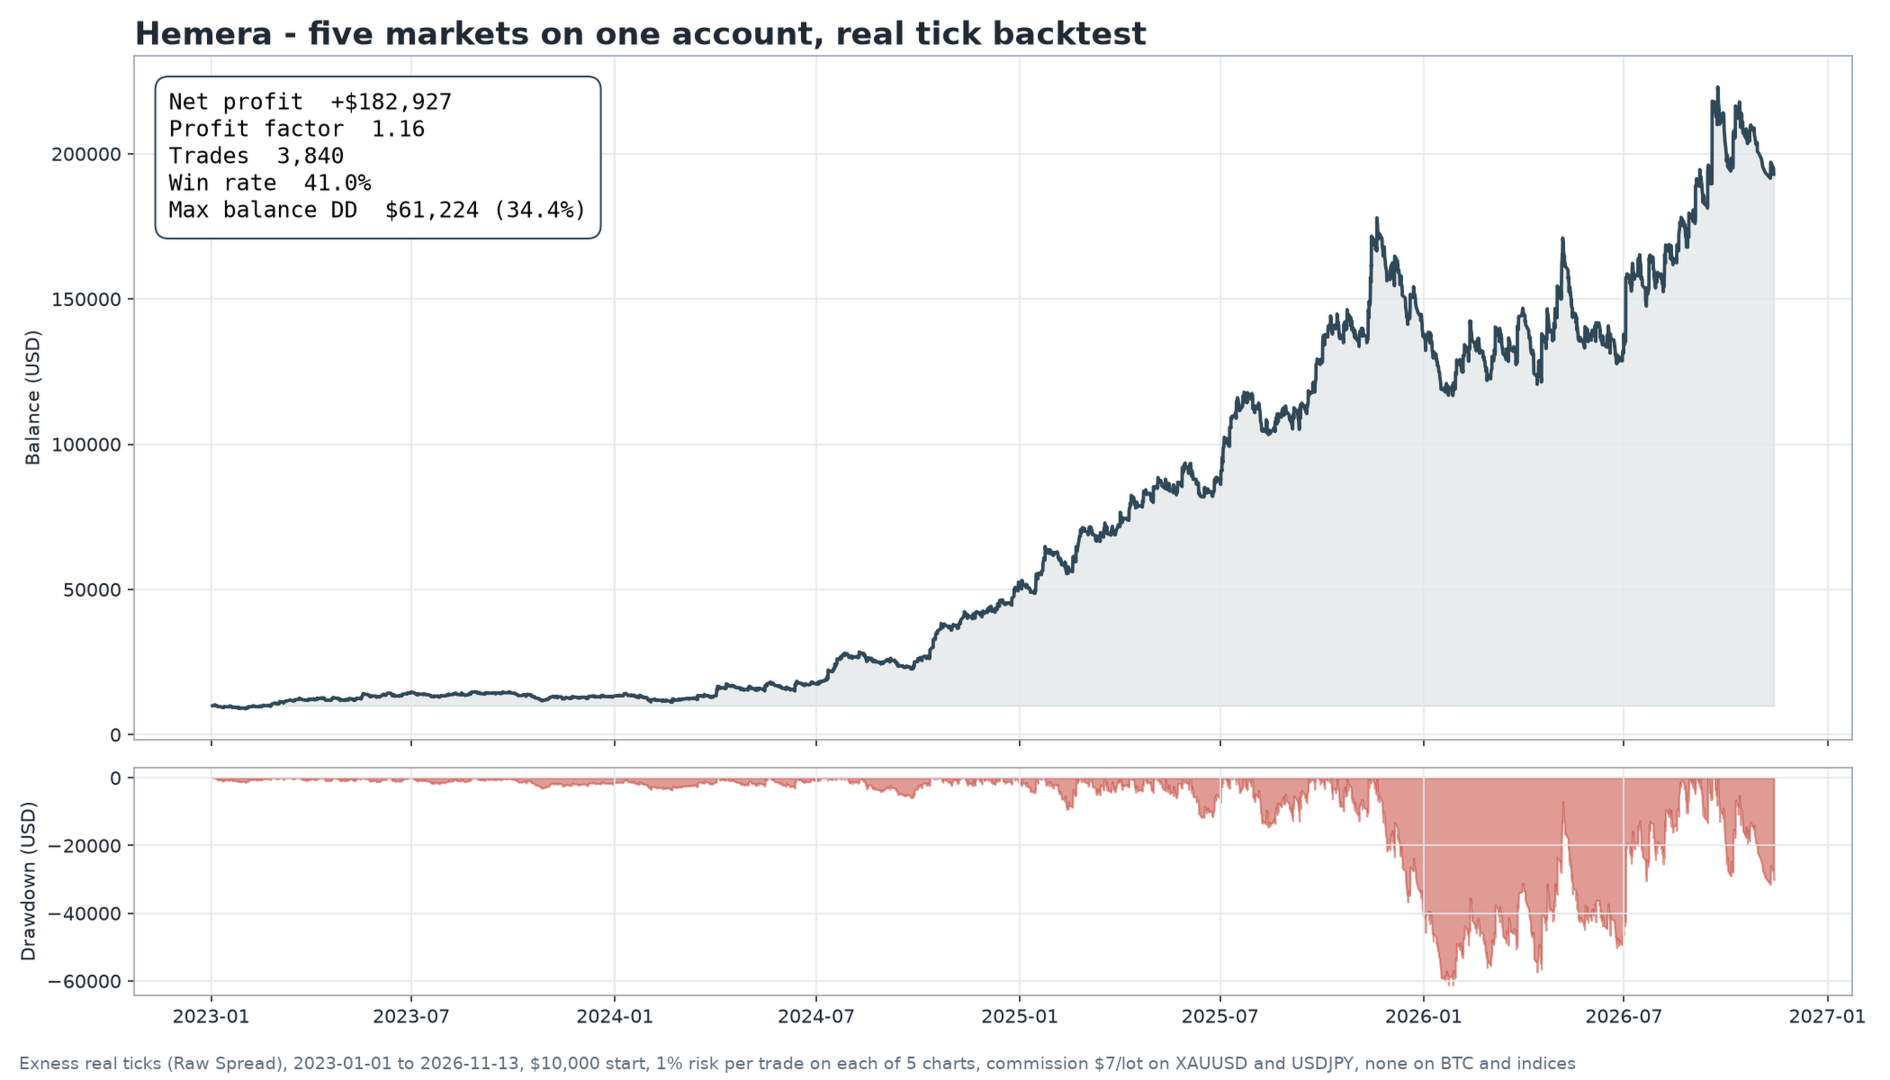
Hemera is one intraday breakout EA for five markets: XAUUSD, USDJPY, BTCUSD, US30 and DE40. In a real-tick backtest from 2 January 2023 to 13 November 2026, five charts on one $10,000 account at 1% risk per trade made +$182,927 (profit factor 1.16, 3,840 trades, max balance drawdown 34.4%). Stop loss on every trade. No grid, no martingale, no averaging down.
That's a backtest, not a promise. How it was run is below, bad stretch included.
At a glance
- Five markets, one file. Put it on a chart and it reads the symbol name and loads the settings tuned for that market.
- One position at a time per chart, at most one trade a day (two on USDJPY).
- Stop loss on every order from the moment it opens, and it's never widened.
- Lot from your risk % and the stop distance, recalculated for every trade.
- Nothing held overnight. Whatever is still open gets closed the same day on a fixed schedule.
- Trailing stop on the two indices once a trade runs.
The backtest in numbers
Exness real ticks (Raw Spread account), 2 January 2023 to 13 November 2026 (Bitcoin from January 2024, when my tick data for it starts). $10,000 start, risk 1% of balance per trade on each of the five charts. Commission $7 per lot on gold and USDJPY, none on Bitcoin and the two indices.
| Net profit | +$182,927 |
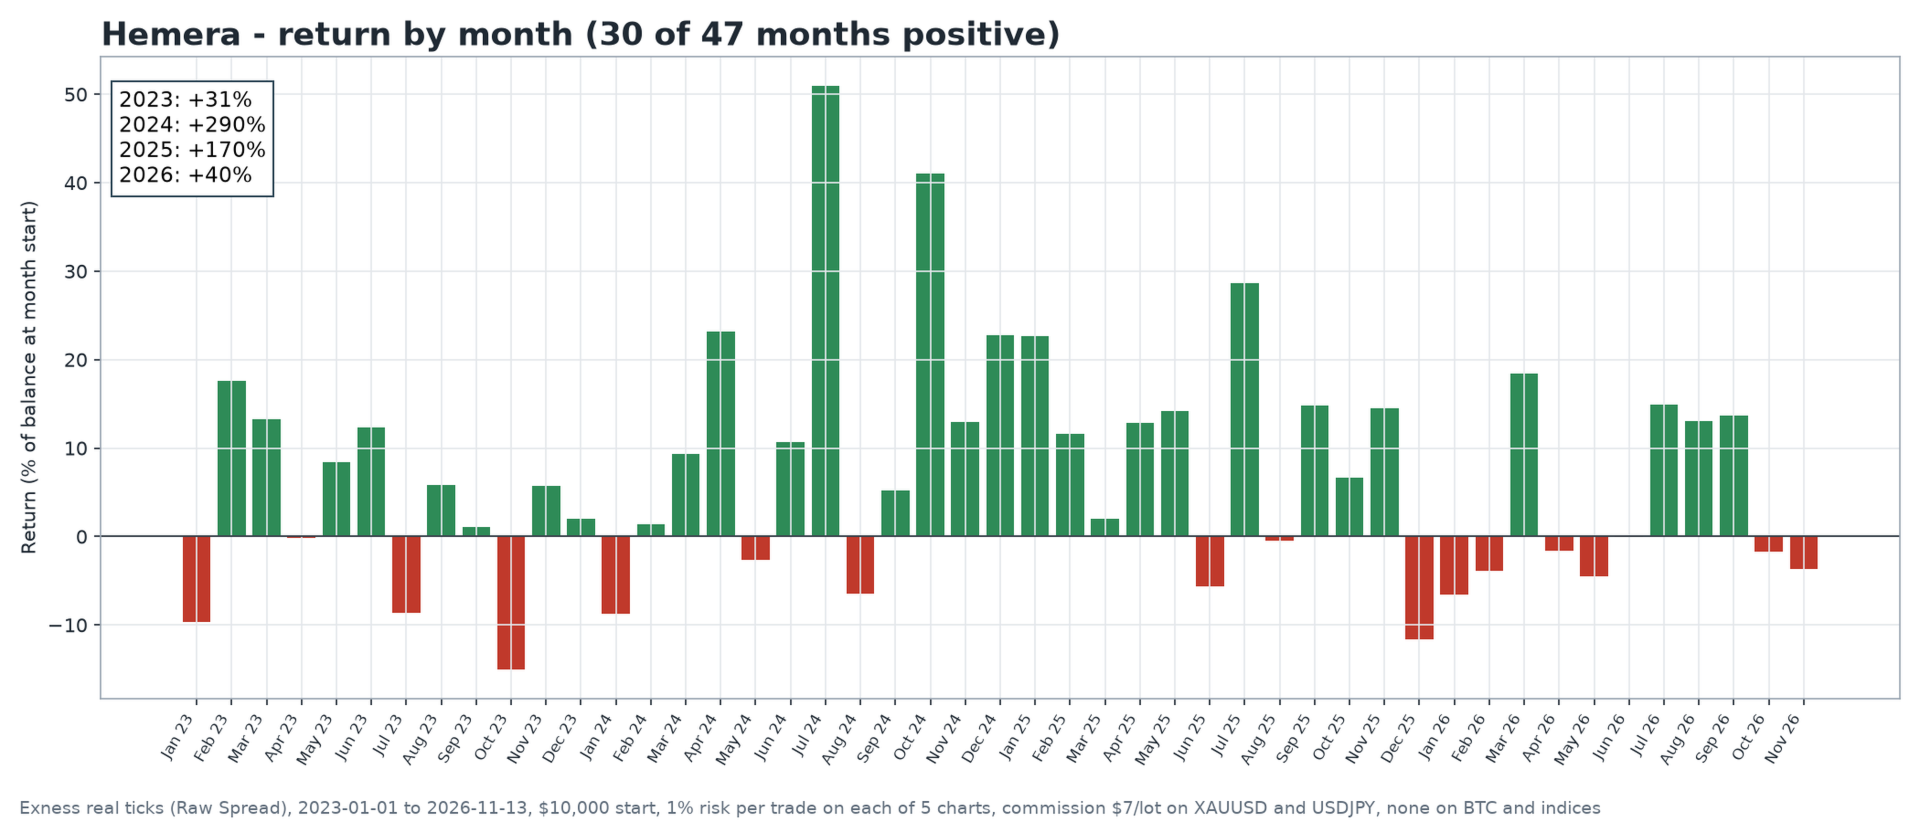
| 2023 / 2024 / 2025 | +31% / +290% / +170% |
| 2026 (to 13 Nov) | +40% |
| Profit factor | 1.16 |
| Trades | 3,840 |
| Win rate | 41.0% |
| Max drawdown (balance) | 34.4% |
| Positive months | 30 of 47 |
Most of that dollar figure is compounding. The lot grows with the balance, so a good month makes the next one bigger. Winners run until the daily exit or a trailing stop, so the average winner is a good deal bigger than the average loser ($836 against $501 across the whole test). The profit factor comes from that, not from a high hit rate.
And the bad stretch, because you should know it before you buy: the balance peaked on 19 November 2025, was 34.4% lower by 27 January 2026, and didn't make a new high until 21 August 2026. Only 30 of the 47 months were positive.
Each market on its own
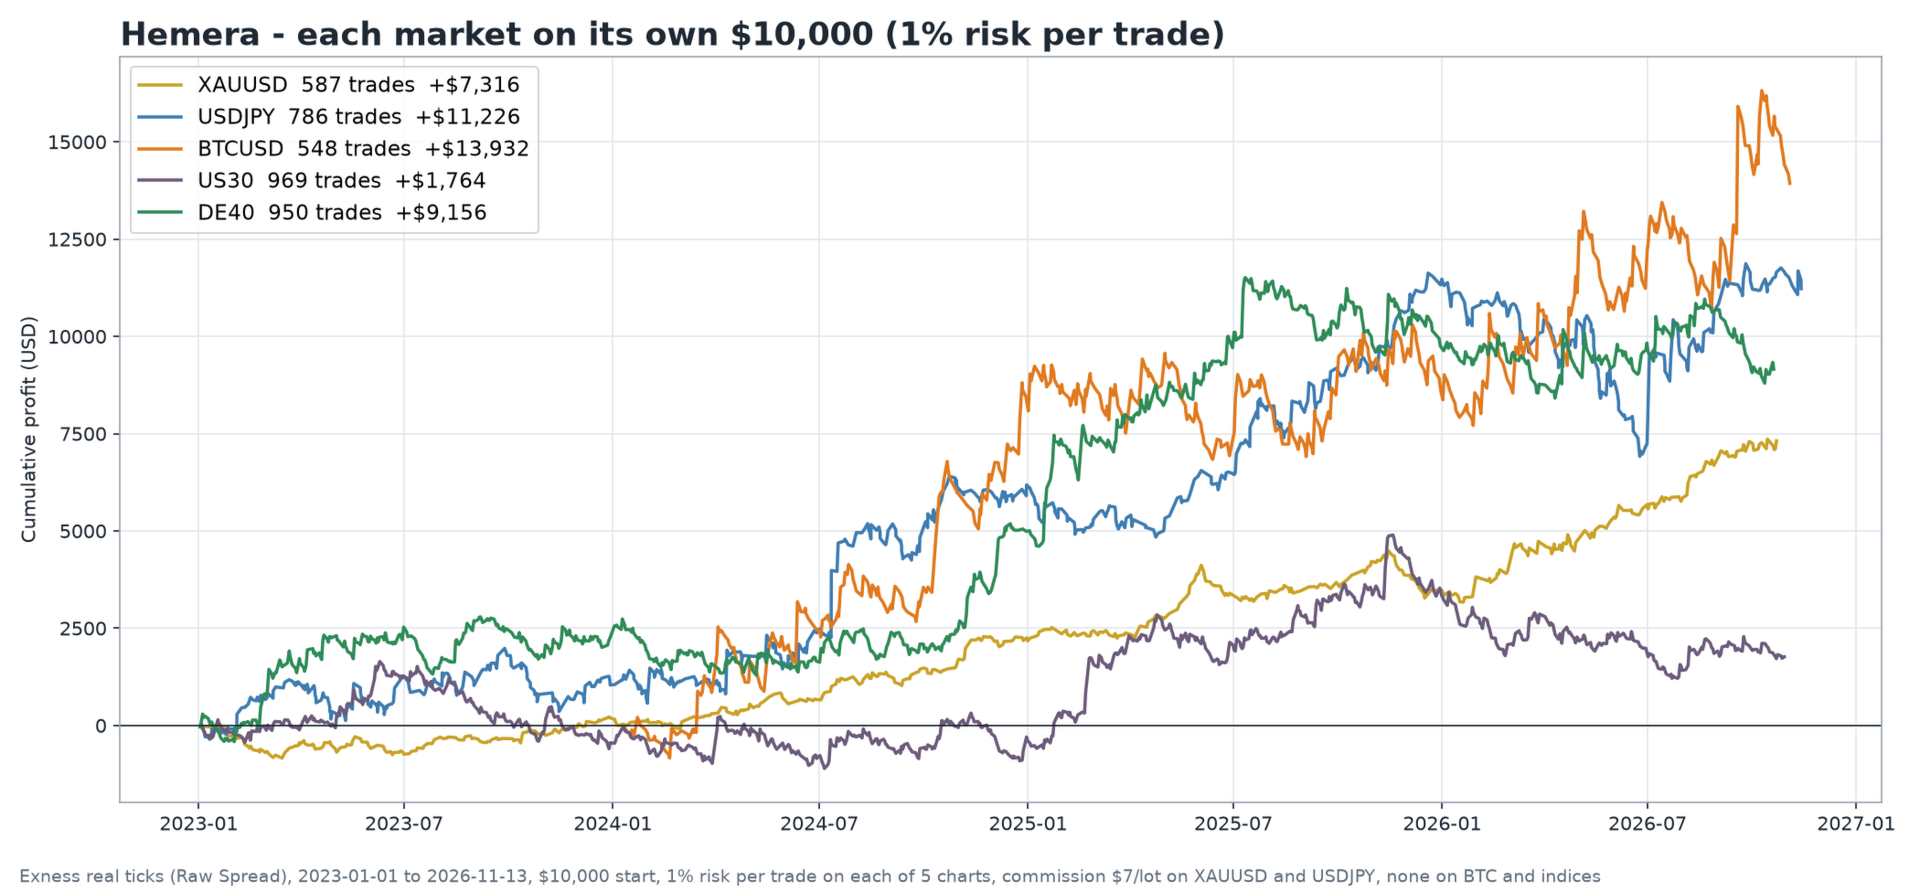
Same test, but each market alone on its own $10,000 at 1% risk, without five markets compounding into each other.
| Market | Trades | Net profit | Profit factor | Win rate | Max DD |
|---|---|---|---|---|---|
| XAUUSD | 587 | +$7,316 | 1.46 | 54.3% | 9.1% |
| USDJPY | 786 | +$11,226 | 1.23 | 45.7% | 21.8% |
| BTCUSD (from 2024) | 548 | +$13,932 | 1.21 | 29.6% | 13.9% |
| US30 | 969 | +$1,764 | 1.04 | 37.4% | 24.8% |
| DE40 | 950 | +$9,156 | 1.18 | 39.4% | 14.4% |
Gold has the smoothest curve of the five and Bitcoin made the most. US30 is the weak one at 1.04, barely better than flat. In 2026 so far gold (+$3,837) and Bitcoin (+$5,379) did the work while USDJPY (-$246), US30 (-$1,571) and DE40 (-$597) are down for the year. That's the reason to run several markets: the slow ones rarely line up.
The price next to the test
Hemera costs $199, once. In the test above, gold alone on its own $10,000 at 1% risk made +$7,316, and the five markets together on one $10,000 account made +$182,927.
I'm not telling you that you'll get those numbers. It's a backtest on one broker's ticks and next year won't look like the last four. But it shows the scale of the purchase against what the system did in testing, and you can rerun the test yourself in the Strategy Tester before you put real money on it.
Where the numbers come from
The figures come from my own tick-by-tick backtest engine, which runs the same rules as this EA. I checked the engine against the MT5 build trade by trade, on Exness data from July 2025 to November 2026. They agreed within two minutes on 96% to 99% of trades depending on the market: gold 196 of 202, USDJPY 276 of 279, Bitcoin 269 of 279, US30 338 of 341, DE40 323 of 325.
Brokers feed slightly different prices, so your own backtest won't be identical. The logic is.
Requirements
- Platform: MetaTrader 5, hedging or netting account. Hemera keeps one position per symbol, so on a netting account don't run another EA on the same symbol.
- Symbols: one chart each for XAUUSD, USDJPY, BTCUSD, US30, DE40. Broker suffixes and other names are fine: XAUUSDm, GOLD, US30m, USA30, DJ30, GER40, DE30, DAX40 are all recognised. If your broker uses something unusual, set Preset by hand.
- Other symbols: it'll run, on its currency-pair settings, and it says so in the Experts log. None of the numbers above cover those symbols, so I wouldn't.
- Timeframe: any. Hemera reads the data it needs itself.
- Account type: a low-spread account (Raw / ECN style) is what the test used.
- Capital and risk: 1% per trade on each chart is the tested setting, on $10,000. With all five on one account that can mean up to 5% at risk on a busy day, so I'd start at 0.5% per chart.
- Small accounts: when the risk-sized lot comes out below the broker's minimum, Hemera trades the minimum lot instead, but only if the margin fits and a stop-out would cost no more than five times your risk setting or 10% of the balance, whichever is larger. It writes the real figure to the Experts log. Past that it skips the trade and says so. On gold this starts below roughly $4,000 at 1%, so on a small account your real risk per gold trade is higher than the number you typed.
- VPS: recommended. Trades close on a clock, so the EA has to be running.
- Several charts: give each one its own magic number.
How to backtest it
Strategy Tester, model "Every tick based on real ticks", any timeframe, one of the five symbols.
One thing to set first. The tester can't see your broker's GMT offset, so Auto falls back to the "Server GMT offset" input. Leave it at 0 if your broker's server runs on UTC. If the server is on GMT+2/+3 (most brokers), set "Broker server time zone" to that option. Get this wrong and the EA trades at the wrong hours and the results mean nothing. On a live chart Auto works it out by itself.
Inputs
| Input | Default | What it does |
|---|---|---|
| Preset | Auto | Auto picks the market from the symbol name, or choose XAUUSD / USDJPY / BTCUSD / US30 / DE40 |
| Broker server time zone | Auto | Leave on Auto live. In the tester: Fixed for UTC servers, "GMT+2/+3" for most other brokers |
| Server GMT offset, hours | 0 | Used in Fixed mode and in the tester |
| Extra time shift, hours | 0 | Only for brokers whose clock is neither UTC nor GMT+2/+3 |
| Risk per trade (% of balance) | 1.0 | Lot is sized so a stop-out costs this % of balance |
| Fixed lot | 0 | Above 0 it trades this lot instead of the risk % |
| Max spread at entry, points | 0 (off) | Skips the entry while the spread is wider than this |
| Magic | 2026130 | Keeps Hemera's trades apart from other EAs |
The trading settings are fixed per market at the tested values. That's deliberate: those are the settings the numbers above belong to. The entry rules aren't published. That's the part that took the time.
Questions people ask
Can I run just one market? Yes. Each chart is independent. Gold alone had the smoothest curve in the test.
Why no trade today? It takes at most one trade a day per market, some days it stands aside on purpose, and some days price never gives it an entry. Several quiet days in a row are normal.
Does it hold trades overnight or over the weekend? No. Everything still open is closed the same day.
Does it trade on news? It doesn't read a calendar. The stop is on from the first second, and the spread filter can keep it out of the widest spikes if you set one.
Why does my backtest differ from yours? Different broker prices, spreads and session hours. Small differences are normal. If yours is wildly different, check the server time zone input first.
Support? Message me here on mql5 or leave a comment on the product page. Updates are free.
Past backtest results don't guarantee future returns. Trading with leverage carries risk, and you can lose money.