News of the day. Wednesday 30.09.2015
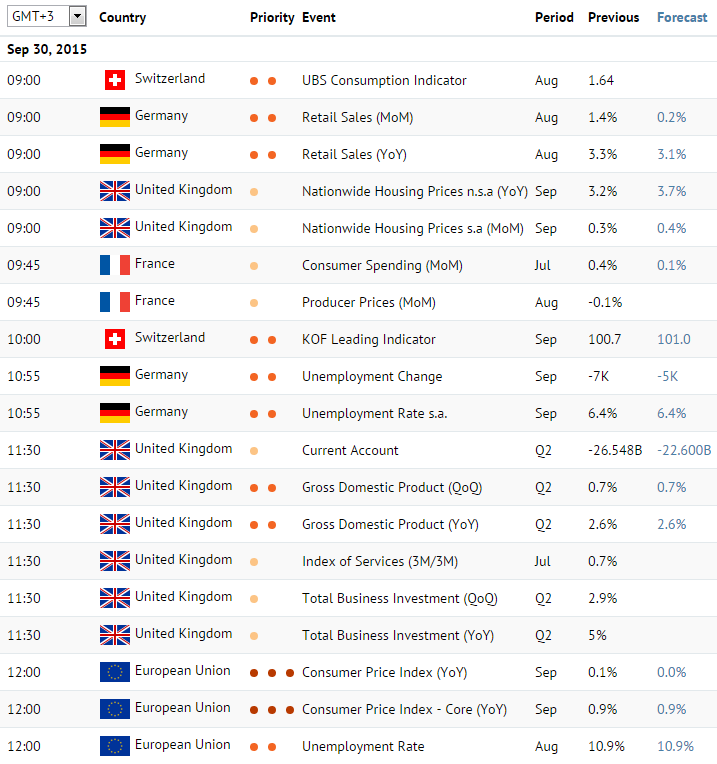
Wednesday is going to be full of important publications. The final Gross Domestic Product (QoQ) data for the second quarter of the year is due from the UK at 11:30 am (all times stated in GMT +3). After the first quarter reduction to 2.9%, the figure is expected to fall again to 2.6% in yearly terms. The market reaction is going to be moderate, as the data would match preliminary figure. Preliminary data on the Consumer Price Index for September is due at 12 pm in the eurozone. The index was expected to keep gradually falling and in September would have reached 0%, thus pressuring the Euro. July GDP (MoM) data is due at 3:30 pm in Canada. According to forecasts, the figure was going to fall to 0.2% after a growth by 0.5% in June, which would pressure the CAD. Fed’s Yellen Speech is due at the Third Annual Community Banking Research and Policy Conference in St. Louis, Missouri at 10 pm. The speech traditionally attracts market attention as it may have hints on the future direction of US monetary policy.
On Wednesday night at 2:50 am, the key Japanese indices Tankan are due. Amongst those, the most important one is the Tankan Large Manufacturing Index for the third quarter of the year, which is calculated based on surveys of the largest Japanese companies and represents business conditions in the manufacturing sector. According to forecasts, the index is going to fall from 15 to 13 points thus showing a slowdown of the Japanese economy. Finally, at 4 am September NBS Manufacturing PMI is due in China. The index is expected to continue its fall that started in July. In August, it already fell below the level of 50, which indicates a contraction of the manufacturing sector, and could decline further in September from 49.7 to 49.6 points. If forecasts are confirmed it could pressure all major currency pairs and commodity markets.
Wednesday is going to be full of important publications. The final Gross Domestic Product (QoQ) data for the second quarter of the year is due from the UK at 11:30 am (all times stated in GMT +3). After the first quarter reduction to 2.9%, the figure is expected to fall again to 2.6% in yearly terms. The market reaction is going to be moderate, as the data would match preliminary figure. Preliminary data on the Consumer Price Index for September is due at 12 pm in the eurozone. The index was expected to keep gradually falling and in September would have reached 0%, thus pressuring the Euro. July GDP (MoM) data is due at 3:30 pm in Canada. According to forecasts, the figure was going to fall to 0.2% after a growth by 0.5% in June, which would pressure the CAD. Fed’s Yellen Speech is due at the Third Annual Community Banking Research and Policy Conference in St. Louis, Missouri at 10 pm. The speech traditionally attracts market attention as it may have hints on the future direction of US monetary policy.
On Wednesday night at 2:50 am, the key Japanese indices Tankan are due. Amongst those, the most important one is the Tankan Large Manufacturing Index for the third quarter of the year, which is calculated based on surveys of the largest Japanese companies and represents business conditions in the manufacturing sector. According to forecasts, the index is going to fall from 15 to 13 points thus showing a slowdown of the Japanese economy. Finally, at 4 am September NBS Manufacturing PMI is due in China. The index is expected to continue its fall that started in July. In August, it already fell below the level of 50, which indicates a contraction of the manufacturing sector, and could decline further in September from 49.7 to 49.6 points. If forecasts are confirmed it could pressure all major currency pairs and commodity markets.