if actual > forecast = good for currency (for AUD in our case)
[AUD - Home Loans] = Change in the number of new loans granted for owner-occupied homes. It's a leading indicator of demand in the housing market - most homes
are financed, so it provides an excellent gauge of how many qualified
buyers are entering the market.
The total number of home loans
in Australia was up a seasonally adjusted 0.3 percent on month in July,
the Australian Bureau of Statistics said on Tuesday - coming in at
52,251.
That missed
forecasts for an increase of 1.0 percent, and down from the downwardly
revised 0.1 percent gain in June (originally 0.2 percent).
The
value of home loans for owner-occupied housing was flat on month at
A$17.058 billion - down from the 1.7 percent increase in the previous
month.
Investment lending climbed 6.8 percent on year to A$11.513 billion, after adding 0.1 percent a month earlier.
US Dollar Strengthens Broadly as Expectations for Rate Hike Accumulate
The major event of the week until now has been the poll of YouGov in UK for Scotland’s independence. The Sunday poll showed for first time that separatist take the lead with the British pound declining to fresh lows every day. Early on Tuesday morning the GBPUSDdropped to new 10-month low at 1.6064, the sterling remains the weakest major currency against the greenback but a retracement should be expected. Good news could come with the Manufacturing or Industrial production report today or with Mark Carney’s speech. The previous months’ investors were having great expectations for Bank of England monetary tight and for that reason the GBPUSD went up to 1.7187.
The US dollar strengthened further overnight as market participants’ expectations for Fed interest rate raise timing becomes more imminent. The Treasury 10-year yields advance as BlackRock said that the improving labor and indications for inflation suggest that the Fed would increase borrowing costs. That is diverging from almost all other major central banks monetary policies. The greenback rose against the Japanese Yen to fresh 5-year high at 106.33 and fundamentals are expected to remain supportive for the US dollar. At the same time the Japanese Consumer Confidence was reported today lower than expected.
Next week the FOMC would release its projections and most likely would further cut monthly asset purchases program. In addition, the geopolitical risk has diminished significantly compared to August and that does not help the Japanese Yen, therefore continuation of these developments would further increase the USDJPY.
Elsewhere, the Euro against the US dollar also dropped to fresh 14-month low at 1.2864 as the greenback was strengthening while the demand for Euro remains weak. On the data front today we are expecting the Manufacturing and Industrial Production for UK while in the evening investors would anticipate the JOLTS Job Opening for further clues on US labor market performance.
if actual > forecast (or actual data) = good for currency (for AUD in our case)
[AUD
- Home Loans] = Change in the level of a diffusion index based on surveyed consumers. Financial confidence is a leading indicator of consumer spending, which accounts for a majority of overall economic activity.
The Australian share market has suffered its worst fall in more than a
month, with investors influenced by losses on Wall Street and an
unexpected fall in consumer confidence.
All sectors fell but finance companies managed to post the slimmest losses.
The NAB and ANZ bank fell by 0.4 per cent and 0.25 per cent respectively, while the Commonwealth closed steady. Westpac gained 0.4 per cent.
The All Ordinaries index and the ASX200 both fell 34 points or 0.6 per cent to close at 5,574.
The mining sector
was one of the hardest hit; BHP Billiton dropped 0.8 per cent and Rio
Tinto 0.4 per cent, as the benchmark Chinese iron ore price softened a
touch more overnight Tuesday.
Atlas Iron dropped 4.2 per cent and Fortescue Metals Group fell 2.7 per cent, but gold miner Newcrest gained 1.25 per cent.
The Westpac Melbourne Institute Consumer Confidence index fell sharply and unexpectedly in its latest reading, erasing the gains it had made over the previous three months.
The index is now 4.6 points lower at 94, with any reading below 100 indicating that pessimists outnumber optimists.
The
Australian dollar was also hurt by the confidence index and continued
its slide on speculation that US interest rates will begin increasing
before those domestically.
Trading the News: Reserve Bank of New Zealand (RBNZ) Rate Decision(based on dailyfx article)
RBNZ Expected to Retain Current Policy Amid Period of ‘Interest Rate Stability’.
Will RBNZ Governor Graeme Wheeler Remove the Verbal Intervention on Kiwi?
According to a Bloomberg News survey, all of the 13 economist polled see
the Reserve Bank of New Zealand (RBNZ) keeping the interest rate on
hold at 3.50%, but the fresh batch of central bank rhetoric may produce
increased volatility in the NZD/USD as market participants weigh the
outlook for monetary policy.
What’s Expected:
Why Is This Event Important:
In light of the marked depreciation in the NZD/USD, the biggest risk for
surprise will be a removal of the verbal intervention on the kiwi, and a
further decline in the exchange rate may prompt Governor Graeme Wheeler
to adopt a more hawkish tone for monetary policy as it fuels imported
inflation.
Below-target inflation along with the slowdown in employment may
encourage the RBNZ to retain a period of ‘interest rate stability’ in
New Zealand, and the fresh batch of central bank rhetoric may spur a
further decline in the NZD/USD should it drag on interest rate
expectations.
Nevertheless, the RBNZ may no longer jawbone the kiwi as the lower
exchange rate raises the risk for imported inflation, and the NZD/USD
may face a more meaningful rebound ahead of the next Fed meeting on
September 17 should Governor Wheeler unexpectedly adopt a more hawkish
tone for monetary policy.
How To Trade This Event Risk Bearish NZD Trade: RBNZ Continues Talk Down Interest Rate Expectations
Need red, five-minute candle following the statement to consider a short New Zealand dollar trade
If market reaction favors selling kiwi, short NZD/USD with two separate position
Set stop at the near-by swing high/reasonable distance from entry; look for at least 1:1 risk-to-reward
Move stop to entry on remaining position once initial target is hit, set reasonable limit
Need green, five-minute candle to favor a long NZD/USD trade
Implement same setup as the bullish New Zealand dollar trade, just in the opposite direction
Potential Price Targets For The Release NZDUSD Daily
Will look for fresh highs should the NZD/USD carve a higher-low in July
Interim Resistance: 0.8430 (23.6% retracement) to 0.8450 (23.6% expansion)
Interim Support: 0.8160 (100% expansion) to 0.8180 (38.2% retracement)
Impact that the RBNZ rate decision has had on NZD during the last meeting
Period
Data Released
Estimate
Actual
Pips Change
(1 Hour post event )
Pips Change
(End of Day post event)
JUL 2014
07/23/2014 21:00 GMT
3.50%
3.50%
-79
-114
As expected, the Reserve Bank of New Zealand (RBNZ) raised the Official
Cash Rate (OCR) by another 25 pips to 3.50%, marking the fourth
consecutive interest rate hike since March 2014. However, the RBNZ
revised down the GDP forecast to 3.7% from 4% in June amid falling
export prices of diary and timber, and went onto say that there will ‘be
a period of assessment before interest rates adjust further towards a
more-neutral level’. The NZD/USD was pulled down nearly 90 pips
following the shift in the policy outlook, with the pair ending the day
at 0.8584.
The Australian Dollar appears poised to continue lower against the US
Dollar after sliding to the weakest level in close to five months. A
break below support at the bottom of a falling channel set from mid-June
exposes the 38.2% Fibonacci expansion at 0.9085, with a further push
beyond that targeting the 50% level at 0.8955. Alternatively, a reversal
back above the channel floor – now recast as resistance at 0.9195,
opens the door for a test of the 0.9245-64 area marked by a rising trend
line set from April and the 23.6% expansion.
The NZDUSD made new lows on the back of comments from RBNZ’s Wheeler who said that the currency was overvalued and that rates would stay on hold until 1Q of 2015. Meanwhile in Australia, the AUDUSD made it’s new move lows despite much stronger employment statistics that had the market questioning the seasonals.
Inflation data in the UK and the US, German Economic Sentiment, US
Federal Funds Rate and FOMC Press conference, GDP in New Zealand, US
unemployment claims, Scottish Independence Vote are the major topics in
Forex calendar. Check out these events on our weekly outlook.
Last week US jobless claims increased 11,000 last week, reaching
315K, exceeding the revised 304K posted in the week before. However,
the 4 week moving average was little affected, rising 750 to 304K, 7%
less than a year ago and still behind prerecession levels. Despite
sluggish, hiring in August, the general trend is positive. The economy
has generated an average of 215,000 jobs a month so far in 2014, up
from 194,000 in 2013 and wage growth is expected to rise in the coming
months alongside economic expansion. Will this trend continue?
Haruhiko Kuroda speaks: Tuesday, 5:30. BOE Governor Haruhiko Kuroda will press conference in Osaka. Market volatility is expected.
UK inflation data:
Tuesday, 8:30. Annual inflation rate dropped more than expected in
July, reaching 1.6% from 1.9% in June, lowering the chance of an
interest rate rise in 2014. Economists expected a smaller decline to
1.8%. The main cause for the sharp fall was price reduction in summer
clothing. Inflation was held below the BOE’s 2% target for the seventh
consecutive month, indicating the UK economy is stabilizing. However,
cost of living and income tax are still too high compared to wage
growth. Annual inflation is expected to reach 1.5% in August.
Eurozone German ZEW Economic Sentiment:
Tuesday, 9:00. German economic sentiment plunged in August to 8.6 from
27.1 in July. The 18.5 fall brought sentiment to its lowest level
since December 2012. Analysts expected a more modest decline to 18.2
points. The Current Conditions Index dropped to 44.3 from 61.8 in July,
missing predictions for a decline to 55.5. The ongoing geopolitical
tensions are the main reason for the sharp decline. Economic climate is
expected to decline further to 5.2.
US PPI:
Tuesday, 12:30. U.S. producer prices inched marginally in July rising
0.1%, in line with market forecast, following a 0.4% gain in the
previous month. The slow advance resulted from a decline in the cost of
energy goods, lowering prices of finished goods. Despite the
volatility in the PPI series, a trend of inflation is gathering pace,
easing the Central Bank’s concerns. The government introduced three new
indexes to the PPI series focusing on personal consumption. Personal
consumption less food and energy rose 0.2% in July after a 0.3% gain in
June. Excluding food, energy and trade services, the index increased
0.2% after a similar rise in June. Producer prices are predicted to
gain 0.1% in August.
UK employment data:
Wednesday, 8:30. The number of people claiming unemployment benefits in
the U.K. contracted more-than-expected in July, declining a seasonally
adjusted 33,600, after a 39,500 fall in the previous month, lowering
the Unemployment level to 6.4% in the three months to June. Economists
expected a smaller decline of 29,700. Meanwhile, the average earnings
index fell 0.2% in the three months to June after a 0.4% gain in the
three months to May. The number of job seekers is expected to decline
by 29,700 in August.
US inflation data: Wednesday,
12:30. U.S. consumer prices inched 0.1% in July, in line with market
forecast, following a 0.3% rise in June. On a yearly base, consumer
prices gained 2.0%, compared to June’s increase of 2.1%. Excluding the
volatile food and energy costs, July core consumer prices gained 0.1%
after posting the same gain in June. On an annual basis, core CPI rose
1.9%, unchanged from June. Economists expect core CPI to rise above the
2% target next year, prompting the Fed to raise rates in March. U.S.
consumer prices is expected to grow by 0.1% whiel Core CPI is predicted
to gain 0.2%.
FOMC Economic Projections, Rate statement and Press conference: Wednesday,
18:00. The Federal Reserve downgraded its outlook for the U.S. economy
in its June meeting but continued with tapering as planned. Growth
forecast was reduced to 2.1% from 2.3% due to the harsh winter in which
the economy contracted 0.1%. However, Fed Chair Janet Yellen stated
economic activity has rebounded in the second quarter. The Fed voted
unanimously to continue the cut the monthly purchases down to $35
billion. The labor market continues to improve together with underlying
strength in the broader economy. Economists believe inflation will rise
once the Unemployment rate reaches 6%. Regarding interest rate
increase, the Fed may stall its planned hike until reaching solid
growth.
New Zealand GDP: Wednesday, 22:45. New
Zealand economy expanded 1.0% in the first quarter following a revised
1.0% in the last quarter of 2013. Construction sector was the main
contributor to expansion, rising 12.5%, the largest since March 2000.
Retail trade edged up 1.4% and 4.4% on a yearly base. Mining rose 6.3%
in the first quarter. Household spending remained unchanged, despite
the 7.3% gain in real gross national disposable income, the largest
ever annual rise. Exports increased 3.1% for the quarter driven by an
18.6% rise in agriculture and fishing products.
Switzerland rate decision:
Thursday, 7:30. The Swiss National Bank (SNB) decided to maintain its
Libor target at the historically-low range of 0% to 0.25%, in line with
market forecast. The Central bank stated that economic growth picked
up in the first quarter, after a softer fourth quarter last year.
However, the Bank also noted that production capacities are still not
fully utilized and expects a pickup in economic activity during the
coming quarters. The downside risks remained unchanged including
weaker-than-expected growth in major economies, geopolitical tensions,
Eurozone financial difficulties. No change in rates is expected.
US Building Permits:
Thursday, 12:30. US building permits surged 15.7% in July, reaching a
seasonally adjusted annual pace of 1.09-million units. The rise came
after two consecutive declines. Economists expected starts to rise to a
969,000-unit rate. The housing market softened after the rise in
interest rates. The government reported last month that the
homeownership rate hit a 19-year low in the second quarter, while the
rental vacancy rate was the lowest in more than 19 years. The number of
Building permits is expected to reach 1.04 million units this time.
US Unemployment Claims:
Thursday, 12:30. The number of Americans seeking U.S. unemployment
benefits increased by 11,000 last week to 315,000. However, the
four-week average inched up only 750 to 304,000. The average remained
7.1% lower than last year. Unemployment benefits data can be volatile
around holidays and could explain the 11,000 rise. Overall, the Us
labor market continues to strengthen with a clear growth trend. Jobless
claims are expected to grow by 312,000 this week.
Janet Yellen speaks: Thursday,
12:45. Federal Reserve Chair Janet Yellen will speak in Washington DC.
She may talk about the US labor market and the prospects of a rate
hike following the taper period. Market volatility is expected.
US Philly Fed Manufacturing Index:
Thursday, 14:00. Business conditions in the Philadelphia area
improved in August surging to 28 from 23.9 in July. This was the third
consecutive rise and posting the highest reading since March 2011.
Economists expected a more modest rise to 19.7 points. However despite
the less encouraging new orders index, the general tone is positive.
Business conditions in the Philadelphia area are expected to decline
to 22.8.
Scottish Independence Vote: Thursday.
In September 18, Scottish voters will decide whether to split from the
United Kingdom or stay as one country with England, Wales and Northern
Ireland. A YouGov poll conducted for The Sunday Times and released on
Sunday showed the “yes” vote at 51% and “no” at 49%. Scotland’s first
minister and SNP leader Alex Salmond has been a vocal proponent of
independence. British Prime Minister David Cameron wants Scotland to
remain part of an undivided United Kingdom of Great Britain and
Northern Ireland. Uncertainty over the outcome of the Scottish
referendum weakened the pound.
Euro May Bounce on Strong Demand at First ECB TLTRO Operation
FOMC Announcement, Scotland Referendum May Stoke Euro Volatility
Euro selling pressure appears to be waning at last after eight consecutive weeks of losses that brought the single currency to the lowest level in 14 months against the US Dollar.
The operative question going forward is whether this precedes a period
of consolidation before a reinvigorated push downward or a correction
upward. The answer will be found in the markets’ response to a hefty
dose of high-profile event risk on the domestic and the external fronts
in the week ahead.
Looking inward, thespotlight is on the first ECB TLTRO operation due to be held on September 18.
The effort represents one of many easing tools that Mario Draghi and
company have deployed in recent months in an attempt to check the slide
toward deflation and repair the seemingly broken monetary policy
transmission mechanism that has made the central bank’s prior attempts
at stimulus largely ineffective. The scheme envisions offering Eurozone
banks cheap capital tied up with conditions pushing them re-lend it
while passing on low borrowing costs to the real economy, stoking
activity and boosting prices. The key variable in play will be the
size of the liquidity provision that is ultimately taken up by banks
tapping the facility. In a somewhat counter-intuitive turn of events, a
large capital allocation seems likely to offer support to the Euro.
Externally, the first major item of note is the FOMC policy
announcement. September’s outing will be accompanied by the release of
an updated set of forecasts for key metrics of US economic activity as
well as press conference from Chair Janet Yellen. The Fed has long
warned about complacently buoyant risk appetite as the end of QE3 looms
ahead next month. If policymakers opt to shake things loose with
upbeat activity projections and/or a hawkish outing from Ms Yellen,
this may put the Euro’s increasingly unattractive yield profile in
stark relief and reinvigorate bearish momentum.
The second is the Scottish Independence referendum. Opinion polls ahead
of the ballot essentially point to a 50/50 chance that Scotland will
secede from the UK. This implies that – whatever the final result – a
surge of volatility is likely to follow the results as those on the
wrong side of the outcome are forced to readjust positions. A final
vote in favor of independence is likely weigh on Sterling, sending
capital fleeing to alternatives. The Euro looks like a natural
beneficiary in such a scenario. Needless to say, a victory for the “no”
campaign will probably yield the opposite result.
The U.S. dollar ended its ninth successive weekly gain against a basket
of other major currencies on Friday as expectations for an early hike in
U.S. interest rates continued to bolster investor demand.
The US Dollar Index, which tracks the performance of the greenback
versus a basket of six other major currencies, was last down 0.18% to
84.32, but ended the week with gains of 0.39%. It was the longest series
of successive weekly gains in more than 17 years.
The dollar rallied to fresh six-year highs against the yen on Friday,
with USD/JPY up 0.23% to 107.33 at the close. For the week, the pair
added 2.05%.
Expectations that the Federal Reserve is growing closer to raising
interest rates continued to boost the dollar against the yen and the
euro, with the Japanese and European central banks likely to stick to a
looser monetary policy stance.
A study by the San Francisco Fed published on Monday indicated that
central bank officials see rates rising sooner than markets expect.
The Fed was expected to cut its asset purchase program by another $10
billion at its upcoming policy meeting next week which would keep it on
track for winding up the program in October, and to start raising
interest rates sometime in mid-2015.
Data on Friday showing that U.S. retail sales rose in August and another
report showing that consumer sentiment rose to a 14-month high in
September underlined the view that the economic recovery is deepening.
The yen remained under pressure after Bank of Japan Governor Haruhiko
Kuroda said Thursday that the bank would be prepared to immediately
loosen monetary policy or implement other measures if its 2% inflation
target becomes difficult to meet.
EUR/USD was up 0.33% to 1.2964 late Friday, holding above the 14-month trough of 1.2858 reached on Tuesday.
The single currency has remained under pressure since the European
Central Bank unexpectedly cut rates to record lows on September 4 and
unveiled new easing measures in a bid to shore up inflation in the euro
area.
The pound also pushed higher against the dollar on Friday, with GBP/USD
up 0.18% to 1.6267 in late trade. The pair fell to 10-month lows on
Wednesday as the prospects of Scottish independence rattled financial
markets.
However, uncertainty over what currency an independent Scotland would
use, as well as concerns over how much of the U.K. national debt it
would take on looked likely to cap sterling’s gains ahead of the
September 18 referendum.
In the week ahead, investors will be focusing on the outcome of
Wednesday’s Fed policy meeting. Fed Chair Janet Yellen was to hold a
press conference following the meeting.
Market participants will also be closely watching the outcome of Thursday’s independence referendum in Scotland.
Monday, September 15
Markets in Japan are to remain closed for a national holiday.
Switzerland is to produce data on producer price inflation.
In the euro zone, Germany’s Bundesbank is to publish its monthly report.
The U.S. is to release reports on manufacturing activity in the Empire State and industrial production.
Tuesday, September 16
The Reserve Bank of Australia is to publish the minutes
of its latest policy meeting, which contain valuable insights into
economic conditions from the bank’s perspective.
The U.K. is to publish data on consumer price inflation, which comprises the majority of overall inflation.
The ZEW Institute is to release its closely watched report on German economic sentiment, a leading indicator of economic health.
Canada is to release data on manufacturing sales.
The U.S. is to produce data on producer price inflation.
Wednesday, September 17
New Zealand is to publish data on the current account.
The
U.K. is to publish data on the change in the number of people employed
and the unemployment rate, as well as data on average earnings. In
addition, the Bank of England is to release the minutes of its latest
policy meeting.
The euro zone is to release revised data on consumer price inflation.
The
U.S. is to produce data on consumer prices. Later Wednesday, the
Federal Reserve is to announce its federal funds rate and publish its
rate statement. Fed Chair Janet Yellen is to hold a press conference
following announcement.
Thursday, September 18
New Zealand is to publish data on gross domestic
product, the broadest indicator of economic activity and the leading
measure of the economy’s health.
Japan is to release data on the trade balance, the difference in value between imports and exports.
Switzerland
is also to release a report on the trade balance. At the same time, the
Swiss National Bank is to announce its libor rate and publish its
monetary policy assessment.
The U.K. is to release data
on retail sales, the government measure of consumer spending, which
accounts for the majority of overall economic activity. Meanwhile,
Scotland is to hold its independence referendum.
The
U.S. is to produce a flurry of economic data, including reports on
initial jobless claims, building permits, housing starts and
manufacturing activity in the Philadelphia region.
Friday, September 19
Canada is to round up the week with data on consumer prices and wholesale sales.
if actual > forecast = good for currency (for AUD in our case)
[AUD - Home Loans] = Change in the number of new loans granted for owner-occupied homes. It's a leading indicator of demand in the housing market - most homes are financed, so it provides an excellent gauge of how many qualified buyers are entering the market.
==========
Australia Home Loans Add 0.3% In JulyThe total number of home loans in Australia was up a seasonally adjusted 0.3 percent on month in July, the Australian Bureau of Statistics said on Tuesday - coming in at 52,251.
That missed forecasts for an increase of 1.0 percent, and down from the downwardly revised 0.1 percent gain in June (originally 0.2 percent).
The value of home loans for owner-occupied housing was flat on month at A$17.058 billion - down from the 1.7 percent increase in the previous month.
Investment lending climbed 6.8 percent on year to A$11.513 billion, after adding 0.1 percent a month earlier.
Forum on trading, automated trading systems and testing trading strategies
AminStar, 2014.09.09 22:09
US Dollar Strengthens Broadly as Expectations for Rate Hike Accumulate
The US dollar strengthened further overnight as market participants’ expectations for Fed interest rate raise timing becomes more imminent. The Treasury 10-year yields advance as BlackRock said that the improving labor and indications for inflation suggest that the Fed would increase borrowing costs. That is diverging from almost all other major central banks monetary policies. The greenback rose against the Japanese Yen to fresh 5-year high at 106.33 and fundamentals are expected to remain supportive for the US dollar. At the same time the Japanese Consumer Confidence was reported today lower than expected.
Next week the FOMC would release its projections and most likely would further cut monthly asset purchases program. In addition, the geopolitical risk has diminished significantly compared to August and that does not help the Japanese Yen, therefore continuation of these developments would further increase the USDJPY.
Elsewhere, the Euro against the US dollar also dropped to fresh 14-month low at 1.2864 as the greenback was strengthening while the demand for Euro remains weak. On the data front today we are expecting the Manufacturing and Industrial Production for UK while in the evening investors would anticipate the JOLTS Job Opening for further clues on US labor market performance.Trading Video: FX Volatility Surge Puts Dollar and S&P 500 on Alert
if actual > forecast (or actual data) = good for currency (for AUD in our case)
[AUD - Home Loans] = Change in the level of a diffusion index based on surveyed consumers. Financial confidence is a leading indicator of consumer spending, which accounts for a majority of overall economic activity.
==========
Bad time for Australia. Share market falls as consumer confidence drops
The Australian share market has suffered its worst fall in more than a month, with investors influenced by losses on Wall Street and an unexpected fall in consumer confidence.
All sectors fell but finance companies managed to post the slimmest losses.
The NAB and ANZ bank fell by 0.4 per cent and 0.25 per cent respectively, while the Commonwealth closed steady. Westpac gained 0.4 per cent.
The All Ordinaries index and the ASX200 both fell 34 points or 0.6 per cent to close at 5,574.
The mining sector was one of the hardest hit; BHP Billiton dropped 0.8 per cent and Rio Tinto 0.4 per cent, as the benchmark Chinese iron ore price softened a touch more overnight Tuesday.
Atlas Iron dropped 4.2 per cent and Fortescue Metals Group fell 2.7 per cent, but gold miner Newcrest gained 1.25 per cent.
The Westpac Melbourne Institute Consumer Confidence index fell sharply and unexpectedly in its latest reading, erasing the gains it had made over the previous three months.
The index is now 4.6 points lower at 94, with any reading below 100 indicating that pessimists outnumber optimists.
The Australian dollar was also hurt by the confidence index and continued its slide on speculation that US interest rates will begin increasing before those domestically.
Trading the News: Reserve Bank of New Zealand (RBNZ) Rate Decision (based on dailyfx article)
According to a Bloomberg News survey, all of the 13 economist polled see the Reserve Bank of New Zealand (RBNZ) keeping the interest rate on hold at 3.50%, but the fresh batch of central bank rhetoric may produce increased volatility in the NZD/USD as market participants weigh the outlook for monetary policy.
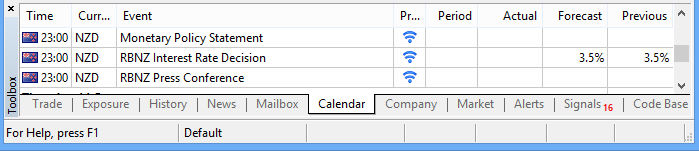
What’s Expected:
Why Is This Event Important:
In light of the marked depreciation in the NZD/USD, the biggest risk for surprise will be a removal of the verbal intervention on the kiwi, and a further decline in the exchange rate may prompt Governor Graeme Wheeler to adopt a more hawkish tone for monetary policy as it fuels imported inflation.
Below-target inflation along with the slowdown in employment may encourage the RBNZ to retain a period of ‘interest rate stability’ in New Zealand, and the fresh batch of central bank rhetoric may spur a further decline in the NZD/USD should it drag on interest rate expectations.
Nevertheless, the RBNZ may no longer jawbone the kiwi as the lower exchange rate raises the risk for imported inflation, and the NZD/USD may face a more meaningful rebound ahead of the next Fed meeting on September 17 should Governor Wheeler unexpectedly adopt a more hawkish tone for monetary policy.
How To Trade This Event Risk
Bearish NZD Trade: RBNZ Continues Talk Down Interest Rate Expectations
- Need red, five-minute candle following the statement to consider a short New Zealand dollar trade
- If market reaction favors selling kiwi, short NZD/USD with two separate position
- Set stop at the near-by swing high/reasonable distance from entry; look for at least 1:1 risk-to-reward
- Move stop to entry on remaining position once initial target is hit, set reasonable limit
Bullish NZD Trade: Governor Wheeler Removes Verbal Intervention- Need green, five-minute candle to favor a long NZD/USD trade
- Implement same setup as the bullish New Zealand dollar trade, just in the opposite direction
Potential Price Targets For The ReleaseNZDUSD Daily
- Will look for fresh highs should the NZD/USD carve a higher-low in July
- Interim Resistance: 0.8430 (23.6% retracement) to 0.8450 (23.6% expansion)
- Interim Support: 0.8160 (100% expansion) to 0.8180 (38.2% retracement)
Impact that the RBNZ rate decision has had on NZD during the last meeting(1 Hour post event )
(End of Day post event)
MetaTrader Trading Platform Screenshots
NZDUSD, M5, 2014.09.11
MetaQuotes Software Corp., MetaTrader 5, Demo
NZDUSD M5 : 35 pips price movement by NZD - Official Cash Rate news event
AUDUSD Technical Analysis (based on dailyfx article)
The Australian Dollar appears poised to continue lower against the US Dollar after sliding to the weakest level in close to five months. A break below support at the bottom of a falling channel set from mid-June exposes the 38.2% Fibonacci expansion at 0.9085, with a further push beyond that targeting the 50% level at 0.8955. Alternatively, a reversal back above the channel floor – now recast as resistance at 0.9195, opens the door for a test of the 0.9245-64 area marked by a rising trend line set from April and the 23.6% expansion.
Technical Analysis: AUDUSD & NZDUSD trade similarly for different reasons
The NZDUSD made new lows on the back of comments from RBNZ’s Wheeler who said that the currency was overvalued and that rates would stay on hold until 1Q of 2015. Meanwhile in Australia, the AUDUSD made it’s new move lows despite much stronger employment statistics that had the market questioning the seasonals.
Inflation data in the UK and the US, German Economic Sentiment, US Federal Funds Rate and FOMC Press conference, GDP in New Zealand, US unemployment claims, Scottish Independence Vote are the major topics in Forex calendar. Check out these events on our weekly outlook.
Last week US jobless claims increased 11,000 last week, reaching 315K, exceeding the revised 304K posted in the week before. However, the 4 week moving average was little affected, rising 750 to 304K, 7% less than a year ago and still behind prerecession levels. Despite sluggish, hiring in August, the general trend is positive. The economy has generated an average of 215,000 jobs a month so far in 2014, up from 194,000 in 2013 and wage growth is expected to rise in the coming months alongside economic expansion. Will this trend continue?
EURUSD Fundamentals (based on dailyfx article)
Fundamental Forecast for Euro: NeutralEuro selling pressure appears to be waning at last after eight consecutive weeks of losses that brought the single currency to the lowest level in 14 months against the US Dollar. The operative question going forward is whether this precedes a period of consolidation before a reinvigorated push downward or a correction upward. The answer will be found in the markets’ response to a hefty dose of high-profile event risk on the domestic and the external fronts in the week ahead.
Looking inward, thespotlight is on the first ECB TLTRO operation due to be held on September 18. The effort represents one of many easing tools that Mario Draghi and company have deployed in recent months in an attempt to check the slide toward deflation and repair the seemingly broken monetary policy transmission mechanism that has made the central bank’s prior attempts at stimulus largely ineffective. The scheme envisions offering Eurozone banks cheap capital tied up with conditions pushing them re-lend it while passing on low borrowing costs to the real economy, stoking activity and boosting prices. The key variable in play will be the size of the liquidity provision that is ultimately taken up by banks tapping the facility. In a somewhat counter-intuitive turn of events, a large capital allocation seems likely to offer support to the Euro.
Externally, the first major item of note is the FOMC policy announcement. September’s outing will be accompanied by the release of an updated set of forecasts for key metrics of US economic activity as well as press conference from Chair Janet Yellen. The Fed has long warned about complacently buoyant risk appetite as the end of QE3 looms ahead next month. If policymakers opt to shake things loose with upbeat activity projections and/or a hawkish outing from Ms Yellen, this may put the Euro’s increasingly unattractive yield profile in stark relief and reinvigorate bearish momentum.
The second is the Scottish Independence referendum. Opinion polls ahead of the ballot essentially point to a 50/50 chance that Scotland will secede from the UK. This implies that – whatever the final result – a surge of volatility is likely to follow the results as those on the wrong side of the outcome are forced to readjust positions. A final vote in favor of independence is likely weigh on Sterling, sending capital fleeing to alternatives. The Euro looks like a natural beneficiary in such a scenario. Needless to say, a victory for the “no” campaign will probably yield the opposite result.
The U.S. dollar ended its ninth successive weekly gain against a basket of other major currencies on Friday as expectations for an early hike in U.S. interest rates continued to bolster investor demand.
The US Dollar Index, which tracks the performance of the greenback versus a basket of six other major currencies, was last down 0.18% to 84.32, but ended the week with gains of 0.39%. It was the longest series of successive weekly gains in more than 17 years.
The dollar rallied to fresh six-year highs against the yen on Friday, with USD/JPY up 0.23% to 107.33 at the close. For the week, the pair added 2.05%.
Expectations that the Federal Reserve is growing closer to raising interest rates continued to boost the dollar against the yen and the euro, with the Japanese and European central banks likely to stick to a looser monetary policy stance.
A study by the San Francisco Fed published on Monday indicated that central bank officials see rates rising sooner than markets expect.
The Fed was expected to cut its asset purchase program by another $10 billion at its upcoming policy meeting next week which would keep it on track for winding up the program in October, and to start raising interest rates sometime in mid-2015.
Data on Friday showing that U.S. retail sales rose in August and another report showing that consumer sentiment rose to a 14-month high in September underlined the view that the economic recovery is deepening.
The yen remained under pressure after Bank of Japan Governor Haruhiko Kuroda said Thursday that the bank would be prepared to immediately loosen monetary policy or implement other measures if its 2% inflation target becomes difficult to meet.
EUR/USD was up 0.33% to 1.2964 late Friday, holding above the 14-month trough of 1.2858 reached on Tuesday.
The single currency has remained under pressure since the European Central Bank unexpectedly cut rates to record lows on September 4 and unveiled new easing measures in a bid to shore up inflation in the euro area.
The pound also pushed higher against the dollar on Friday, with GBP/USD up 0.18% to 1.6267 in late trade. The pair fell to 10-month lows on Wednesday as the prospects of Scottish independence rattled financial markets.
However, uncertainty over what currency an independent Scotland would use, as well as concerns over how much of the U.K. national debt it would take on looked likely to cap sterling’s gains ahead of the September 18 referendum.
In the week ahead, investors will be focusing on the outcome of Wednesday’s Fed policy meeting. Fed Chair Janet Yellen was to hold a press conference following the meeting.
Market participants will also be closely watching the outcome of Thursday’s independence referendum in Scotland.
Monday, September 15
- Markets in Japan are to remain closed for a national holiday.
- Switzerland is to produce data on producer price inflation.
- In the euro zone, Germany’s Bundesbank is to publish its monthly report.
- The U.S. is to release reports on manufacturing activity in the Empire State and industrial production.
Tuesday, September 16- The Reserve Bank of Australia is to publish the minutes
of its latest policy meeting, which contain valuable insights into
economic conditions from the bank’s perspective.
- The U.K. is to publish data on consumer price inflation, which comprises the majority of overall inflation.
- The ZEW Institute is to release its closely watched report on German economic sentiment, a leading indicator of economic health.
- Canada is to release data on manufacturing sales.
- The U.S. is to produce data on producer price inflation.
Wednesday, September 17- New Zealand is to publish data on the current account.
- The
U.K. is to publish data on the change in the number of people employed
and the unemployment rate, as well as data on average earnings. In
addition, the Bank of England is to release the minutes of its latest
policy meeting.
- The euro zone is to release revised data on consumer price inflation.
- The
U.S. is to produce data on consumer prices. Later Wednesday, the
Federal Reserve is to announce its federal funds rate and publish its
rate statement. Fed Chair Janet Yellen is to hold a press conference
following announcement.
Thursday, September 18- New Zealand is to publish data on gross domestic
product, the broadest indicator of economic activity and the leading
measure of the economy’s health.
- Japan is to release data on the trade balance, the difference in value between imports and exports.
- Switzerland
is also to release a report on the trade balance. At the same time, the
Swiss National Bank is to announce its libor rate and publish its
monetary policy assessment.
- The U.K. is to release data
on retail sales, the government measure of consumer spending, which
accounts for the majority of overall economic activity. Meanwhile,
Scotland is to hold its independence referendum.
- The
U.S. is to produce a flurry of economic data, including reports on
initial jobless claims, building permits, housing starts and
manufacturing activity in the Philadelphia region.
Friday, September 19