
October 21, 2026
USD/JPY lacks direction in the lower 158s; focus on the Australian dollar and the reaction to UK CPI
Market Overview
Ahead of next week’s Japanese and U.S. monetary policy meetings, USD/JPY is trading without a clear direction, mainly in the lower 158s.
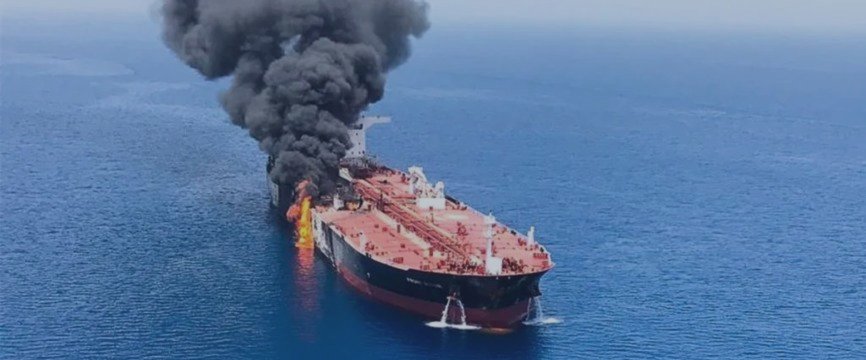
Following reports of a tanker fire in the Strait of Hormuz, NY crude futures rose from the $97 area early in the day to above $99.50. However, dollar buying in the FX market has been limited, and higher oil prices alone have had difficulty pushing USD/JPY higher.
The Japan-U.S. interest-rate differential and elevated oil prices are supporting USD/JPY, while official warnings against yen weakness are weighing on the pair just below 159. With factors on both sides, the market is struggling to establish a strong direction.
By currency, the Australian dollar has stood out after hawkish comments from the Reserve Bank of Australia’s deputy governor. Sterling’s reaction to UK CPI, which came in above expectations, has been modest. Watch for the possibility that the pound may struggle to extend its gains despite the positive data.
USD/JPY
In the previous New York session, weak U.S. housing data and hopes for progress in Middle East peace talks prompted dollar selling, briefly taking USD/JPY into the 157s.
The pair then recovered into the 158s after a diplomat denied reports that an agreement was close. Conflicting reports about the Middle East have caused the market to reverse direction within a short period.
Higher oil prices are again supporting the pair today, but gains in USD/JPY remain limited. With the Bank of Japan meeting and the FOMC meeting scheduled for next week, market participants are increasingly waiting for clues about policy from December onward.
The immediate focus is whether the pair can hold above 158. If it breaks below that level, the mid-157s may become the next downside reference. On a rebound, watch whether USD/JPY can absorb selling around the 200-day moving average and just below 159.
If the pair continues to struggle to rise despite higher oil prices, short-term profit-taking could become more likely.
Oil and the Middle East
Concerns about oil supply and transportation have intensified again following reports that a tanker carrying more than 2 million barrels of crude caught fire in the Strait of Hormuz.
NY crude futures climbed above $99.50, bringing the $100 level into focus.
The previous day, oil fell on unconfirmed reports suggesting progress in peace talks, then reversed after those reports were denied. The market remains vulnerable to headlines about negotiations and shipping activity.
The U.S. weekly petroleum inventory report is due at 23:30 Japan time tonight. Watch whether a decline in inventories adds to supply concerns or an increase in inventories limits the rise in oil prices.
For FX, the key question is whether higher oil prices are accompanied by rising U.S. yields and dollar buying. If higher oil is instead seen as a burden on economic growth, it may not lead to straightforward dollar strength.
The Australian Dollar and the RBA
The Australian dollar has been notably strong among the major currencies today.
RBA Deputy Governor Hauser said the inflation outlook had deteriorated significantly compared with the Bank’s August projections. He also made clear that the RBA would not tolerate inflation expectations moving away from its target.
Following these comments, Goldman Sachs changed its forecast for the November meeting from no change to a rate hike. Interest-rate futures briefly put the probability of a November hike above 90%.
AUD/JPY rose into the 111.20s, reaching its highest level in about a month. The Australian dollar has also gained against both the U.S. dollar and the New Zealand dollar, indicating currency-specific buying that is not dependent on the direction of the U.S. dollar.
The next important event is Australia’s CPI release on October 28. Evidence of accelerating inflation could reinforce expectations of a November rate hike, while a weak reading could prompt a rapid reassessment of the rate-hike expectations that have recently been priced in.
UK CPI and Sterling
UK CPI for September rose 3.5% year over year, above both the market forecast of 3.4% and the previous reading of 3.1%.
Following the previous day’s strong employment data, this result supports expectations of further tightening by the Bank of England. However, GBP/USD rose into the 1.3380s after the release, but its gains were limited.
The pound’s failure to accelerate higher despite a run of strong data suggests that some rate-hike expectations may already be reflected in prices.
The first focus for GBP/USD is whether it can break above the previous day’s high near 1.3409. Beyond that, the 1.3470–1.3500 area is a potential upside reference.
If the pair struggles to advance and a correction gathers pace, the Ichimoku conversion line near 1.3273 will be an important downside level to watch. GBP/JPY’s ability to hold above 211 is also worth monitoring.
At 22:00 Japan time tonight, Bank of England Governor Andrew Bailey is scheduled to speak. The topic is central bank independence, so watch for whether he makes any specific comments on monetary policy.
The Euro and the Situation in France
EUR/USD is expected to trade mainly in the lower 1.12s.
Political and fiscal uncertainty in France is capping the euro, while expectations of further ECB rate hikes and a pause in dollar strength are providing support. EUR/USD briefly rebounded to around 1.1260 in the previous New York session, but selling on rallies is likely to emerge in the upper 1.12s.
The immediate questions are whether the pair can hold 1.1200 and, if it rebounds, whether it can move above around 1.1260.
Moody’s is scheduled to review France’s sovereign credit rating on Friday. If concerns about a downgrade intensify, the euro’s recovery could be limited.
EUR/JPY is trading mainly in the 177s, with resistance just below 178 in focus. If USD/JPY falls, EUR/JPY is also likely to struggle to extend its rebound.
New Zealand CPI Early Tomorrow
New Zealand’s third-quarter CPI is due at 06:45 Japan time on October 22.
-
Quarter over quarter: forecast +0.9%; previous +1.5%
-
Year over year: forecast +3.8%; previous +4.1%
Inflation is expected to ease but remain elevated.
A result above expectations could support the New Zealand dollar by strengthening expectations of monetary tightening by the Reserve Bank of New Zealand. Conversely, a larger-than-expected slowdown could highlight the difference in policy expectations between Australia and New Zealand, potentially sustaining Australian dollar buying and New Zealand dollar selling.
With Australian-dollar-specific buying strengthening today, watch whether the New Zealand CPI changes the relative strength of the Australian and New Zealand dollars.
U.S. Data and the Treasury Market
The main U.S. economic release tonight is the MBA Mortgage Applications Index. There are few other U.S. indicators likely to change the overall market direction.
As a result, movements in oil, U.S. Treasury yields, and equities may provide the main cues for FX.
A $13 billion U.S. 20-year Treasury auction is scheduled for 02:00 Japan time on October 22. Strong demand could push yields lower and weigh on the dollar; weak demand could lift yields and support the dollar.
Earnings are also due from Meta, Tesla, Texas Instruments, IBM, and other companies. Watch whether reactions in U.S. technology shares affect risk appetite and spill over into the yen crosses.
Key Points for Overseas Markets
-
Whether USD/JPY can hold in the lower 158s
-
Whether the pair’s gains remain limited despite higher oil prices
-
Whether NY crude tests $100
-
The results of the U.S. weekly petroleum inventory report and 20-year Treasury auction
-
Whether the Australian dollar’s advance continues in European and U.S. trading
-
Whether GBP/USD can break above around 1.3409
-
Whether EUR/USD can hold above 1.1200
-
How far New Zealand CPI deviates from expectations early tomorrow
Scenario Analysis
The main scenario is for USD/JPY to consolidate in the lower 158s, while currencies with currency-specific catalysts, such as the Australian dollar, remain relatively firm.
If oil prices and U.S. yields rise together, USD/JPY may be more likely to test higher levels. However, official warnings remain a concern just below 159, so it will be important to see whether upward momentum can continue.
Conversely, if hopes for peace talks push oil lower and U.S. yields also fall, USD/JPY could break below 158 and correct toward the mid-157s.
Sterling failed to extend its gains after strong CPI data. The key is therefore not simply the positive data itself, but whether the pound can move on to set new highs.
Summary
Today, USD/JPY has reacted only modestly to higher oil prices, as market participants increasingly wait for next week’s Japanese and U.S. policy meetings. With factors supporting both sides, the pair is likely to continue searching for direction in the lower 158s.
The Australian dollar has been notably strong on expectations of an earlier RBA rate hike. Sterling, meanwhile, has seen only a limited reaction to the upside CPI surprise, as rate-hike expectations and profit-taking appear to be competing.
Tonight, the focus is on the relationship between oil and U.S. yields. Early tomorrow, New Zealand CPI will be in focus. While keeping USD/JPY’s range in mind, watch for differences in currency strength driven by changing monetary policy expectations.