NostosNDX MT5
- Experts
- 버전: 1.0
- 활성화: 20

Nasdaq-100 (US100) buy-the-dip · Holds a few days · Long only · Position size capped · No grid / no martingale
- The current price is available for the next 10 copies. The price then rises by $10 every 10 copies.
- Final price: $99
Welcome to Nostos NDX!
Nostos NDX buys meaningful short-term dips in the Nasdaq-100 and sells on the first up close. It checks the market once a day, just before the US close, and holds a position for a few days at most.
Short dips in the Nasdaq-100 have tended to bounce back within days. In daily data from 2008 to 2026, the same rule was profitable in every sub-period tested (2008–2014, 2015–2020, 2021–2024, 2025–2026) and for lookbacks from 3 to 30 days, and its average trade was many times larger than holding for the same number of days from random dates. Shallow dips are skipped because their bounce is too small to pay for costs.
No grid, no martingale, no averaging down. One position at a time. There is no price stop loss by design (see IMPORTANT); risk is controlled by position size and a 10-day time exit.
Key Features:
- Checks once a day at 15:55 New York time (just before the US close)
- Buys when the close breaks the 3-day low by at least 0.2 × daily ATR
- Doubles the size when the close is also a 10-day low (deeper dips bounce more)
- Sells on the first close above the previous close, or after 10 trading days
- Position size as a % of equity, with a hard cap of 60% that settings cannot exceed
- Trades: About 30 per year (2–3 per month)
- Holding time: A few days (average about 2.6 days, maximum 10 trading days)
Daily close: the price at 15:55 New York time is used as the day's close.
Entry (long only): buy when today's close is below the lowest close of the previous 3 days by at least 0.2 × daily ATR(20).
Size: ExposurePercent of equity (default 30%). If the close is also below the lowest close of the previous 10 days, the size is doubled. Total position value is capped at 60% of equity.
Exit: the first day whose close is above the previous day's close, or after 10 trading days.
Backtesting:
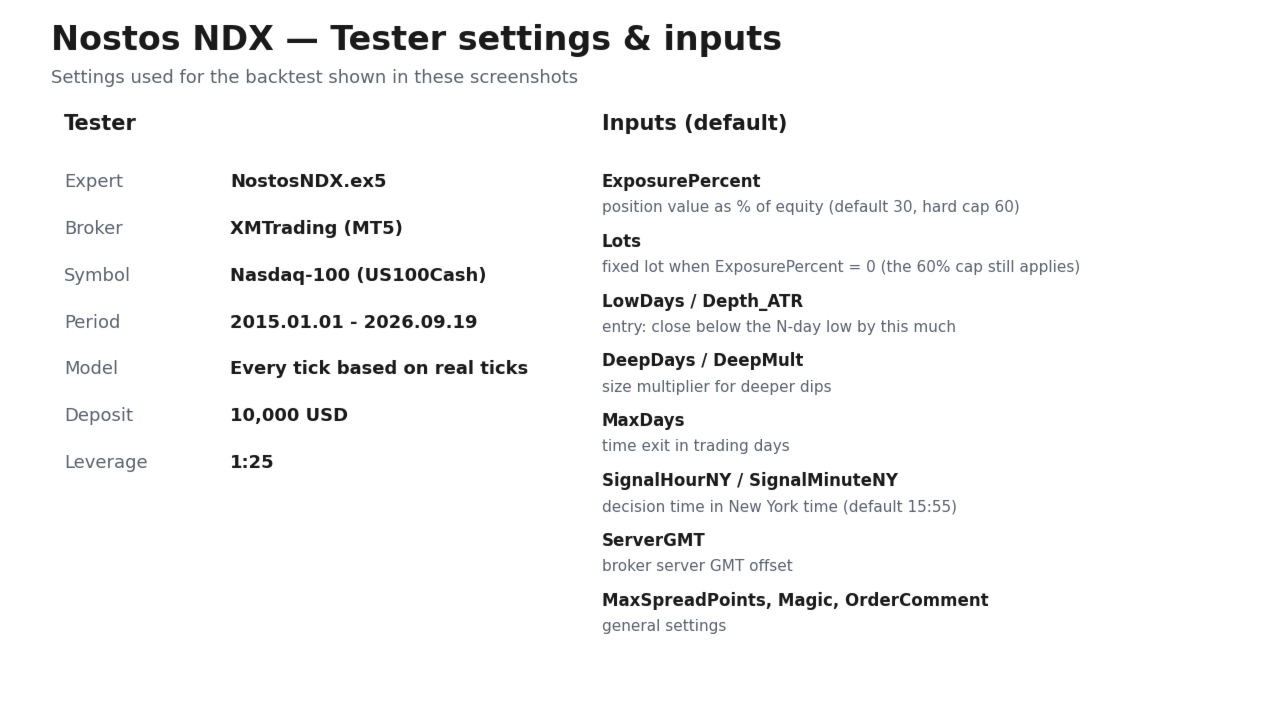
Test on Nasdaq-100 CFD (e.g. US100, USTEC, NAS100) with the default settings, using "Every tick based on real ticks" where available.
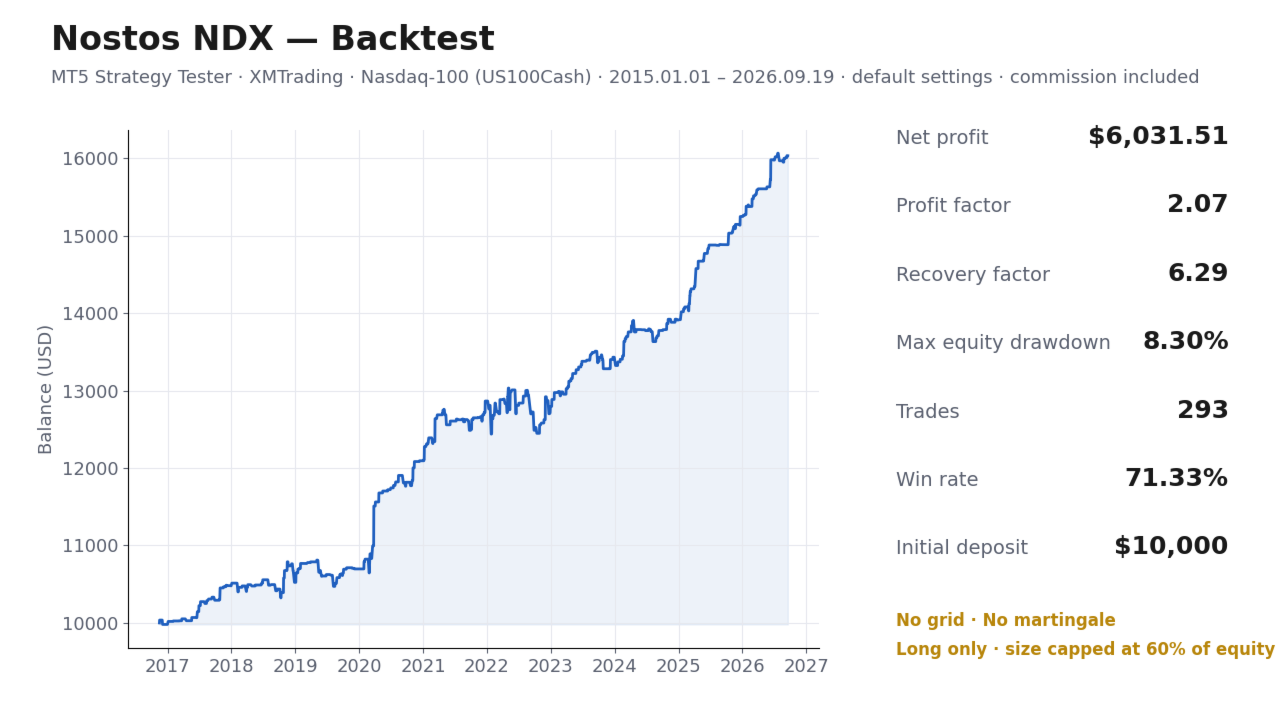
Our test (MT5 Strategy Tester, broker XMTrading (symbol US100Cash), Nasdaq-100, 2015.01–2026.09, position size 30% of equity (default), $10,000, model: every tick based on real ticks, default settings):
- Net profit: +$6,031.51
- Trades: 293
- Profit factor: 2.07
- Recovery factor: 6.29
- Max equity drawdown: 8.30%
- Win rate: 71.33%
- Average win / loss: +$55.93 / −$67.35
- Years positive: 10 of 11 (2022 negative)
Good to know:
- Low frequency: about 2–3 trades a month. Some months have none.
- No price stop loss. The worst single trade in the tests was about −10% of the position value (2022). A deep crash can cause a larger loss, so keep the default size unless you understand the risk.
- At the default 30% exposure, the backtest equity drawdown was about 8%. Resampling the same trades in a different order gave drawdowns up to about 2–3 times the historical one, so plan for that.
- Long only: a multi-year bear market (like 2000–2002, which is outside the test data) would be the hardest environment for this EA.
- The XM US100Cash price history used in the backtest starts in November 2016.
Setup:
Attach the EA to one Nasdaq-100 CFD (e.g. US100, USTEC, NAS100) chart (any timeframe). Recommended balance: $1,000 (so the minimum lot stays within the cap). Account: Hedging or netting. Any broker with a Nasdaq-100 CFD; VPS recommended.
Parameters:
- ExposurePercent – position value as % of equity (default 30, hard cap 60)
- Lots – fixed lot when ExposurePercent = 0 (the 60% cap still applies)
- LowDays / Depth_ATR – entry: close below the N-day low by this much
- DeepDays / DeepMult – size multiplier for deeper dips
- MaxDays – time exit in trading days
- SignalHourNY / SignalMinuteNY – decision time in New York time (default 15:55)
- ServerGMT – broker server GMT offset
- MaxSpreadPoints, Magic, OrderComment – general settings
IMPORTANT:
Check the server GMT offset input. The default is correct for brokers whose server time is GMT+2 in winter and GMT+3 in US summer time (most brokers). For other brokers, set it manually, or the trading times will be shifted.
Why there is no price stop loss: this EA buys temporary dips. In our tests, adding a stop at 1.5–4 × daily ATR lowered the profit factor from 2.2 to 1.4–1.9 and made both the drawdown and the worst single loss larger, because stops were hit at the bottom of sell-offs (often on a weekend gap) just before the rebound. Risk is therefore controlled by the position-size cap (60% of equity) and the 10-day time exit. Do not raise the size beyond what you can hold through a sharp market drop.
Trading involves risk. Past results, including backtests, do not guarantee future results.