Daniel-gheorghe Muresan / Perfil
- Información
|
1 año
experiencia
|
12
productos
|
27
versiones demo
|
|
0
trabajos
|
0
señales
|
0
suscriptores
|
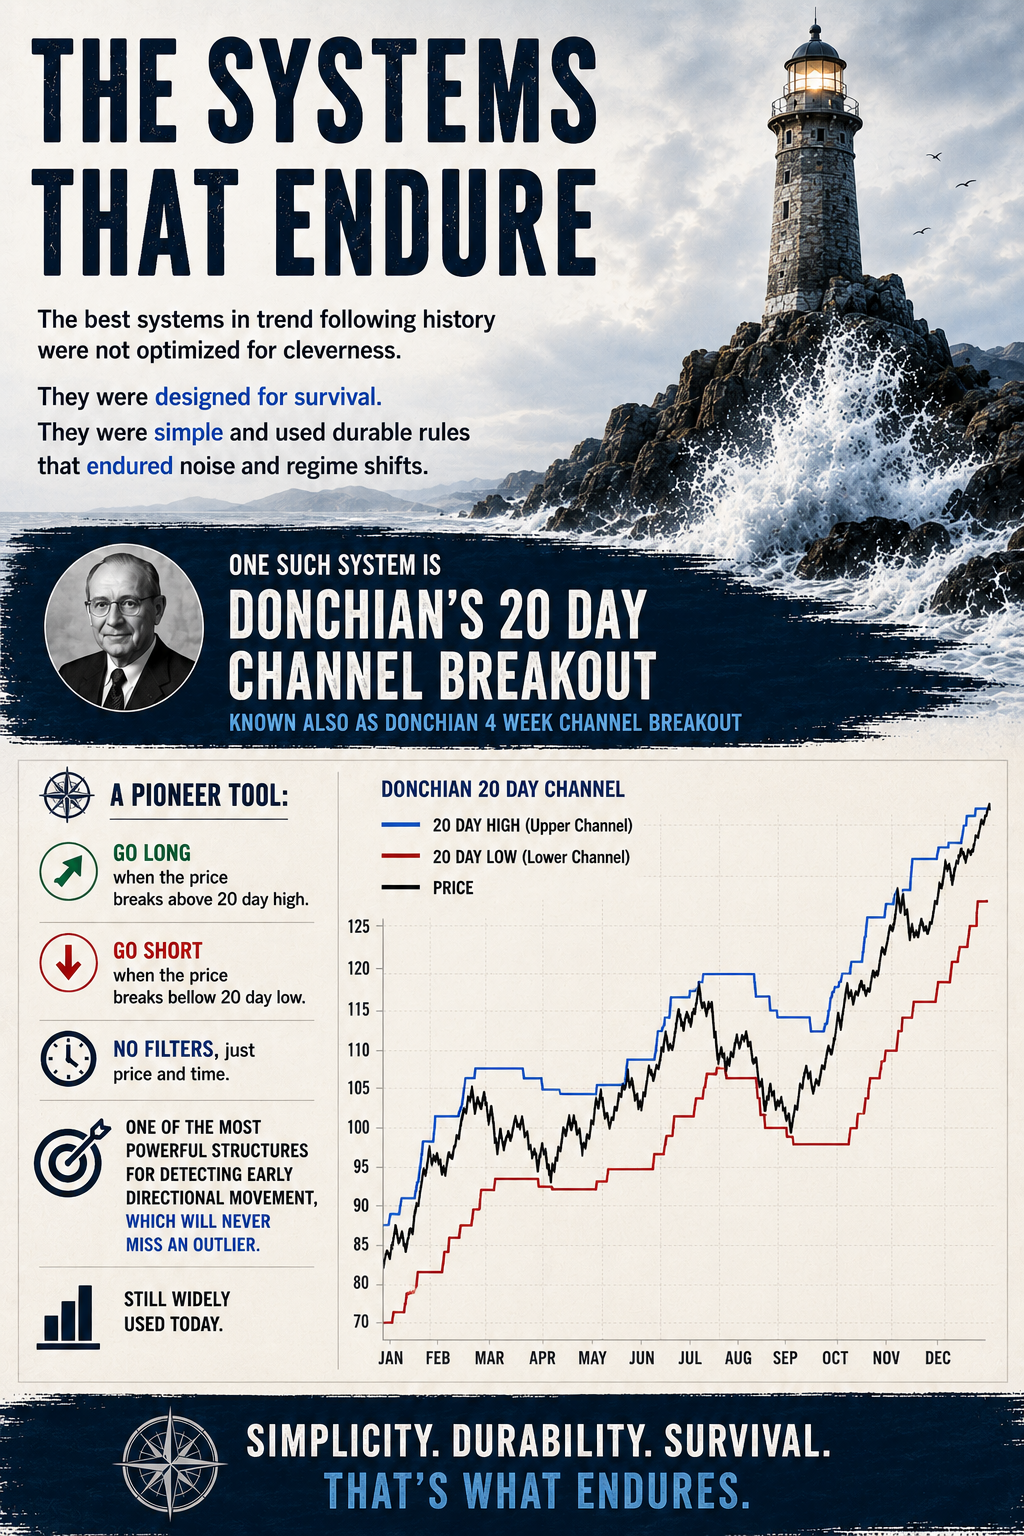
Dado que los mercados han cambiado desde los años 80, utilizo períodos más largos para los breakouts y los trailing stops, sin piramidación y un múltiplo ATR más grande como stop loss.
¡Antes de operar basado en un nuevo método o un nuevo conjunto de parámetros, realizo backtesting, y tú también deberías hacerlo!
Not at all. In fact most of the systems with positive expectancy have a win rate under 50%.
Markets allow a high win rate only because a big loss is hidden somewhere.
I do not want a lot of small profits just to blow my account later.
If the 80 - 90% win rate would work as claimed i would use those systems.
I am a trader in the first place and i know what works and what is bs.
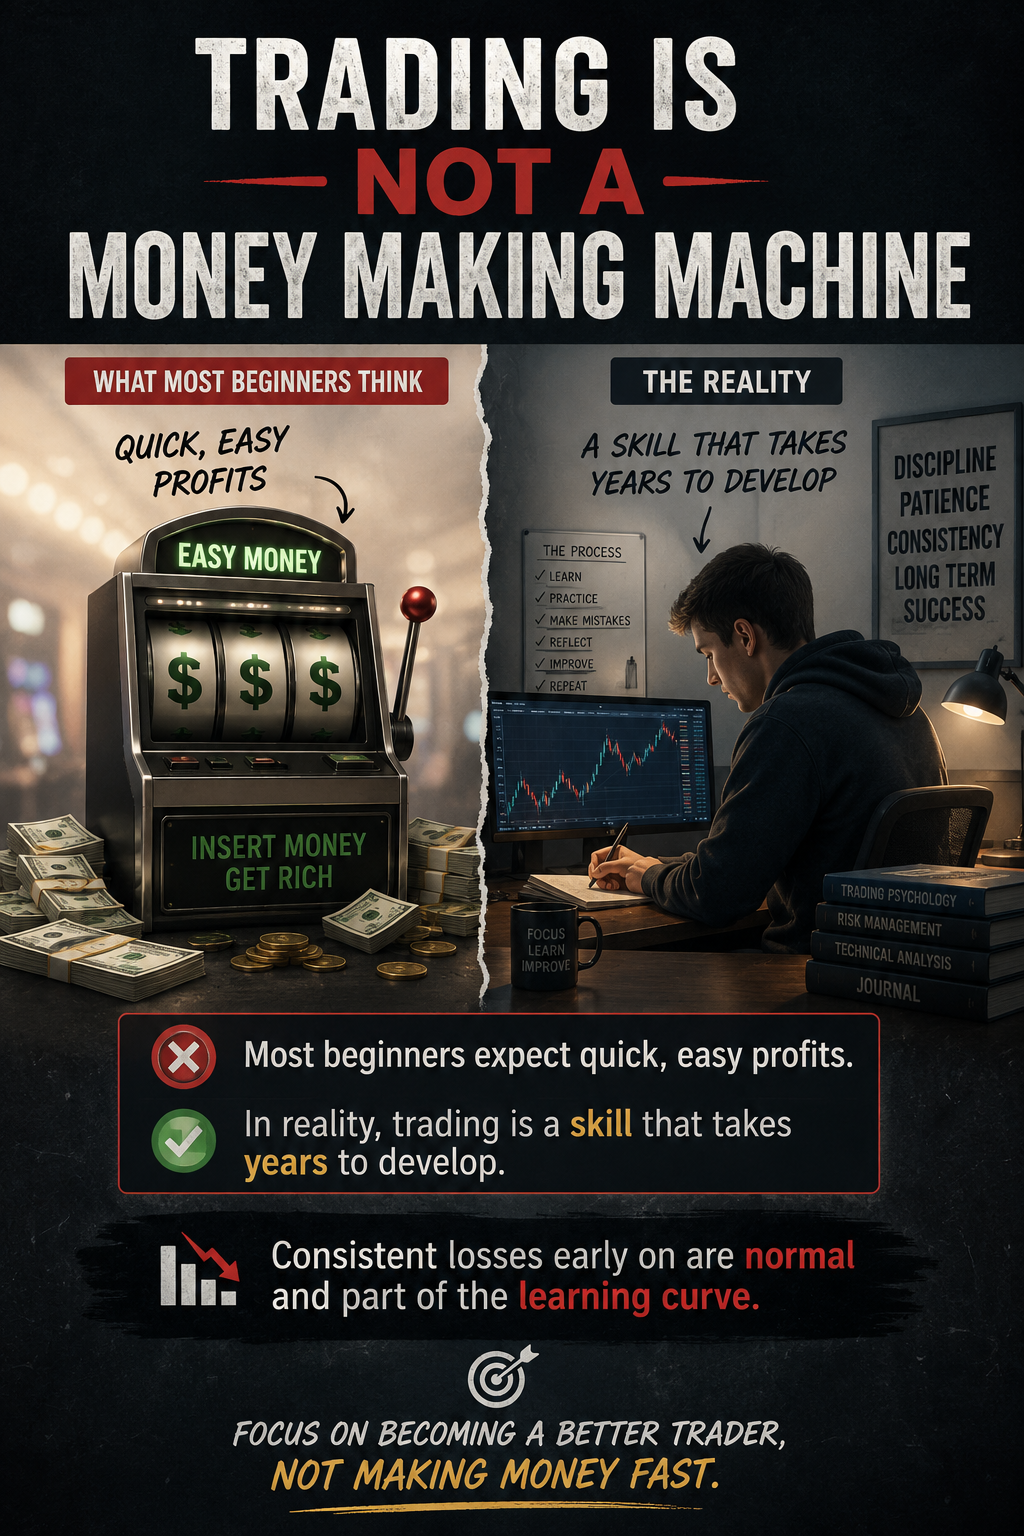
Believe it or not trading is simple but hard to follow with a lot of small losses and drawdowns.
In the end everyone gets what he wants in trading like nice stories with smooth equity curve, high win rate or long term profitability by following 100% a robust system.
Easy but hard this is trading, real trading.
- Cut your losses fast
- Let your winners run
- Follow the price, not your opinion
- Trade many markets and trade them the same way
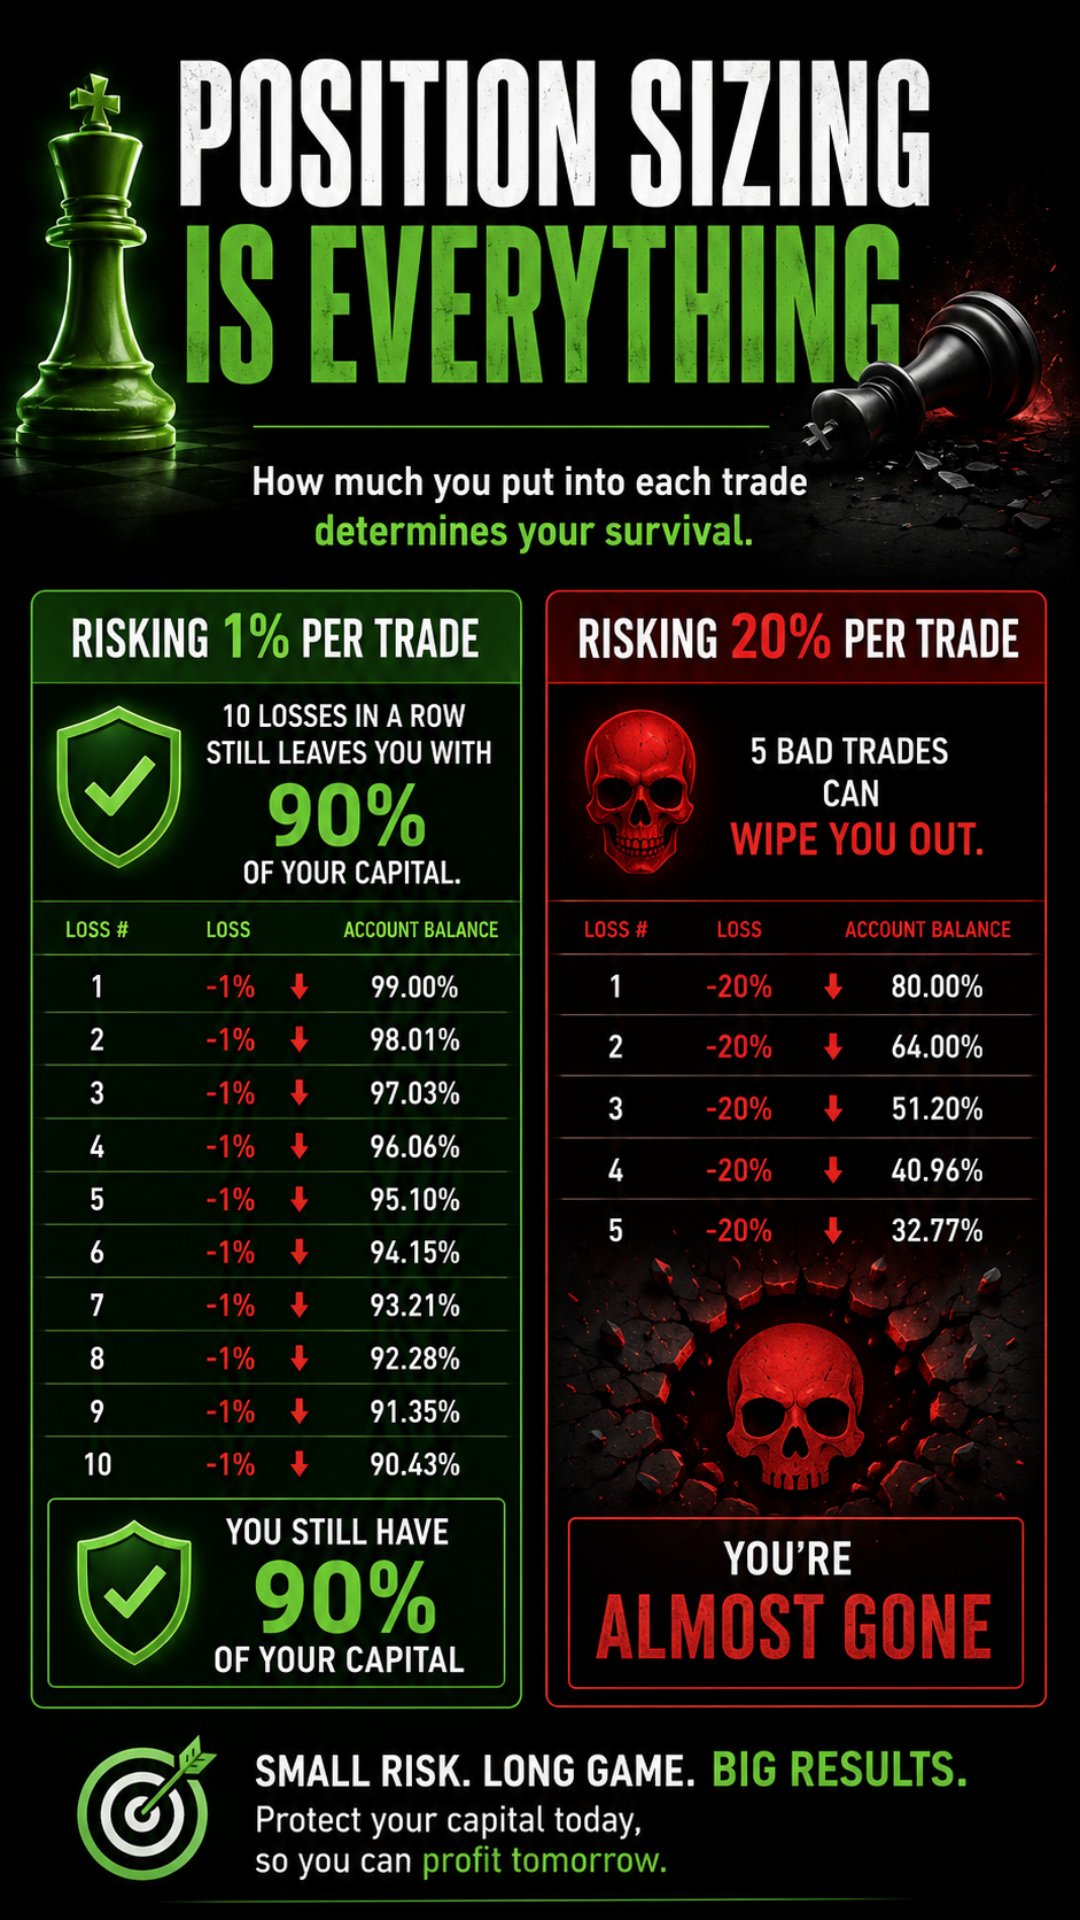
- Use small, equal risk per trade
- Have rules. Follow them. Always
These ideas are simple and passed the test of time.
They work across instruments, across decades and across market regimes.
Not just in simulation, but in real trading.
If you learned something today, hit the like button and share it with someone who trades. It helps more than you think.
Let's say that you trade EUR/USD and you use a 50 pips stop loss. Is this too much or too less? It depends the time frame you trade and the market volatility. You see "volatility" which means that the price does not move in average the same all the time. So if you use a fixed number of pips sometimes you will give too much room for the price to evolve and sometimes too little. In either case you will diminish your returns.
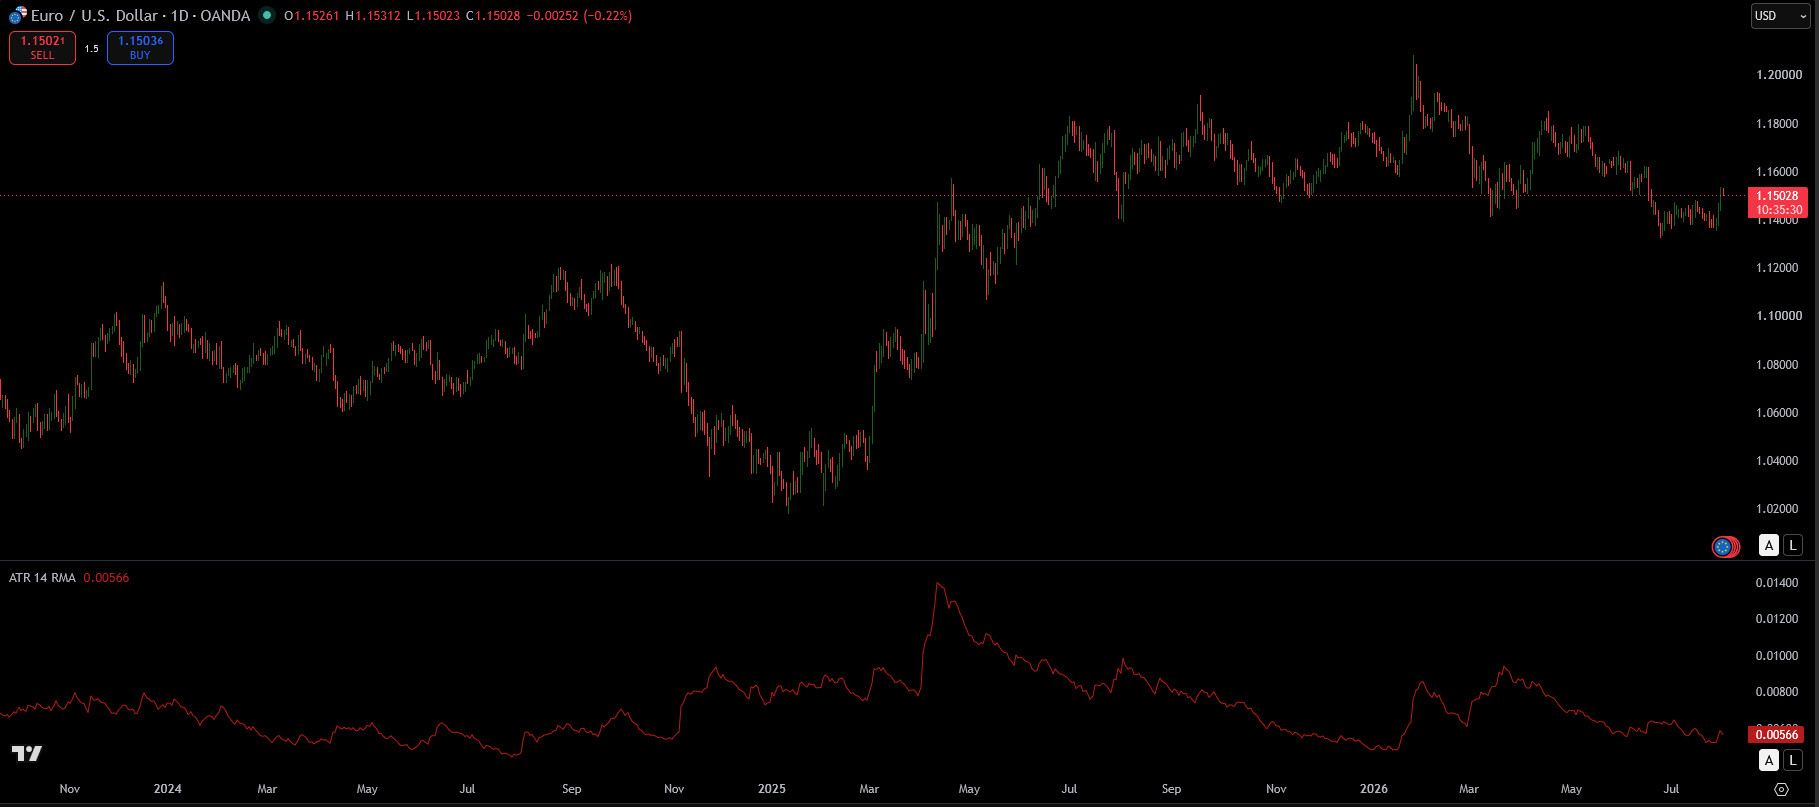
To measure the market volatility we use the average true range(ATR) usually with a 14 or 21 period lookback.
Look at the EUR/USD chart an notice how much can change the market volatility.
Things get even worse if you trade a more volatile pair like GBP/USD, not to mention the really volatile pairs like USD/JPY or GBP/JPY. If 50 pips was good enough on EUR/USD it will not suffice for sure on the other pairs.
What you can do in this situation?
You must incorporate volatility in your stop loss calculation. Maybe the simplest way is to use an ATR multiple as distance from your entry point to place your stop loss. By doing this you will reduce the chances to be whipsawed by normal price movement. Let's say that at the moment you want to enter a trade the atr value is 50 pips. You can place the stop loss at 2 or 3 atr multiples distance from the entry which means 100 or 150 pips away. While there is no magic value for the atr multiple you should use still you must know that a tighter stop loss tends to be whipsawed more often. In the same time if the trade runs in your favor you will get more RR multiples. We talk here about a tradeoff.
What type of stop loss you use in your trading and why? Join the discussion.
https://www.youtube.com/watch?v=jEbEOF0gC3o&t=6s
EA NR7 Opening Range Breakout — Intradía Basado en la metodología de compresión NR7 probada de Toby Crabel Sin Martingala. Sin Grid. Creado por un trader con 8 años de experiencia, no solo un programador. Este asesor experto está inspirado en el trabajo de Toby Crabel publicado en "Day Trading with Short Term Price Patterns and Opening Range Breakout". Qué hace este EA El EA NR7 ORB automatiza uno de los conceptos intradía más probados en el análisis técnico: identificar periodos de compresión
Asesor Experto que combina tres sistemas de trading por ruptura probados en una sola herramienta. El trader selecciona la estrategia activa desde el menú de entrada al adjuntar el EA a un gráfico. Las tres estrategias comparten la misma arquitectura central: gestión de riesgo basada en el saldo, dimensionamiento de posición derivado del ATR, una sola posición a la vez, sin piramidaje, y reenganche automático a posiciones existentes después de un reinicio o recarga. Sin Martingala. Sin Grid