 MetaTrader 5
 Experts
 Indicators
 Scripts
 Libraries
 Storage
Watch how to download trading robots for free
Find us on Telegram!
Join our fan page
Join our fan page
You liked the script? Try it in the MetaTrader 5 terminal
- Published by:
-
Amanda Vitoria De Paula Pereira
 I am a Software Engineer focused on quantitative architecture and high-frequency trade execution, I do not build generic retail scripts, I write clean code designed to survive live broker environments, toxic order flow, and server latency, my infrastructure handles complex math without freezing the
- Views:
- 4253
- Rating:
- Published:
- Updated:
-
 You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration Log inYou agree to website policy and terms of use
If you do not have an account, please register -
 Need a robot or indicator based on this code? Order it on Freelance
Go to Freelance
The Flaw in Retail Volatility Bands
Most retail traders rely on rigid volatility tools like Bollinger Bands or standard Envelopes, these tools are fundamentally flawed because they calculate standard deviation based on linear moving averages. When a market enters a state of extreme systemic shock, these traditional bands blow out completely, providing absolutely zero mathematical boundaries for a reversal.
Institutional quantitative models abandon linear averages entirely. Instead, they use non-parametric smoothing techniques to map the actual underlying structure of the price feed.
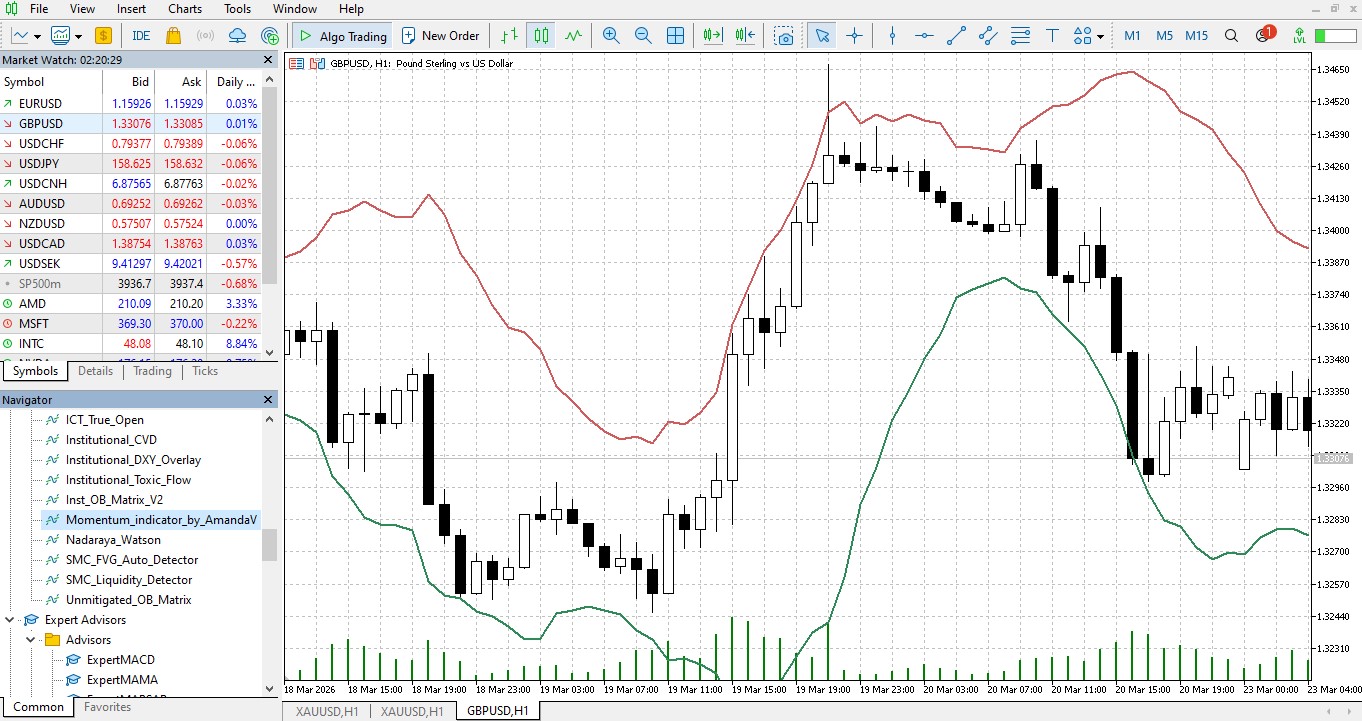
The Institutional Edge: Kernel Regression
The Nadaraya-Watson Kernel Regression indicator brings a core machine learning concept directly into your local trading terminal, by applying a Gaussian kernel to historical price action, the algorithm assigns heavier weights to recent localized price clusters while aggressively filtering out distant structural anomalies.
This creates a highly dynamic and non-linear regression channel that hugs the true market consensus much closer than any standard volatility tool.
Core Quantitative Features
-
Dynamic Mean-Reversion: When the execution price breaches the outer boundaries of this kernel envelope, it signifies a profound mathematical anomaly—a momentary liquidity void where the market has stretched too far from its localized regression mean.
-
Non-Linear Smoothing: Ignores the rigidness of standard deviation, allowing the bands to adapt organically to sudden volume injections.
-
Real-Time Processing: The underlying MQL5 architecture is highly optimized to run these complex distance calculations in real-time, completely eliminating the need for external Python libraries or heavy CPU throttling.
 Multi-Symbol Alert Panel
An indicator to watch highs/lows of all markets simultaneously.
Institutional Gaussian Signal Filter (Zero-Lag ALMA)
A quantitative Gaussian filter designed to replace lagging retail moving averages by applying advanced digital signal processing to eliminate market noise without sacrificing responsiveness.
ExMachina CandleTimer Lite
ExMachina CandleTimer Lite - Free candle countdown timer for MetaTrader 5 with the ExMachina steel palette theme.
 Institutional Kelly-VAPS Risk Engine (Library)
An object-oriented MQL5 library (.mqh) that replaces static retail risk models with institutional Volatility-Adjusted Position Sizing (VAPS) and Kelly Criterion mathematics.