if actual > forecast = good for currency (for AUD in our case)
[AUD - Employment Change] = Change in the number of employed people during the previous month. Job creation is an important leading indicator of consumer spending, which accounts for a majority of overall economic activity.
The unemployment rate Australia remained stable for the third
consecutive month in May, a report from the Australian Bureau Of
Statistics showed Thursday.
The unemployment rate came in at 5.8
percent in May, the same rate as in April and March. Compared to a year
ago, the unemployment rate rose 0.3 percentage points in May.
The
number of unemployed people rose by 3,200 over the month to 717,100 in
May. Out of the total, the number of unemployed looking for full-time
work rose 9,000 to 529,700 and for part-time it decreased 5,900 to
187,400.
The number of employed people fell 4,800 over the month
to 11,564,600. The number of full-time employees rose 22,200 while
number of part-time employees fell 27,000 in May.
However, the participation rate fell to 64.6 in May from 64.7 in April.
In
light of the recent RBNZ interest rate decision and looking at how the
kiwi pairs reacted to the rate hike down under, I would like to focus on
the nzdusd today and to made a case about why the pair is not going to
stop anywhere around these levels and why it should attack the all
important 0.90 area.
Yes, I know we are only in the 0.8650 and recent highs are still
holding but the pattern above on the daily chart is a contracting
triangle that broke higher somewhere in February this year, price made
an impulsive move, or a five waves structure if you want for wave 1 pink
in the chart above and then for the second wave it made a complex
correction, namely a double running flat.
The second flat pattern there kissed the broken now b-d trend line, like a good bye kiss, and then price exploded.
But the info above is only one side of the bullishness on the pair.
The bigger degree triangle you are seeing there has a measured move, the
so called thrust of a triangle and this one points minimum to, well,
0.8872 to come.
The 0.8950 target is given by the fact that the double three running
pattern on the bigger degree charts is always being followed by a third
wave extension, and it means now we are looking for a 3rd wave pink that
should be bigger than 161.8% when compared with the value of wave 1
pink. Minimum.
That gives us 0.8938 for the extension and I will book profits in
that area, up to 0.8950. Why? Well, we want to avoid the classical
behavior markets make around psychological level (check recent failures
eurusd and gbpusd did at almost 1.40 and 1.70).
And all this should happened while price stays above the blue line in
the chart above, as piercing that line will invalidate the whole
pattern.
China's returns on its huge pile of
foreign-exchange reserves are "relatively good" and the nation has been
diversifying its assets in the past few years, officials at the
foreign-exchange regulator said Thursday.
They
also said in an online interview that the buildup of foreign-exchange
reserves, now the world's largest at $3.95 trillion, will gradually ease
as the nation's current account position becomes more balanced.
China
has been diversifying its foreign-exchange reserves in the past few
years and the reserves are "very diversified" in terms of currencies and
types of assets, said Huang Guobo, chief economist of the State
Administration of Foreign Exchange.
Mr.
Huang said assets had been growing steadily and returns on investment
were relatively good in the past few years—including last year. He
didn't elaborate. He said the priority for China in the management of
its foreign-exchange reserves was to maintain adequate liquidity. But he
noted that ample liquidity on investments often means lower returns.
"We
need to make longer term and more diversified investments from our
foreign-exchange reserves while maintaining our fundamental goal of
assuring adequate liquidity," Mr. Huang said without specifying further.
He
also said that China needs to keep its reserves at a "reasonable level"
though he didn't specify how much would be considered reasonable.
The
nation's foreign-exchange reserves reached $3.95 trillion at the end of
March, a big rise from $3.82 trillion at the end of 2013, official data
released in April showed. That reflected a continued trade surplus as
well as steady inflows of capital.
Guan
Tao, head of the international balance-of-payments department at the
State Administration of Foreign Exchange, said in the same online
interview that the yuan would show two-way movement on foreign-exchange
markets instead of a steady appreciation as in previous years.
He said this would contribute to a gradual easing of China's accumulation of foreign-exchange reserves.
The
officials also said that the foreign-exchange regulator would
strengthen its monitoring of cross-border capital flows and prevent
potential risk from huge swings in cross-border capital movements. The
regulator will also continue its efforts to improve the yuan's
exchange-rate mechanism, making it more market-based, they said.
BEIJING—Global investors poured more money into China last year, according to new data, signaling optimism in the prospects of the world's No. 2 economy despite slowing growth. The year-end figures released on Thursday for...
The US Commerce Department reported on Thursday that retail sales in May
rose 0.3 percent, much lower than analysts’ estimate of 0.6 percent
gain and April’s revised 0.5 percent growth.
“The continued gains during the first two months of the second quarter
suggests that consumers are continuing to hold their side of the
bargain, building on the strong momentum at the end of the last
quarter,” Millan Mulraine, a New York-based deputy chief economist at TD
Securities, told Reuters.
Separately, the Labor Department announced that initial applications for
unemployment insurance rose 4,000 to 317,000 in the week through June
7. Nonetheless, recent data shows that the US labor market continues to
improve steadily.
Employers in the country absorbed 217,000 new workers
in May, marking the fourth straight month that the figure has stayed
above 200,000. This has seen all the 8.7 million jobs that were shed in
the financial recession recouped back.
Most analysts expect the economic growth in the second quarter to
range from 3 percent to 4 percent, riding on the back of the resurgent
services and manufacturing sectors. The economy posted a 1 percent
decline in the first quarter owing to the harsh winter weather.
Another data released by the Commerce Department on Wednesday showed
that business inventories grew the most in the six months through April.
The core retail sales, which are adjusted for food, gasoline,
automobiles and building materials, remained unchanged in May. The
figures in April were readjusted to show an increase of 0.2 percent as
opposed to the earlier estimate of a 0.1 percent decline.
Trading the News: U. of Michigan Confidence(based on dailyfx article)
U. of Michigan Confidence Survey to Rebound in June
Expected to Hold Above 80.0 for Seventh Consecutive Month
A rebound in the U. of Michigan Confidence survey may generate a further
decline in the EUR/USD as it raises the fundamental outlook for the
U.S. economy.
What’s Expected:
Why Is This Event Important:
Indeed, a further improvement in household sentiment may spur a greater
dissent within the Federal Open Market Committee (FOMC), and the Fed may
show a greater willingness to normalize monetary policy sooner rather
than later as the central bank hawks see a faster recovery in the
second-half of 2014.
The ongoing pickup in employment paired with the uptick in wage growth
may generate a marked rebound in consumer confidence, and a positive
print may spur a bullish reaction in the USD as it raises the outlook
for growth and inflation.
However, we may see another unexpected downtick in the confidence survey
as household face sticky prices, and a dismal U. of Michigan print may
dampen the appeal of the greenback as it drags on interest rate
expectations.
How To Trade This Event Risk
Bullish USD Trade: U. of Michigan Survey Climbs to 83.0 or Higher
Need to see red, five-minute candle following the release to consider a short trade on EURUSD
If market reaction favors a long dollar trade, sell EURUSD with two separate position
Set stop at the near-by swing high/reasonable distance from entry; look for at least 1:1 risk-to-reward
Move stop to entry on remaining position once initial target is hit; set reasonable limit
Bearish USD Trade: Household Sentiment Continues to Deteriorate
Need green, five-minute candle to favor a long EURUSD trade
Implement same setup as the bullish dollar trade, just in the opposite direction
Potential Price Targets For The Release
EUR/USD Daily
Bullish Outside Day (Harami) in Focus as EUR/USD Preserves Monthly Low (1.3501)
Interim Resistance: 1.3650 (78.6% expansion) to 1.3670 (61.8% retracement)
Interim Support: 1.3490 (50.0% retracement to 1.3500 Pivot
Impact that the U. of Michigan Confidence has had on EUR/USD during the last release
Period
Data Released
Estimate
Actual
Pips Change
(1 Hour post event )
Pips Change
(End of Day post event)
MAY P
2014
05/16/2014 13:55 GMT
84.5
81.8
-8
-18
May 2014 U. of Michigan Confidence Survey
USDJPY M5 : 15 pips price movement by USD - UoM Consumer Sentiment news event
The U. of Michigan Confidence survey unexpectedly weakened in May, with
the index slipping to 81.8 from 84.1 the month prior. Despite the
weaker-than-expected print, the EUR/USD struggled to hold above the
1.3700 handle, with the pair closing the day at 1.3692.
After spending a couple of weeks at the end of May trading near and finding support at 0.9220, the Australian dollar
has enjoyed a solid surge over over the last couple of weeks. It has
not only moved through the key 0.93 level but moved to a resistance
level around 0.9425 and in doing so achieved a two month high. The
0.9220 level has repeatedly reinforced its significance as it is again
likely to support price should the Australia dollar retreat. Only a
month ago the Australian dollar was placing pressure on the resistance
level at 0.94 when it was able to poke through for a short period and
reach a four week high in the process, however in the last 24 hours it
has surpassed those levels and achieved the two week high.
Throughout April and into May the Australian dollar drifted lower
from resistance just below 0.95 after reaching a six month high in that
area and down to the recent key level at 0.93 before falling lower.
During this period the 0.93 level has become very significant as it has
provided stiff resistance for some time. The Australian dollar appeared
to be well settled around 0.93 which has illustrated the strong
resurgence it has experienced throughout this year. For the best part of
February and March, the Australian dollar did very little other than
continue to trade around the 0.90 level, although at the beginning of
March it crept a little lower down to a three week low below 0.89.
Towards the end of March however, the Australian dollar surged higher
strongly moving to the resistance level at 0.93 before consolidating for
a week or so.
For several months either side of the New Year, the Australian dollar
established and traded within a narrow range roughly between 0.88 and
the previous resistance level at 0.90. Back in January, the Australian
dollar was able to rally higher pushing through the resistance at 0.90
to a one month high near 0.91, however it quickly returned to more
familiar territory below the resistance levels at 0.90 and 0.88. After
showing some resilience in early December moving to a one week high
above 0.9150, the AUD/USD spent the next two weeks turning around
sharply and falling heavily down to a then three month low close to
0.88.
Australia’s unemployment rate was steady at 5.8 per cent in May,
official figures show. The total number of people with jobs fell 4,800
to 11.565 million in May, according to seasonally adjusted figures from
the Australian Bureau of Statistics on Thursday. The unemployment rate
was expected to reach 5.9 per cent in May, with 10,000 jobs added to the
economy, according to an AAP survey of 13 economists. Full-time
employment rose 22,200 to 8.068 million in May and part-time employment
was down 27,000 to 3.496 million. The participation rate — those who
have a job, are looking for work or are ready to start work — fell to
64.6 per cent, from 64.7 per cent in April.
AUD/USD Technical
S3
S2
S1
R1
R2
R3
0.9220
0.9100
---
0.9380
0.9400
---
During the early hours of the Asian trading
session on Friday, the AUD/USD is remaining steady around the recent
resistance level around 0.9425 after surging higher from around 0.9370
over the last 24 hours. The Australian dollar was in a free-fall for a
lot of last year falling close to 20 cents and it has done very well to
recover slightly to well above 0.90 again. Current range: trading right
around 0.9425.
The dollar and the euro were on the back foot in the past week. The
focus is now on the Fed decision and the UK inflation data. In
addition, the Philly Fed Manufacturing Index and inflation figures will
be of interest. Here are the main events on our FX calendar. Here is an
outlook on the market-movers for the coming week. A jump in US job
openings underpinned the US dollar. While this figure is lagging, it
closely watched by the Federal Reserve. However, other figures from the
US, such as retail sales, were mediocre. The UK enjoyed encouraging
employment figures that lift the prospects of an early rate hike, and
Carney indeed explicitly said that a rate hike make come sooner than
later, sending the pound jumping up.. In Europe, the lower bond yields
and the implementation of the negative deposit rate weighed on the
common currency. Another currency that stood out is the kiwi that leaped
up: the RBNZ hiked the rate and did not signal a pause.
UK inflation data: Tuesday,
8:30. Annual inflation in the UK edged up to 1.8% in April, rising for
the first time in almost a year, following 1.6% in the previous month.
The main cause for this rise was higher travel and energy prices.
Analysts expected a smaller climb of 0.1%. However rising inflation
ignites new fears that the standard of living will decline due to
falling wages. CPI is expected to slide to an annual level of 1.7%. The
RPI is predicted to remain at 2.5% and Core CPI to slide to 1.7%.
German ZEW Economic Sentiment:
Tuesday, 9:00. German economic sentiment plunged in May by 10.1 points,
to 33.1, hitting the lowest level since January 2013. The Ukraine
crisis was the probable cause for this fall starting effect economic
activity, especially in the eastern part of the country. Economists
expected a 2.2 points fall to 41.3 in May. A rise to 35.2 points is
expected now. The all-European figure is also expected to advance to
59.6 points.
US Building Permits: Tuesday,
12:30. U.S. building permits soared in April to their highest level in
nearly six years, reaching 1.08 million-unit pace. The sharp rise
offered hope that the recent sluggishness in the housing market may be
over. The 90,000 rise surprised analysts expecting a 1.01 million-unit
pace. A similar level of 1.07 million is estimated now. Housing starts
carry expectations of dropping from 1.07 to 1.04 million.
US inflation data:
Tuesday, 12:30. U.S. Consumer Price Index increased 0.3% in April
after posting a 0.2% gain in March, as food prices edged up for a
fourth consecutive month and the cost of gasoline climbed. The reading
was consistent with analysts’ forecast. In the 12 months through April,
CPI gained 2.0% after a 1.5% rise in March, the biggest increase since
July last year. Meanwhile, core inflation, excluding food and energy
prices, rose 0.2% above predictions of a 0.1% rise and following a 0.2%
rate in the previous month. US inflation remains in Goldilocks
territory. Both CPI and Core CPI are expected to rise 0.2% m/m.
UK MPC Meeting Minutes:
Wednesday, 8:30. After Carney lifted the pound with his rate hike
comment, it will be very interesting to see if one or more members
already voted for a rate hike in June’s no-change decision. Up to now,
Carney enjoyed unanimous support behind his policy, and that is what is
expected now. A non-unanimous vote could push the pound even higher.
US rate decision:
Wednesday, 18:00, press conference at 18:30. The Fed is expected to
taper bond buys for the 5th time, to $35 billion / month. Recent data
from the US has been positive and showed growth in jobs as well as in
other sectors after the terrible first quarter. Markets will likely
focus on the fresh economic projections, especially those concerning
the potential date of a rate hike. The previous decision was not
accompanied by a press conference, and it passed quite quietly. This
was not the case in March, when Yellen said that a rate hike could come
within 6 months of the end of QE and stirred markets. Was it a slip in
her first appearance or did she sow the initial seed for a rate hike in
early 2015? Every word she says now will be scrutinized and could
cause a significant market stir. Given the recent improvement, we can
expect a more hawkish approach. If the hints are subtle, a full
response to the FOMC statement and the press conference can only be
expected in the following sessions. Contrary to April’s decision, this
one could have a long lasting impact on markets.
NZ GDP: Wednesday,
22:45. Economic growth in New Zealand continued to grow in the last
quarter of 2013, rising 0.9% from a 1.2% expansion in the third
quarter. Analysts expected a higher rise of 1.0% in the 4th
quarter. Manufacturing and wholesale trade were the main contributors
to the rise in output. On an annualized rate, GDP expanded 3.1% in the
December quarter, in line with forecasts. A growth rate of 1.2% is
expected now.
Switzerland rate decision:
Thursday, 7:30. The Swiss National Bank kept rates unchanged at 0.25%
but was more optimistic on future growth prospects. The bank reiterated
its commitment to defend the 1.20 per euro limit with unlimited
interventions and stood ready to take further measures if necessary. The
SNB said economic activity in Switzerland should improve from the
first quarter of 2014 confirming a 2.0% growth this year.
US Unemployment Claims: Thursday,
12:30. Recent trends in jobless claims have been positive, with a
gradual convergence towards the 300K level. While the drops have never
been steady, the US job market seems to be going in the right
direction. A figure of under 300K will certainly be dollar positive,
but after the recent rise to 317K, a similar value of 316K is
predicted.
US Philly Fed Manufacturing Index:
Thursday, 14:00. US manufacturing barometer in the Philadelphia area
declined less than expected in April, reaching 15.4 after rising to
16.6 points in March. The Philly Fed’s general conditions index
reaching 15.4 in May was nearly as strong as April’s 16.6. This report,
together with Empire State, reaffirms the strength of the US
manufacturing sector. A small slide to 14.3 points is on the cards.
Global threats are nothing new to
markets, but the impact they can have is incredible. Commodity prices
can jump quickly, and volatility can drive markets to the point of
collapse; as we saw in the global financial crisis. These days, though,
threats seem to be few and far between when it comes to markets.
However, one of the largest threats to
the markets has appeared this year, in the form of the ISIS in Iraq.
Normally I try and avoid threats to markets and the impact they may
have - or just include a sentence of two – but in this case I feel it
is actually a serious threat to oil markets.
Currently Iraq is going through the
process of 'turning on the taps', or basically getting its oil
production back into full swing, after a deadly war, followed by civil
unrest. So far so good, and things are starting to happen in Iraq,
which has the world’s fifth-largest proven oil reserves.
But the wheels are starting to come
unstuck in Iraq and oil production may be severely affected as a result.
The ISIS an offshoot of Al-Qaeda and is looking very deadly; they are
not led by an ideologist per say, but instead a seasoned battle
commander. Hence why they so far have been extremely successful in their
ability to move across Iraq and conquer various cities.
In addition to having a heavily armed
force, they are not just a terrorist organisation. They act like a
state, setting up courts and schools and providing services for the
regions that they control. This is not just a side bent on terror,
this is an organisation hell bent on conquering the northern part of
Iraq and taking vengeance on the current government.
Chances of success when it comes to
conquering Baghdad may seem slim, but many have failed to realize the
capabilities that they have. After the capitulation in Mosgul, they
acquired ammunition and weapons from the escaping army. They are as a
result of this now more heavily armed than ever; and in addition to
this to they have captured the equivalent ofUS$400 million from the
central bank in Mosgul to give them the capital of a small country
now.
An escalation in Iraq now seems
inevitable, and regional powers are about to get sucked in whether
they like it or not. The Kurds are holding their own province in the
north, but many see this as a short term move. Long term we could see
an Iraq divided by religious grounds, with a north and south much like
in the case of Sudan.
This massive build-up of tension will
make Ukraine seem like a small problem as Iraq holds a massive oil
wealth and sits in one of the world’s most volatile regions. It’s easy
to just look at Iraq, but you need to take a look at the bigger
picture, and that includes its neighbours like Saudi Arabia, Kuwait,
Iran, Syria and Turkey. Many of these neighbours have large reserves
of oil and gas and violence can easily spill over borders which are
separated by deserts and not by large geographical features.
I had honestly been expecting a small dip down to the trend line,
but the recent escalation of tensions in Iraq will have a major impact.
American involvement in Iraq again will also play a big role in oil
markets getting even more uneasy, as it’s a sign that things really have
hit rock bottom again in Iraq as it cannot control the current
insurgency.
The last candle was very aggressive in terms of climbing higher.
And with the escalation likely to hit critical points in the next 24
hours, expect to see major climbs in the chart with a target of 110, as
that is the heaviest point of resistance.
With the current US stance to not act, any relief may come too late
to help any assault on Baghdad, what is clear though is that the oil
markets have not priced themselves into a civil war in Iraq, especially
one that will destabilise all oil production in the volatile region and
have an effect on global prices. ISIS is hell bent on exacting revenge
on the current Iraqi government and an attack for them would be coming
full circle in their campaign - Oil prices will be quick to react to
such aggression!
With a full moon and a Friday the 13th capping a week of election
surprises at home — like Eric Cantor’s shocking primary loss in
Virginia’s 7th Congressional district — and unrest in Iraq, investors
would have been excused for acting skittish in Friday trading. But
instead, they sent the U.S. equity markets for a daily gain on Friday,
leading all three major indices finishing the day in positive territory.
Unfortunately, the late-in-week gains weren’t enough to offset losses
from earlier in the week, with the Dow, Nasdaq and S&P 500 ending
the week in the red.
The Dow closed Friday up 41.55 points, or 0.25%, as the Nasdaq finished
up 13 points, or 0.3%, and the S&P closed 6 points, or 0.3%, higher
for the day. All three indices traded in positive territory for the
majority of the day on Friday, a bit of a surprise given the unrest in
Iraq, which has seen Sunni militants seize broad swaths of Iraqi
territory — territory that includes much of the country’s oil fields.
This, in turn, has sent oil prices to their highest levels this year:
Brent crude futures hit $114 a barrel before settling at $113.50 and oil
futures went as high as $107 a barrel before eventually settling around
$106. Compare this to their Monday prices: Brent crude opened the week
closer to $108 a barrel and oil started Monday trading around $103.
While these price jumps would have caused market jitters and consumer
panic 10 years ago, John Canally, an investment strategist with LPL
Financial, said that progress the U.S. has made with energy independence
means that oil at $107 a barrel won’t threaten the country’s economic
recovery — and that this, in turn, explains why stocks were in the green
for much of Friday trading.
“These days, even versus 2005, we’re using less gasoline. We’re doing a
better job in conserving it that way,” Canally said in a phone
interview. “We’re still well below the level where it begins to pinch
growth,” he added, noting that investors can start to worry if oil
prices start pushing $130, $140 and certainly $150 a barrel. Also, he
added, oil prices normally rise in the summer — peaking around the
Fourth of July, typically — so a small part of oil’s increase can be
attributed to that.
“You have to remember we just went through geopolitical unrest in
Ukraine – and that sort of fizzled. Right on the heels of that, we have
the issue with Iraq, and the market gets used to these things,” Canally
said, explaining the market’s relatively muted response to the popping
oil prices. They really reacted on Thursday, he noted, but Friday’s
action was, in his view, typical Friday trading behavior. “And quite
frankly a lot of people are sitting in front of their computers watching
the World Cup,” he laughed.
Canally also noted that the relatively positive performance for equities
on a day with a full moon and superstitious date — Friday the 13th —
might be a surprise to some, but is consistent with prior Friday the
13th’s.
“In general, Friday the 13th has been up. There have been 186 Friday the
13ths since 1901, and 110 finished up, the rest down,” Canally said.
“Friday the 13th’s are better than the average day. And if you look at
Friday the 13th in June, 12 of 15 since 1901 have been up. In that
regard, the fact that we’re having an up day today makes sense.”
While stocks finished in the green on Friday, the gains were not enough
to offset losses from earlier in the week — some of which market
insiders attributed to Cantor’s loss on Tuesday, some of which can be
attributed to Iraqi tensions that escalated on Thursday. The S&P
finished the week down 0.74%, the Dow closed the week with an 0.9% loss
and the Nasdaq closed the week down 0.33%. For the Dow and S&P, the
losses marked the first weekly losses in four weeks for the indices.
On a stock-by-stock level, two of the market’s biggest gainers were
OpenTable, which earlier on Friday announced that it will be acquired by
Priceline for $2.6 billion, and retailer Express, which sparked
investor interest after a private equity firm, Sycamore Partners,
disclosed a near-10% stake in the company. OpenTable finished the day
over $104 per share, a 48% surge, and Express finished over $16 per
share, a 21% gain.
Pound Rallies as Carney Signals Possible Rate Hike in BoE’s Future
Pre-Fed Price Action Favors GBP/USD Breakout, EUR/USD Outside Bar
The GBP/USD rallied to a fresh monthly high of 1.6990 as Bank of
England (BoE) Governor Mark Carney showed a greater willingness to
normalize monetary sooner rather than later, and the pound-dollar may
continue to carve a series of higher-highs & higher-lows during the
summer months amid the ongoing shift in the policy outlook.
Nevertheless, the data prints due out next week may generate a minor
setback in the British Pound rally as the U.K. Consumer Price Index
(CPI) is expected to narrow to an annualized 1.7% in May, but the BoE
policy statement may heighten the bullish sentiment surrounding the
sterling should the central bank adopt a more hawkish tone for monetary
policy.
Indeed, the BoE Minutes may reveal a growing dissent within the
Monetary Policy Committee (MPC) as a greater number of central bank
officials turn increasingly upbeat on the U.K. economy, and the policy
statement may spur a more meaningful pickup in interest rate
expectations should the committee lay out a more detailed exit
strategy. With that said, a split BoE decision may serve as the
fundamental catalyst to trigger another near-term rally in the GBP/USD,
and we will maintain a bullish outlook for the pair as the Federal
Reserve remains reluctant to move away from its zero-interest rate
policy (ZIRP).
As a result, the GBP/USD looks poised for a higher-high as it carves
higher-lows in June, and we will look for opportunities to ‘buy dips’
in the pound-dollar as the Relative Strength Index (RSI) breaks out of
the bearish momentum carried over from the previous month.
if actual > forecast = good for currency (for AUD in our case)
[AUD - Employment Change] = Change in the number of employed people during the previous month. Job creation is an important leading indicator of consumer spending, which accounts for a majority of overall economic activity.
==========
Australia Unemployment Rate Stable In May
The unemployment rate Australia remained stable for the third consecutive month in May, a report from the Australian Bureau Of Statistics showed Thursday.
The unemployment rate came in at 5.8 percent in May, the same rate as in April and March. Compared to a year ago, the unemployment rate rose 0.3 percentage points in May.
The number of unemployed people rose by 3,200 over the month to 717,100 in May. Out of the total, the number of unemployed looking for full-time work rose 9,000 to 529,700 and for part-time it decreased 5,900 to 187,400.
The number of employed people fell 4,800 over the month to 11,564,600. The number of full-time employees rose 22,200 while number of part-time employees fell 27,000 in May.
However, the participation rate fell to 64.6 in May from 64.7 in April.
Top Trade Idea For June 12th, 2014 – NZDUSD
In light of the recent RBNZ interest rate decision and looking at how the kiwi pairs reacted to the rate hike down under, I would like to focus on the nzdusd today and to made a case about why the pair is not going to stop anywhere around these levels and why it should attack the all important 0.90 area.
Yes, I know we are only in the 0.8650 and recent highs are still holding but the pattern above on the daily chart is a contracting triangle that broke higher somewhere in February this year, price made an impulsive move, or a five waves structure if you want for wave 1 pink in the chart above and then for the second wave it made a complex correction, namely a double running flat.
The second flat pattern there kissed the broken now b-d trend line, like a good bye kiss, and then price exploded.
But the info above is only one side of the bullishness on the pair. The bigger degree triangle you are seeing there has a measured move, the so called thrust of a triangle and this one points minimum to, well, 0.8872 to come.
The 0.8950 target is given by the fact that the double three running pattern on the bigger degree charts is always being followed by a third wave extension, and it means now we are looking for a 3rd wave pink that should be bigger than 161.8% when compared with the value of wave 1 pink. Minimum.
That gives us 0.8938 for the extension and I will book profits in that area, up to 0.8950. Why? Well, we want to avoid the classical behavior markets make around psychological level (check recent failures eurusd and gbpusd did at almost 1.40 and 1.70).
And all this should happened while price stays above the blue line in the chart above, as piercing that line will invalidate the whole pattern.
China's Forex Reserve Returns 'Relatively Good'
China's returns on its huge pile of foreign-exchange reserves are "relatively good" and the nation has been diversifying its assets in the past few years, officials at the foreign-exchange regulator said Thursday.
They also said in an online interview that the buildup of foreign-exchange reserves, now the world's largest at $3.95 trillion, will gradually ease as the nation's current account position becomes more balanced.
China has been diversifying its foreign-exchange reserves in the past few years and the reserves are "very diversified" in terms of currencies and types of assets, said Huang Guobo, chief economist of the State Administration of Foreign Exchange.
Mr. Huang said assets had been growing steadily and returns on investment were relatively good in the past few years—including last year. He didn't elaborate. He said the priority for China in the management of its foreign-exchange reserves was to maintain adequate liquidity. But he noted that ample liquidity on investments often means lower returns.
"We need to make longer term and more diversified investments from our foreign-exchange reserves while maintaining our fundamental goal of assuring adequate liquidity," Mr. Huang said without specifying further.
He also said that China needs to keep its reserves at a "reasonable level" though he didn't specify how much would be considered reasonable.
The nation's foreign-exchange reserves reached $3.95 trillion at the end of March, a big rise from $3.82 trillion at the end of 2013, official data released in April showed. That reflected a continued trade surplus as well as steady inflows of capital.
A rise in capital inflows and foreign direct investment last year has forced China's central bank to buy foreign currency, partly in a move to stop the yuan from appreciating.
Guan Tao, head of the international balance-of-payments department at the State Administration of Foreign Exchange, said in the same online interview that the yuan would show two-way movement on foreign-exchange markets instead of a steady appreciation as in previous years.
He said this would contribute to a gradual easing of China's accumulation of foreign-exchange reserves.
The officials also said that the foreign-exchange regulator would strengthen its monitoring of cross-border capital flows and prevent potential risk from huge swings in cross-border capital movements. The regulator will also continue its efforts to improve the yuan's exchange-rate mechanism, making it more market-based, they said.
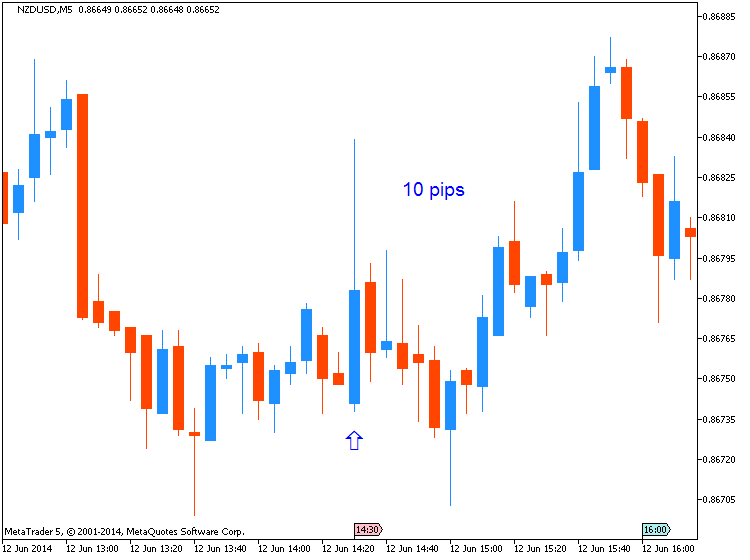
2014-06-12 12:30 GMT (or 14:30 MQ MT5 time) | [USD - Retail Sales]
---
U.S. Retail Sales in May Grow Slower than Estimated
The US Commerce Department reported on Thursday that retail sales in May rose 0.3 percent, much lower than analysts’ estimate of 0.6 percent gain and April’s revised 0.5 percent growth.
“The continued gains during the first two months of the second quarter suggests that consumers are continuing to hold their side of the bargain, building on the strong momentum at the end of the last quarter,” Millan Mulraine, a New York-based deputy chief economist at TD Securities, told Reuters.
Separately, the Labor Department announced that initial applications for unemployment insurance rose 4,000 to 317,000 in the week through June 7. Nonetheless, recent data shows that the US labor market continues to improve steadily.
Employers in the country absorbed 217,000 new workers in May, marking the fourth straight month that the figure has stayed above 200,000. This has seen all the 8.7 million jobs that were shed in the financial recession recouped back.
Most analysts expect the economic growth in the second quarter to range from 3 percent to 4 percent, riding on the back of the resurgent services and manufacturing sectors. The economy posted a 1 percent decline in the first quarter owing to the harsh winter weather.
Another data released by the Commerce Department on Wednesday showed that business inventories grew the most in the six months through April.
The core retail sales, which are adjusted for food, gasoline, automobiles and building materials, remained unchanged in May. The figures in April were readjusted to show an increase of 0.2 percent as opposed to the earlier estimate of a 0.1 percent decline.
Trading the News: U. of Michigan Confidence (based on dailyfx article)
A rebound in the U. of Michigan Confidence survey may generate a further decline in the EUR/USD as it raises the fundamental outlook for the U.S. economy.
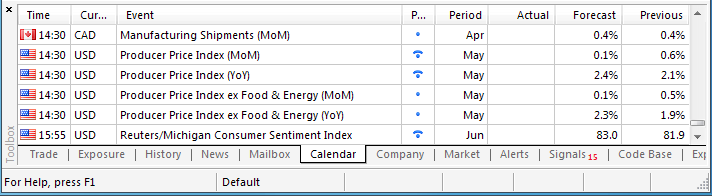
What’s Expected:
Why Is This Event Important:
Indeed, a further improvement in household sentiment may spur a greater dissent within the Federal Open Market Committee (FOMC), and the Fed may show a greater willingness to normalize monetary policy sooner rather than later as the central bank hawks see a faster recovery in the second-half of 2014.
The ongoing pickup in employment paired with the uptick in wage growth may generate a marked rebound in consumer confidence, and a positive print may spur a bullish reaction in the USD as it raises the outlook for growth and inflation.
However, we may see another unexpected downtick in the confidence survey as household face sticky prices, and a dismal U. of Michigan print may dampen the appeal of the greenback as it drags on interest rate expectations.
How To Trade This Event Risk
Bullish USD Trade: U. of Michigan Survey Climbs to 83.0 or Higher
- Need to see red, five-minute candle following the release to consider a short trade on EURUSD
- If market reaction favors a long dollar trade, sell EURUSD with two separate position
- Set stop at the near-by swing high/reasonable distance from entry; look for at least 1:1 risk-to-reward
- Move stop to entry on remaining position once initial target is hit; set reasonable limit
Bearish USD Trade: Household Sentiment Continues to Deteriorate- Need green, five-minute candle to favor a long EURUSD trade
- Implement same setup as the bullish dollar trade, just in the opposite direction
Potential Price Targets For The ReleaseEUR/USD Daily
Impact that the U. of Michigan Confidence has had on EUR/USD during the last release
(1 Hour post event )
(End of Day post event)
2014
May 2014 U. of Michigan Confidence Survey
USDJPY M5 : 15 pips price movement by USD - UoM Consumer Sentiment news event
The U. of Michigan Confidence survey unexpectedly weakened in May, with the index slipping to 81.8 from 84.1 the month prior. Despite the weaker-than-expected print, the EUR/USD struggled to hold above the 1.3700 handle, with the pair closing the day at 1.3692.
AUD/USD: Moves to Two Month High Around 0.9425
After spending a couple of weeks at the end of May trading near and finding support at 0.9220, the Australian dollar has enjoyed a solid surge over over the last couple of weeks. It has not only moved through the key 0.93 level but moved to a resistance level around 0.9425 and in doing so achieved a two month high. The 0.9220 level has repeatedly reinforced its significance as it is again likely to support price should the Australia dollar retreat. Only a month ago the Australian dollar was placing pressure on the resistance level at 0.94 when it was able to poke through for a short period and reach a four week high in the process, however in the last 24 hours it has surpassed those levels and achieved the two week high.
Throughout April and into May the Australian dollar drifted lower from resistance just below 0.95 after reaching a six month high in that area and down to the recent key level at 0.93 before falling lower. During this period the 0.93 level has become very significant as it has provided stiff resistance for some time. The Australian dollar appeared to be well settled around 0.93 which has illustrated the strong resurgence it has experienced throughout this year. For the best part of February and March, the Australian dollar did very little other than continue to trade around the 0.90 level, although at the beginning of March it crept a little lower down to a three week low below 0.89. Towards the end of March however, the Australian dollar surged higher strongly moving to the resistance level at 0.93 before consolidating for a week or so.
For several months either side of the New Year, the Australian dollar established and traded within a narrow range roughly between 0.88 and the previous resistance level at 0.90. Back in January, the Australian dollar was able to rally higher pushing through the resistance at 0.90 to a one month high near 0.91, however it quickly returned to more familiar territory below the resistance levels at 0.90 and 0.88. After showing some resilience in early December moving to a one week high above 0.9150, the AUD/USD spent the next two weeks turning around sharply and falling heavily down to a then three month low close to 0.88.
Australia’s unemployment rate was steady at 5.8 per cent in May, official figures show. The total number of people with jobs fell 4,800 to 11.565 million in May, according to seasonally adjusted figures from the Australian Bureau of Statistics on Thursday. The unemployment rate was expected to reach 5.9 per cent in May, with 10,000 jobs added to the economy, according to an AAP survey of 13 economists. Full-time employment rose 22,200 to 8.068 million in May and part-time employment was down 27,000 to 3.496 million. The participation rate — those who have a job, are looking for work or are ready to start work — fell to 64.6 per cent, from 64.7 per cent in April.
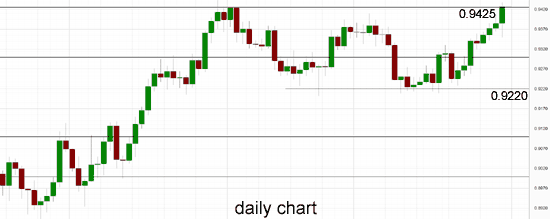
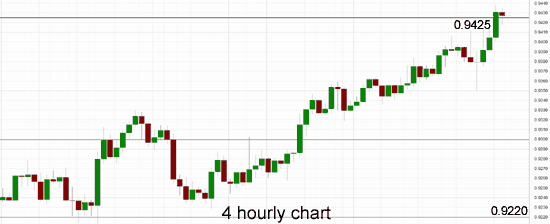
AUD/USD TechnicalDuring the early hours of the Asian trading session on Friday, the AUD/USD is remaining steady around the recent resistance level around 0.9425 after surging higher from around 0.9370 over the last 24 hours. The Australian dollar was in a free-fall for a lot of last year falling close to 20 cents and it has done very well to recover slightly to well above 0.90 again. Current range: trading right around 0.9425.
The dollar and the euro were on the back foot in the past week. The focus is now on the Fed decision and the UK inflation data. In addition, the Philly Fed Manufacturing Index and inflation figures will be of interest. Here are the main events on our FX calendar. Here is an outlook on the market-movers for the coming week. A jump in US job openings underpinned the US dollar. While this figure is lagging, it closely watched by the Federal Reserve. However, other figures from the US, such as retail sales, were mediocre. The UK enjoyed encouraging employment figures that lift the prospects of an early rate hike, and Carney indeed explicitly said that a rate hike make come sooner than later, sending the pound jumping up.. In Europe, the lower bond yields and the implementation of the negative deposit rate weighed on the common currency. Another currency that stood out is the kiwi that leaped up: the RBNZ hiked the rate and did not signal a pause.
Threats, Markets, Iraq And Oil
Global threats are nothing new to markets, but the impact they can have is incredible. Commodity prices can jump quickly, and volatility can drive markets to the point of collapse; as we saw in the global financial crisis. These days, though, threats seem to be few and far between when it comes to markets.
However, one of the largest threats to the markets has appeared this year, in the form of the ISIS in Iraq. Normally I try and avoid threats to markets and the impact they may have - or just include a sentence of two – but in this case I feel it is actually a serious threat to oil markets.
Currently Iraq is going through the process of 'turning on the taps', or basically getting its oil production back into full swing, after a deadly war, followed by civil unrest. So far so good, and things are starting to happen in Iraq, which has the world’s fifth-largest proven oil reserves.
But the wheels are starting to come unstuck in Iraq and oil production may be severely affected as a result. The ISIS an offshoot of Al-Qaeda and is looking very deadly; they are not led by an ideologist per say, but instead a seasoned battle commander. Hence why they so far have been extremely successful in their ability to move across Iraq and conquer various cities.
In addition to having a heavily armed force, they are not just a terrorist organisation. They act like a state, setting up courts and schools and providing services for the regions that they control. This is not just a side bent on terror, this is an organisation hell bent on conquering the northern part of Iraq and taking vengeance on the current government.
Chances of success when it comes to conquering Baghdad may seem slim, but many have failed to realize the capabilities that they have. After the capitulation in Mosgul, they acquired ammunition and weapons from the escaping army. They are as a result of this now more heavily armed than ever; and in addition to this to they have captured the equivalent ofUS$400 million from the central bank in Mosgul to give them the capital of a small country now.
An escalation in Iraq now seems inevitable, and regional powers are about to get sucked in whether they like it or not. The Kurds are holding their own province in the north, but many see this as a short term move. Long term we could see an Iraq divided by religious grounds, with a north and south much like in the case of Sudan.
This massive build-up of tension will make Ukraine seem like a small problem as Iraq holds a massive oil wealth and sits in one of the world’s most volatile regions. It’s easy to just look at Iraq, but you need to take a look at the bigger picture, and that includes its neighbours like Saudi Arabia, Kuwait, Iran, Syria and Turkey. Many of these neighbours have large reserves of oil and gas and violence can easily spill over borders which are separated by deserts and not by large geographical features.
I had honestly been expecting a small dip down to the trend line, but the recent escalation of tensions in Iraq will have a major impact. American involvement in Iraq again will also play a big role in oil markets getting even more uneasy, as it’s a sign that things really have hit rock bottom again in Iraq as it cannot control the current insurgency.
The last candle was very aggressive in terms of climbing higher.
And with the escalation likely to hit critical points in the next 24 hours, expect to see major climbs in the chart with a target of 110, as that is the heaviest point of resistance.
With the current US stance to not act, any relief may come too late to help any assault on Baghdad, what is clear though is that the oil markets have not priced themselves into a civil war in Iraq, especially one that will destabilise all oil production in the volatile region and have an effect on global prices. ISIS is hell bent on exacting revenge on the current Iraqi government and an attack for them would be coming full circle in their campaign - Oil prices will be quick to react to such aggression!
Unlucky Friday The 13th? U.S. Stocks End Up For The Day But Down For The Week
With a full moon and a Friday the 13th capping a week of election surprises at home — like Eric Cantor’s shocking primary loss in Virginia’s 7th Congressional district — and unrest in Iraq, investors would have been excused for acting skittish in Friday trading. But instead, they sent the U.S. equity markets for a daily gain on Friday, leading all three major indices finishing the day in positive territory. Unfortunately, the late-in-week gains weren’t enough to offset losses from earlier in the week, with the Dow, Nasdaq and S&P 500 ending the week in the red.
The Dow closed Friday up 41.55 points, or 0.25%, as the Nasdaq finished up 13 points, or 0.3%, and the S&P closed 6 points, or 0.3%, higher for the day. All three indices traded in positive territory for the majority of the day on Friday, a bit of a surprise given the unrest in Iraq, which has seen Sunni militants seize broad swaths of Iraqi territory — territory that includes much of the country’s oil fields. This, in turn, has sent oil prices to their highest levels this year: Brent crude futures hit $114 a barrel before settling at $113.50 and oil futures went as high as $107 a barrel before eventually settling around $106. Compare this to their Monday prices: Brent crude opened the week closer to $108 a barrel and oil started Monday trading around $103.
While these price jumps would have caused market jitters and consumer panic 10 years ago, John Canally, an investment strategist with LPL Financial, said that progress the U.S. has made with energy independence means that oil at $107 a barrel won’t threaten the country’s economic recovery — and that this, in turn, explains why stocks were in the green for much of Friday trading.
“These days, even versus 2005, we’re using less gasoline. We’re doing a better job in conserving it that way,” Canally said in a phone interview. “We’re still well below the level where it begins to pinch growth,” he added, noting that investors can start to worry if oil prices start pushing $130, $140 and certainly $150 a barrel. Also, he added, oil prices normally rise in the summer — peaking around the Fourth of July, typically — so a small part of oil’s increase can be attributed to that.
“You have to remember we just went through geopolitical unrest in Ukraine – and that sort of fizzled. Right on the heels of that, we have the issue with Iraq, and the market gets used to these things,” Canally said, explaining the market’s relatively muted response to the popping oil prices. They really reacted on Thursday, he noted, but Friday’s action was, in his view, typical Friday trading behavior. “And quite frankly a lot of people are sitting in front of their computers watching the World Cup,” he laughed.
Canally also noted that the relatively positive performance for equities on a day with a full moon and superstitious date — Friday the 13th — might be a surprise to some, but is consistent with prior Friday the 13th’s.
“In general, Friday the 13th has been up. There have been 186 Friday the 13ths since 1901, and 110 finished up, the rest down,” Canally said. “Friday the 13th’s are better than the average day. And if you look at Friday the 13th in June, 12 of 15 since 1901 have been up. In that regard, the fact that we’re having an up day today makes sense.”
While stocks finished in the green on Friday, the gains were not enough to offset losses from earlier in the week — some of which market insiders attributed to Cantor’s loss on Tuesday, some of which can be attributed to Iraqi tensions that escalated on Thursday. The S&P finished the week down 0.74%, the Dow closed the week with an 0.9% loss and the Nasdaq closed the week down 0.33%. For the Dow and S&P, the losses marked the first weekly losses in four weeks for the indices.
On a stock-by-stock level, two of the market’s biggest gainers were OpenTable, which earlier on Friday announced that it will be acquired by Priceline for $2.6 billion, and retailer Express, which sparked investor interest after a private equity firm, Sycamore Partners, disclosed a near-10% stake in the company. OpenTable finished the day over $104 per share, a 48% surge, and Express finished over $16 per share, a 21% gain.
GBPUSD Fundamentals (based on dailyfx article)
Fundamental Forecast for Pound: BullishThe GBP/USD rallied to a fresh monthly high of 1.6990 as Bank of England (BoE) Governor Mark Carney showed a greater willingness to normalize monetary sooner rather than later, and the pound-dollar may continue to carve a series of higher-highs & higher-lows during the summer months amid the ongoing shift in the policy outlook.
Nevertheless, the data prints due out next week may generate a minor setback in the British Pound rally as the U.K. Consumer Price Index (CPI) is expected to narrow to an annualized 1.7% in May, but the BoE policy statement may heighten the bullish sentiment surrounding the sterling should the central bank adopt a more hawkish tone for monetary policy.
Indeed, the BoE Minutes may reveal a growing dissent within the Monetary Policy Committee (MPC) as a greater number of central bank officials turn increasingly upbeat on the U.K. economy, and the policy statement may spur a more meaningful pickup in interest rate expectations should the committee lay out a more detailed exit strategy. With that said, a split BoE decision may serve as the fundamental catalyst to trigger another near-term rally in the GBP/USD, and we will maintain a bullish outlook for the pair as the Federal Reserve remains reluctant to move away from its zero-interest rate policy (ZIRP).
As a result, the GBP/USD looks poised for a higher-high as it carves higher-lows in June, and we will look for opportunities to ‘buy dips’ in the pound-dollar as the Relative Strength Index (RSI) breaks out of the bearish momentum carried over from the previous month.