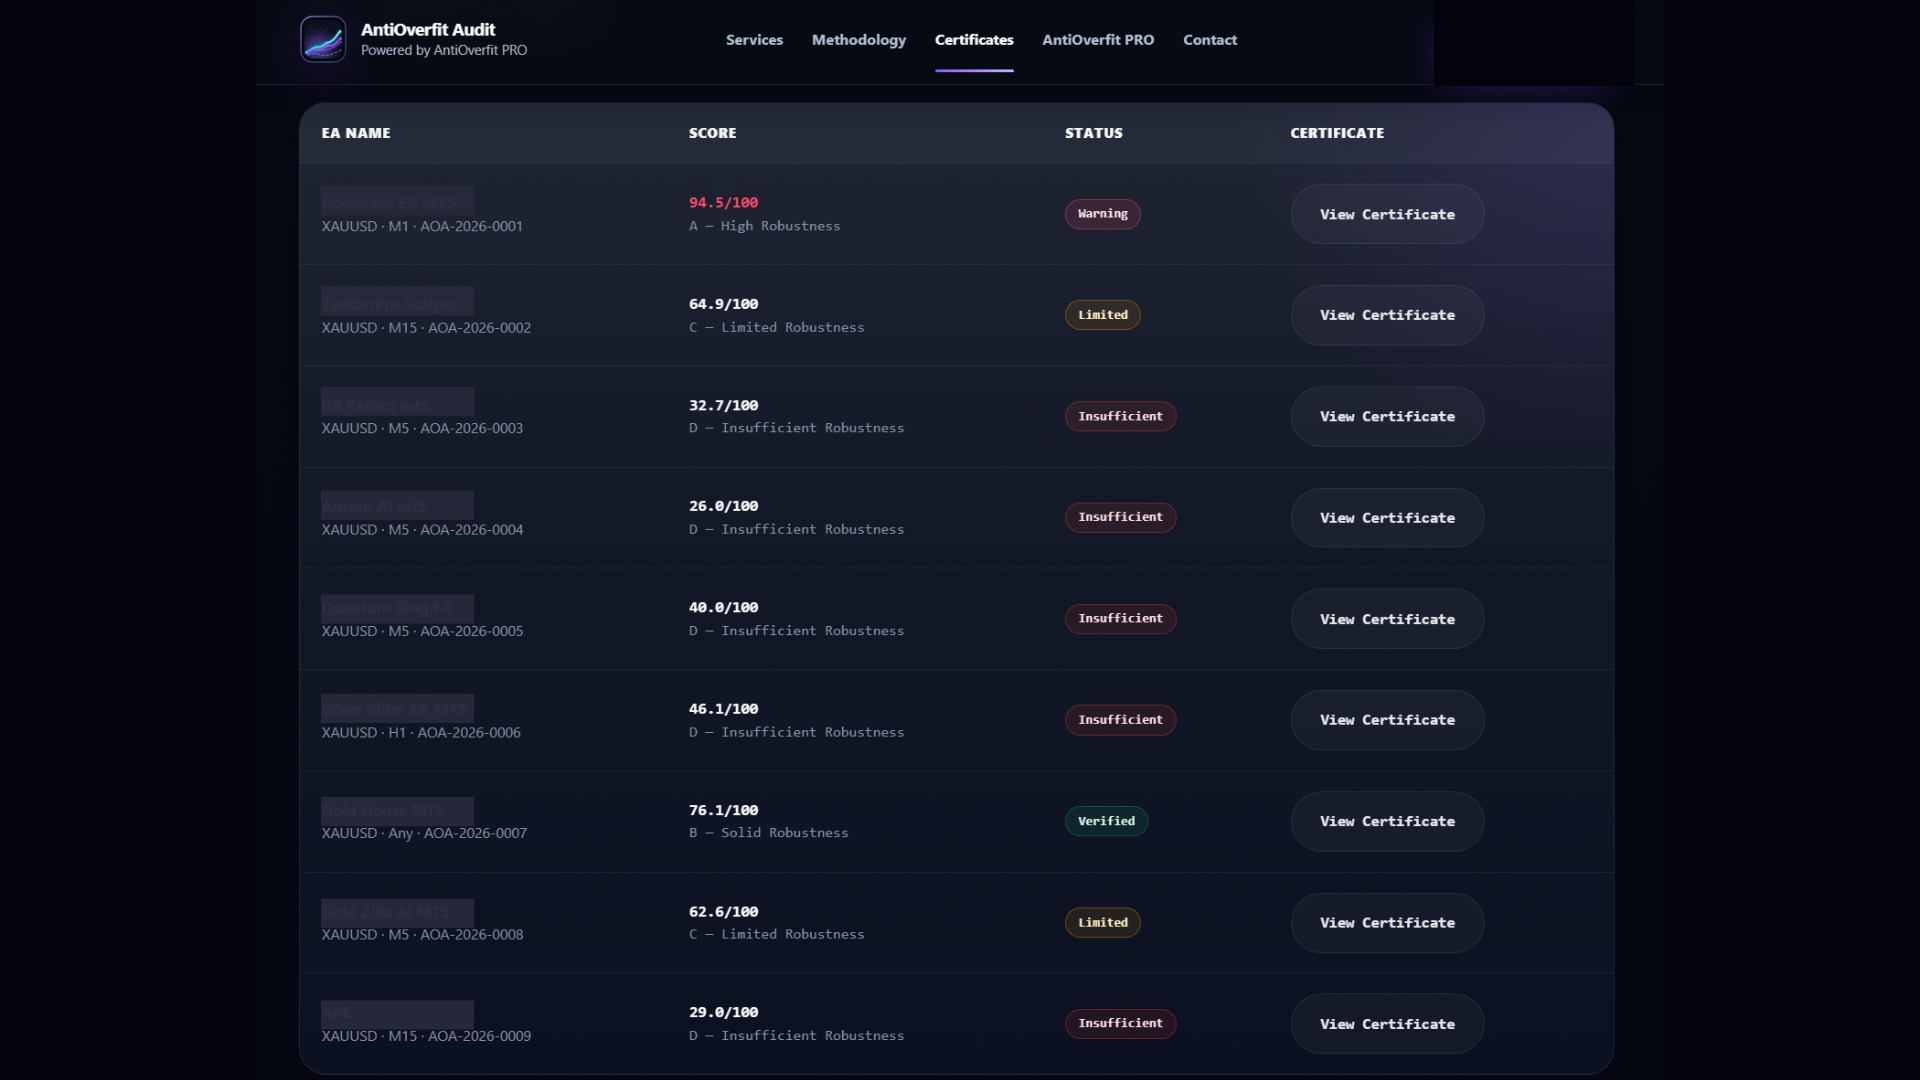
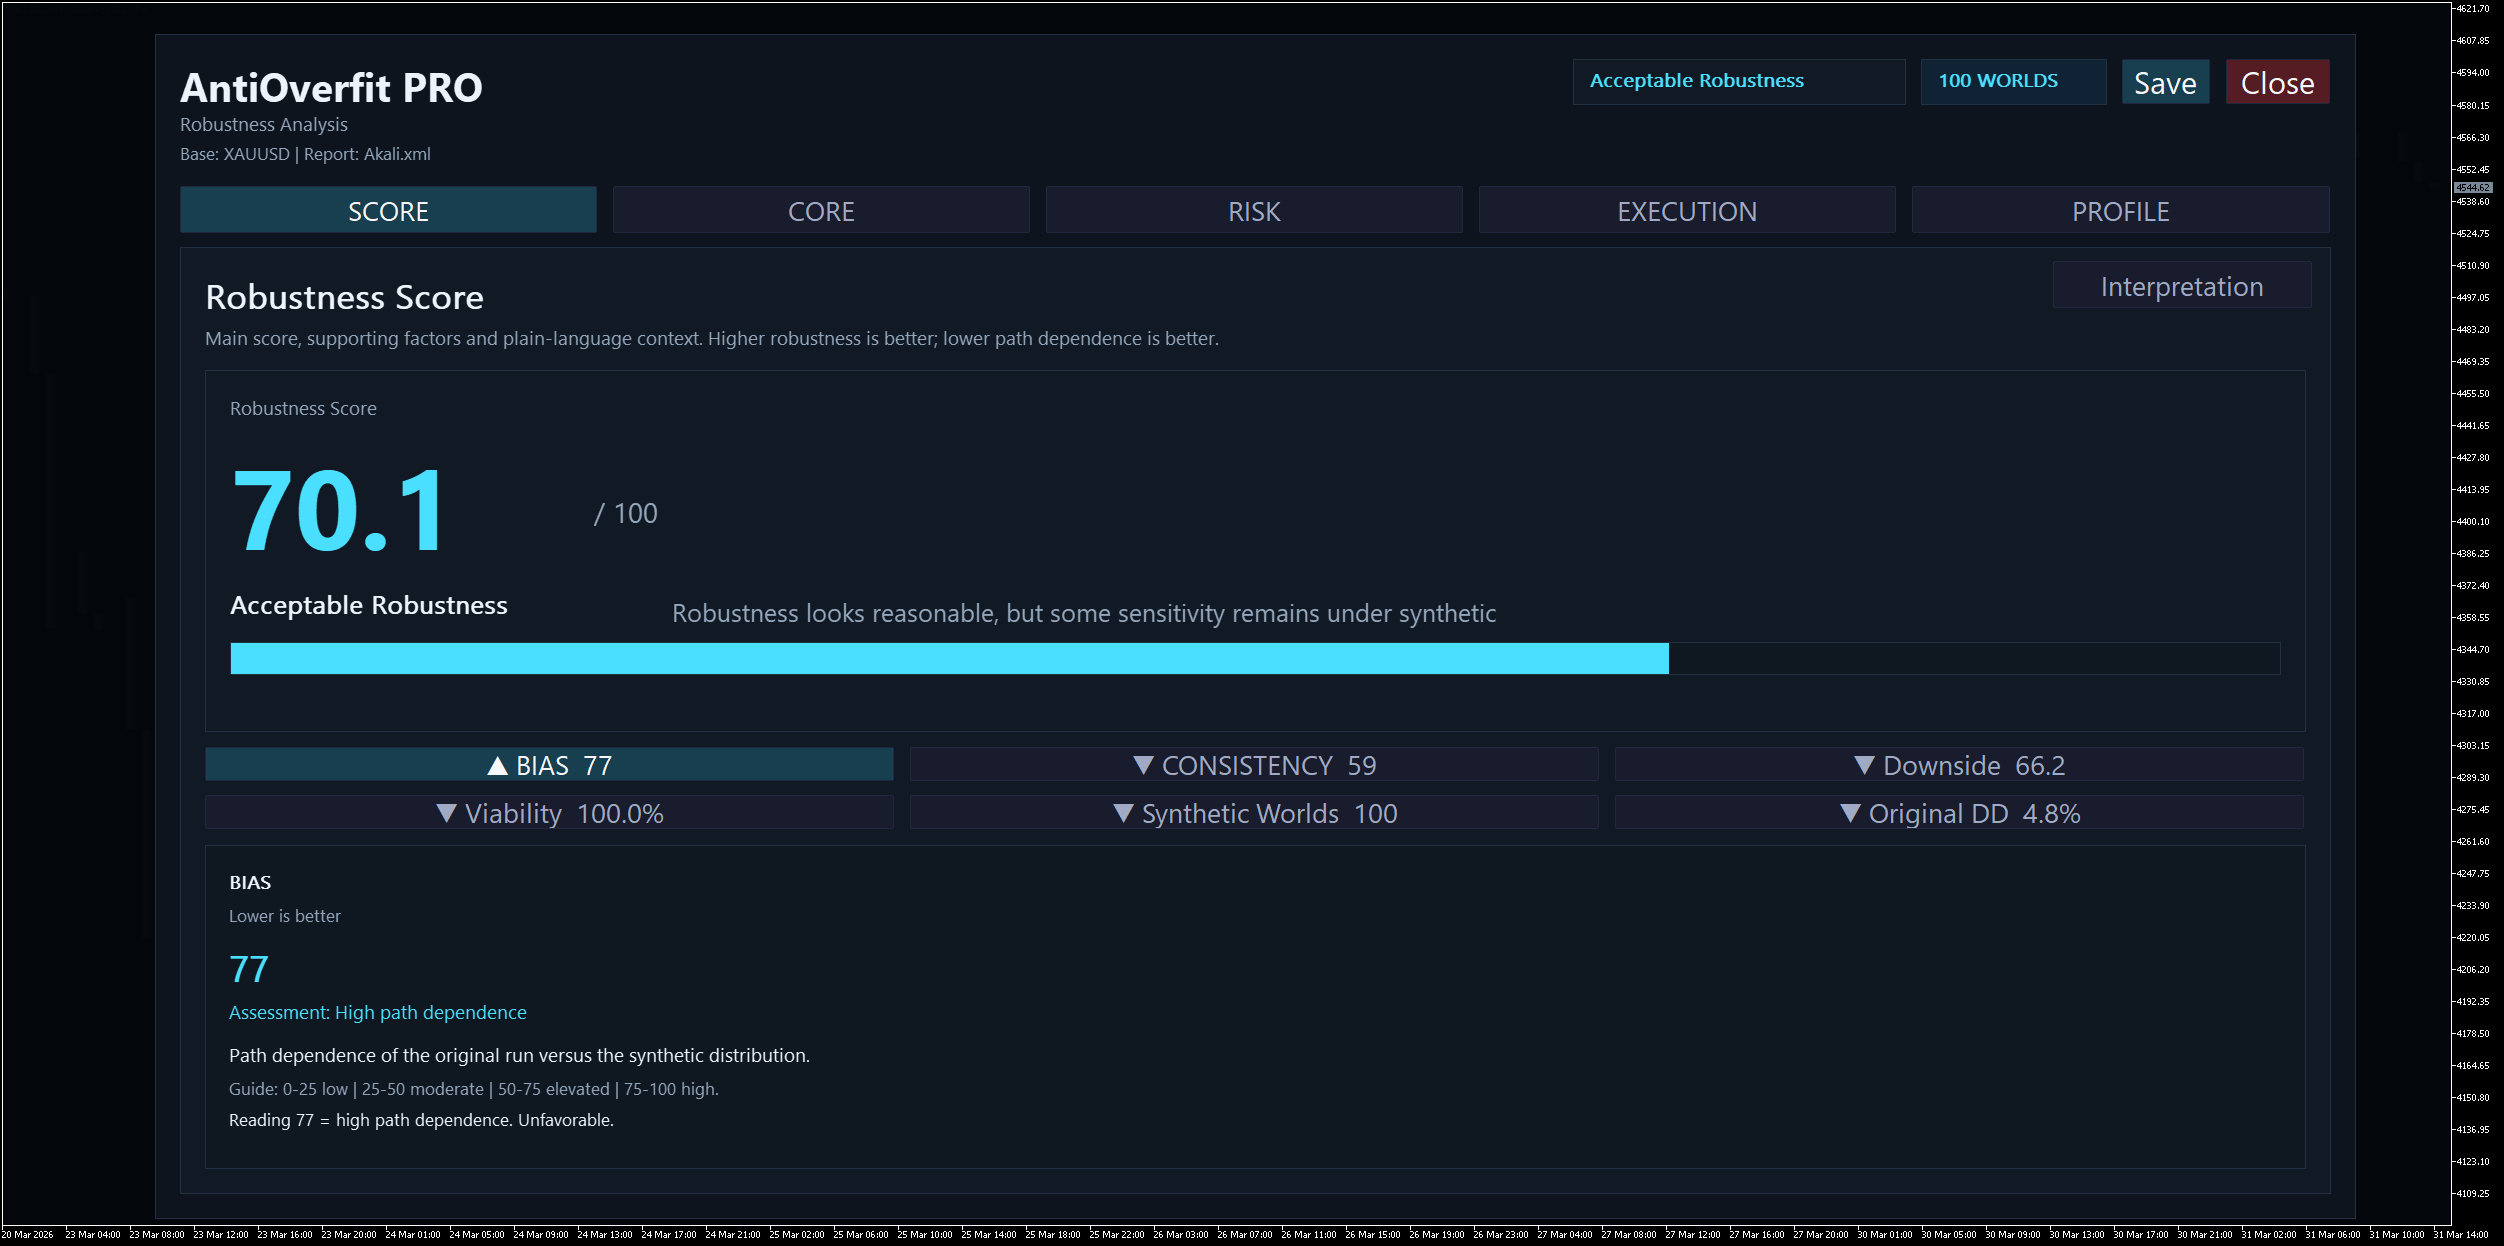
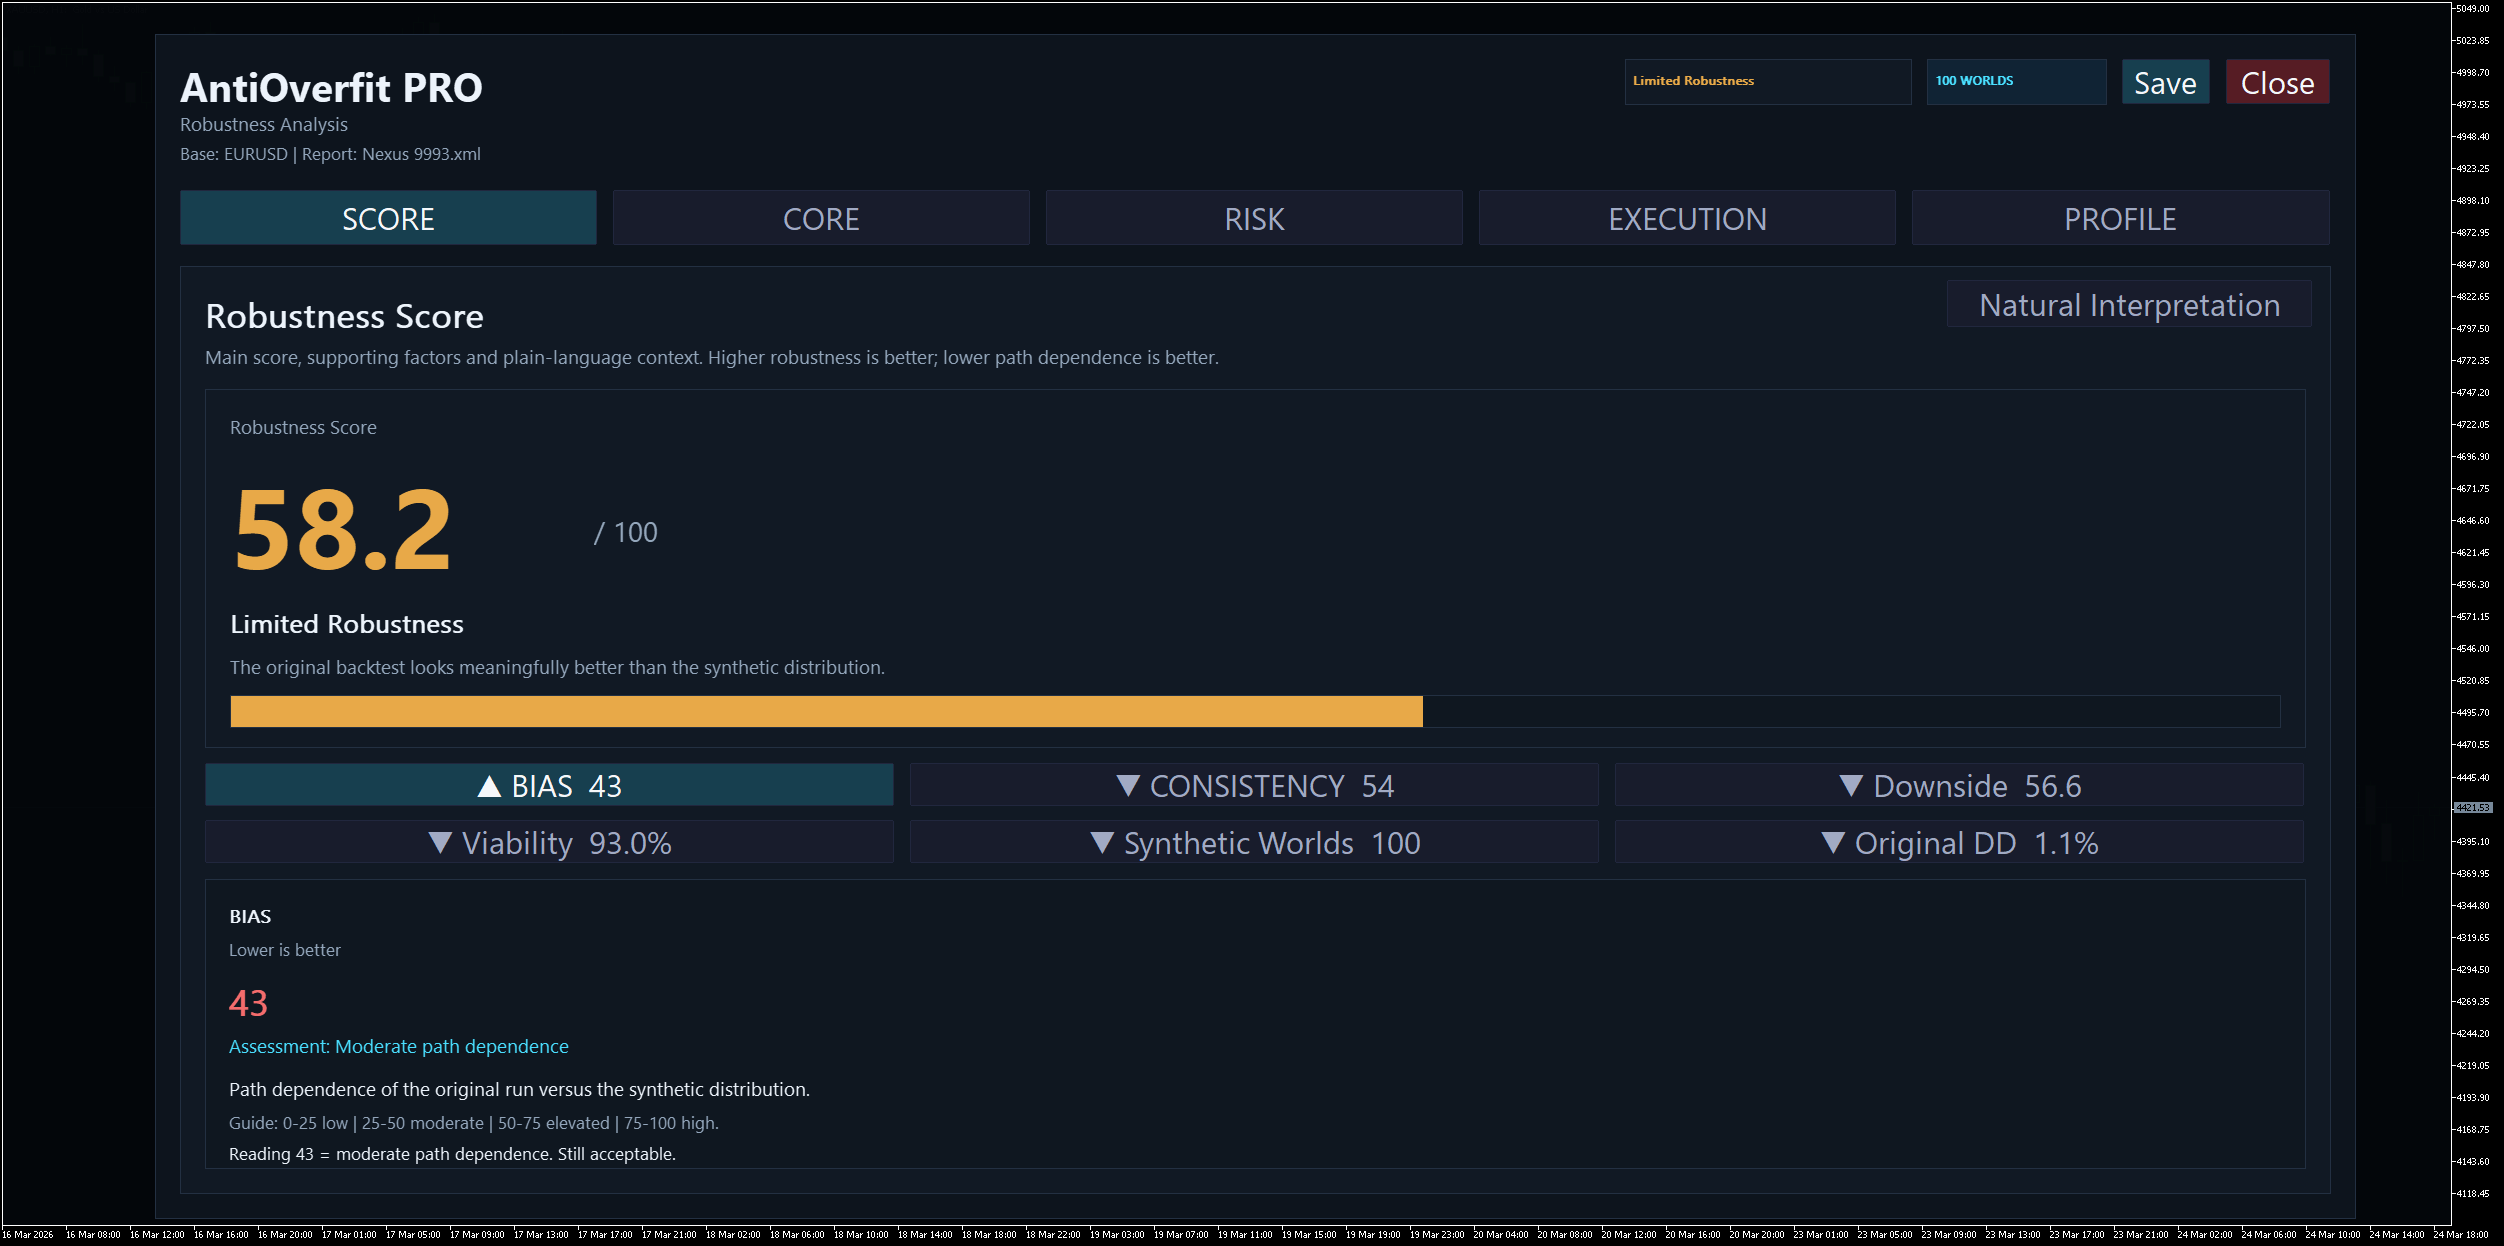
I refuse to believe that traders cannot see the value of AntiOverfit PRO.
In our latest experiment, we tested 10,000 strategies across different symbols and random date ranges:
EURUSD, GBPUSD, USDJPY, USDCAD, AUDUSD and XAUUSD.
The result was not subtle.
The higher the AntiOverfit PRO score, the higher the probability that a strategy achieved a better Forward Profit Factor.
Not every high-score strategy wins.
Not every low-score strategy fails.
That is not the point.
The point is that AntiOverfit PRO does what most traders desperately need but almost never measure properly:
It helps estimate, probabilistically, whether an Expert Advisor has a real chance of surviving outside the backtest.
A beautiful backtest is easy.
A curve-fitted backtest is easy.
Finding a strategy with a better probability of working in the future is the hard part.
And that is exactly where AntiOverfit PRO has value.
If someone cannot see the importance of a tool that helps separate random historical luck from more robust trading candidates, then the problem is not the tool.
The problem is how they understand trading.
AntiOverfit PRO is not a magic button.
It does not promise certainty.
It does not guarantee future profits.
But it gives traders something far more valuable than another optimized equity curve:
A probabilistic edge in strategy selection.
And in systematic trading, that difference matters.
This may be one of my last public posts about AntiOverfit PRO.
But I will say it clearly:
If you are serious about Expert Advisors, robustness testing should not be optional.
It should be part of the process.
https://www.mql5.com/en/market/product/168279
In our latest experiment, we tested 10,000 strategies across different symbols and random date ranges:
EURUSD, GBPUSD, USDJPY, USDCAD, AUDUSD and XAUUSD.
The result was not subtle.
The higher the AntiOverfit PRO score, the higher the probability that a strategy achieved a better Forward Profit Factor.
Not every high-score strategy wins.
Not every low-score strategy fails.
That is not the point.
The point is that AntiOverfit PRO does what most traders desperately need but almost never measure properly:
It helps estimate, probabilistically, whether an Expert Advisor has a real chance of surviving outside the backtest.
A beautiful backtest is easy.
A curve-fitted backtest is easy.
Finding a strategy with a better probability of working in the future is the hard part.
And that is exactly where AntiOverfit PRO has value.
If someone cannot see the importance of a tool that helps separate random historical luck from more robust trading candidates, then the problem is not the tool.
The problem is how they understand trading.
AntiOverfit PRO is not a magic button.
It does not promise certainty.
It does not guarantee future profits.
But it gives traders something far more valuable than another optimized equity curve:
A probabilistic edge in strategy selection.
And in systematic trading, that difference matters.
This may be one of my last public posts about AntiOverfit PRO.
But I will say it clearly:
If you are serious about Expert Advisors, robustness testing should not be optional.
It should be part of the process.
https://www.mql5.com/en/market/product/168279