Algorex Combo Lab
- Experts
-
Daniel Schwoerer
 Algorex Trading Solutions, 2013년 설립, 취리히 소재. 선물, 지수, 금을 위한 규칙 기반 트레이딩 시스템, 인디케이터 및 도구. 트레이더가 만들고 출시 전에 검증합니다.
현재 작업: 세션 유동성, 오프닝 레인지, 모멘텀에 기반한 시스템과 매일의 화면 작업을 위한 도구. MetaTrader 5, 4 및 TradingView 지원. 코칭과 맞춤 개발은 문의 바랍니다. - 버전: 1.10
- 업데이트됨: 14 11월 2026
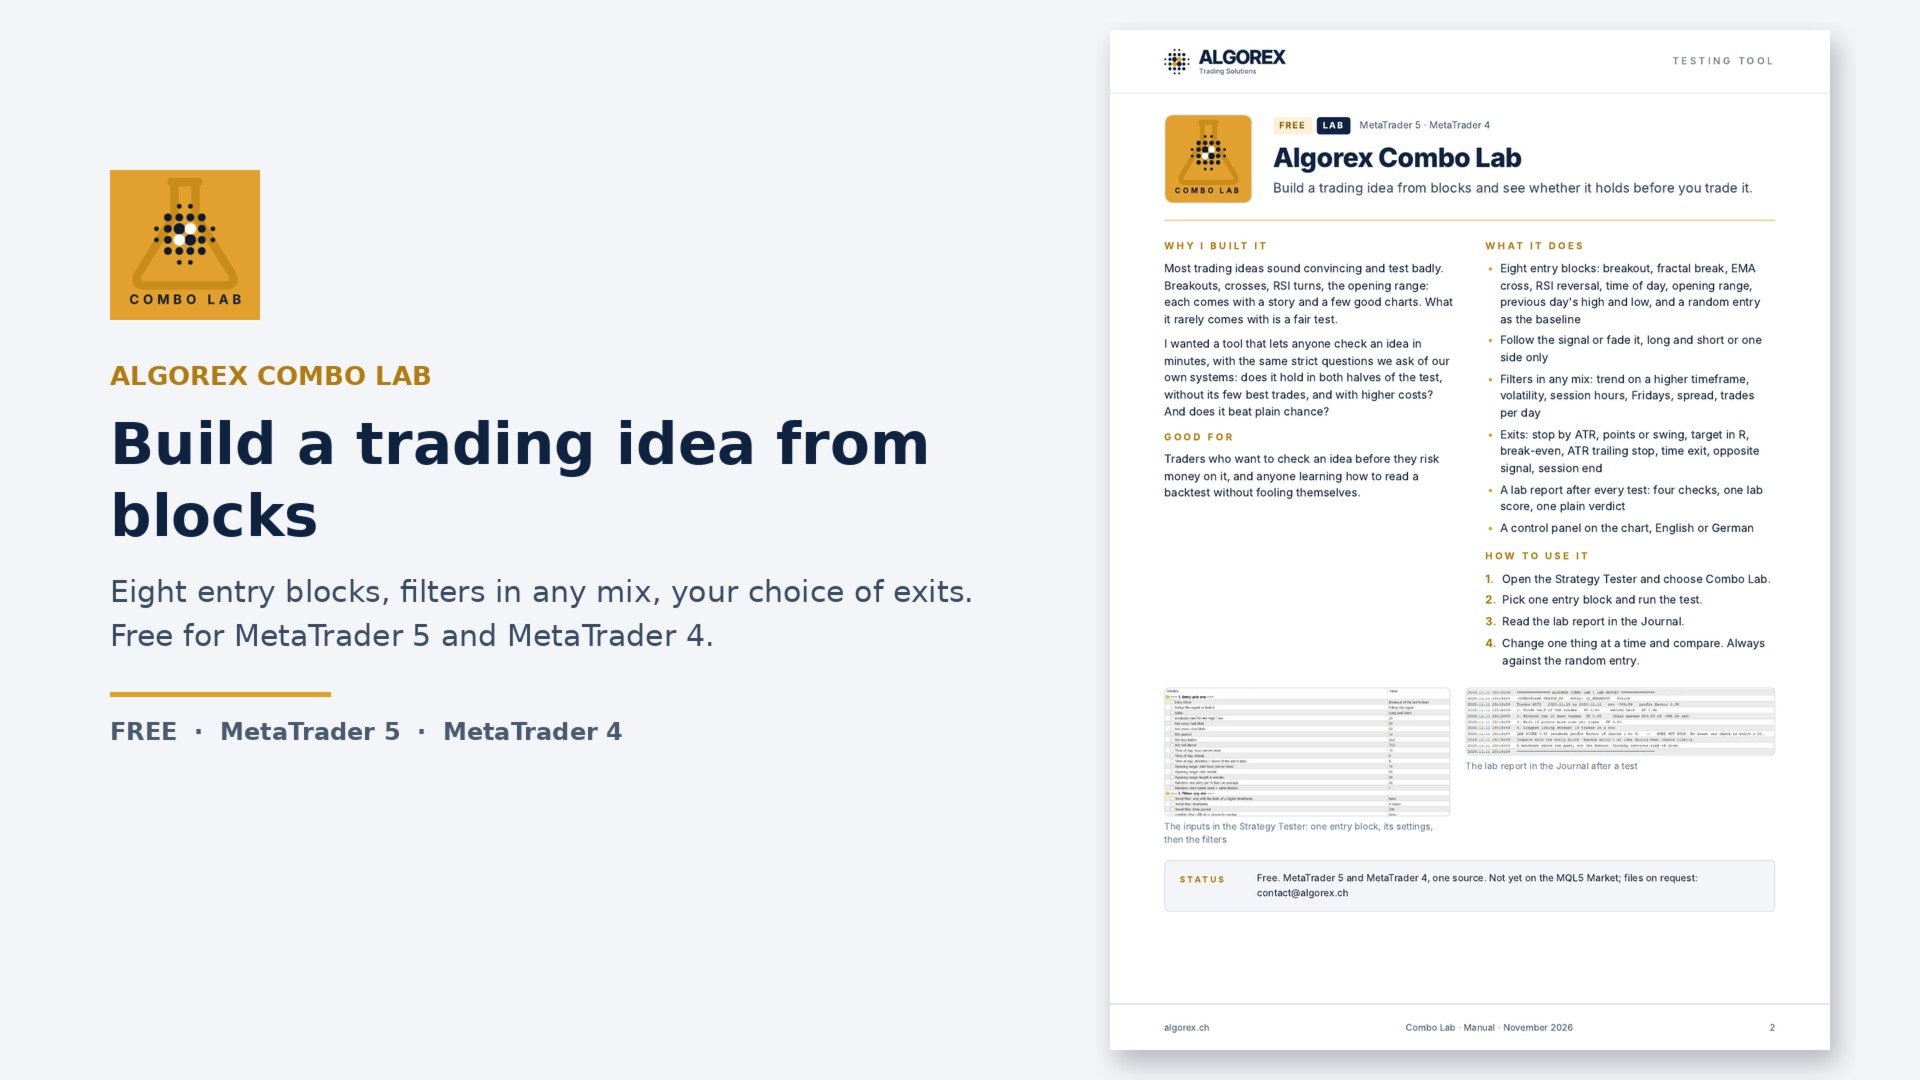
Every trading idea sounds convincing. The question is whether it holds. Algorex Combo Lab lets you try an idea in minutes and keep refining it, with the same strict questions we ask of our own systems: does it hold in both halves of the test, without its few best trades, and with higher costs? And does it beat plain chance?
Combo Lab is a free laboratory for the Strategy Tester. Pick one entry block, switch on any mix of filters, choose your exits, run the test and read the lab report.
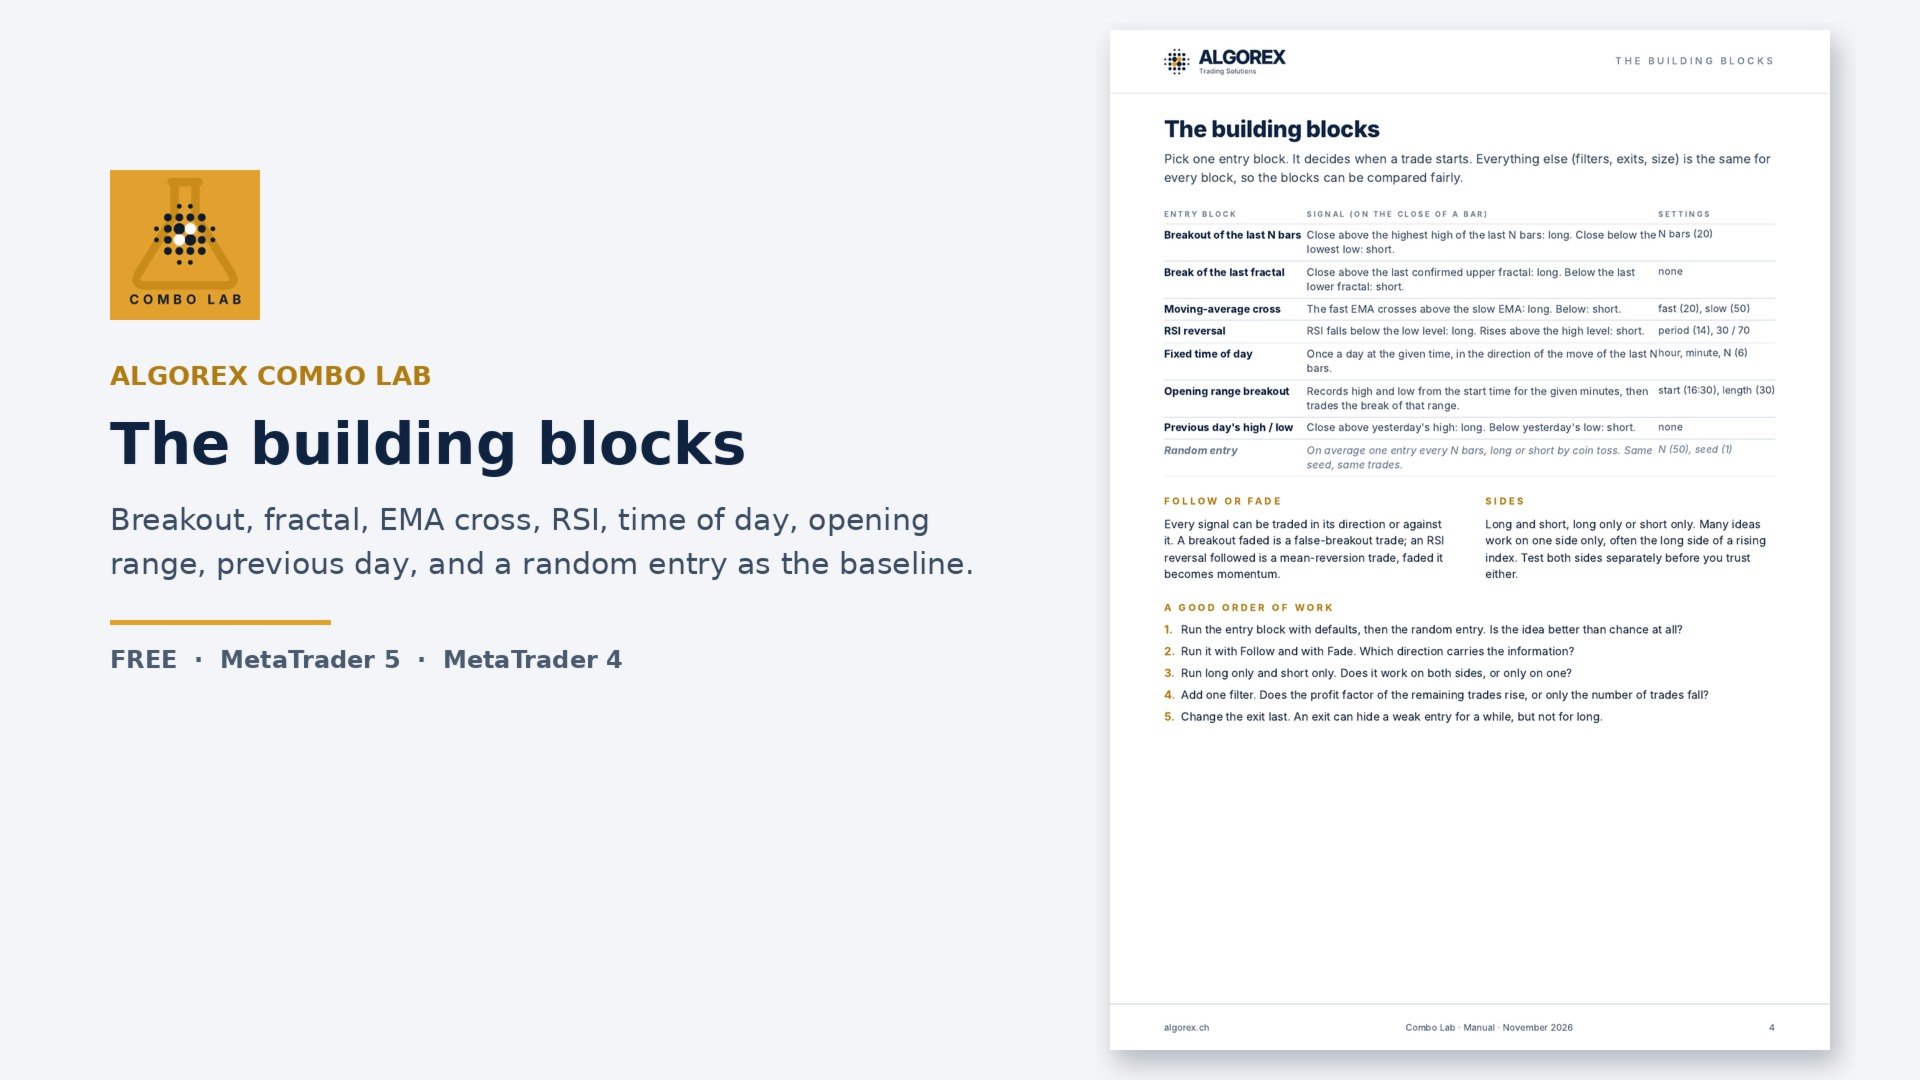
Entry blocks (pick one)
- Breakout of the last N bars
- Break of the last fractal
- Moving-average cross (EMA)
- RSI reversal
- Fixed time of day
- Opening range breakout
- Break of the previous day's high or low
- Random entry: the baseline every idea has to beat
Every block can be followed or faded, traded long and short or on one side only.
Filters (any mix)
- Trend: only with the EMA of a higher timeframe
- Volatility: only when the ATR is at or above its median
- Session hours (server time), no new trades on Friday, maximum spread, maximum trades per day
Exits and size
- Stop by ATR, fixed points or behind the last swing; the stop distance is 1 R
- Target in R, break-even, ATR trailing stop, time exit, opposite signal, session end
- Fixed lots or risk in percent of the balance
The lab report
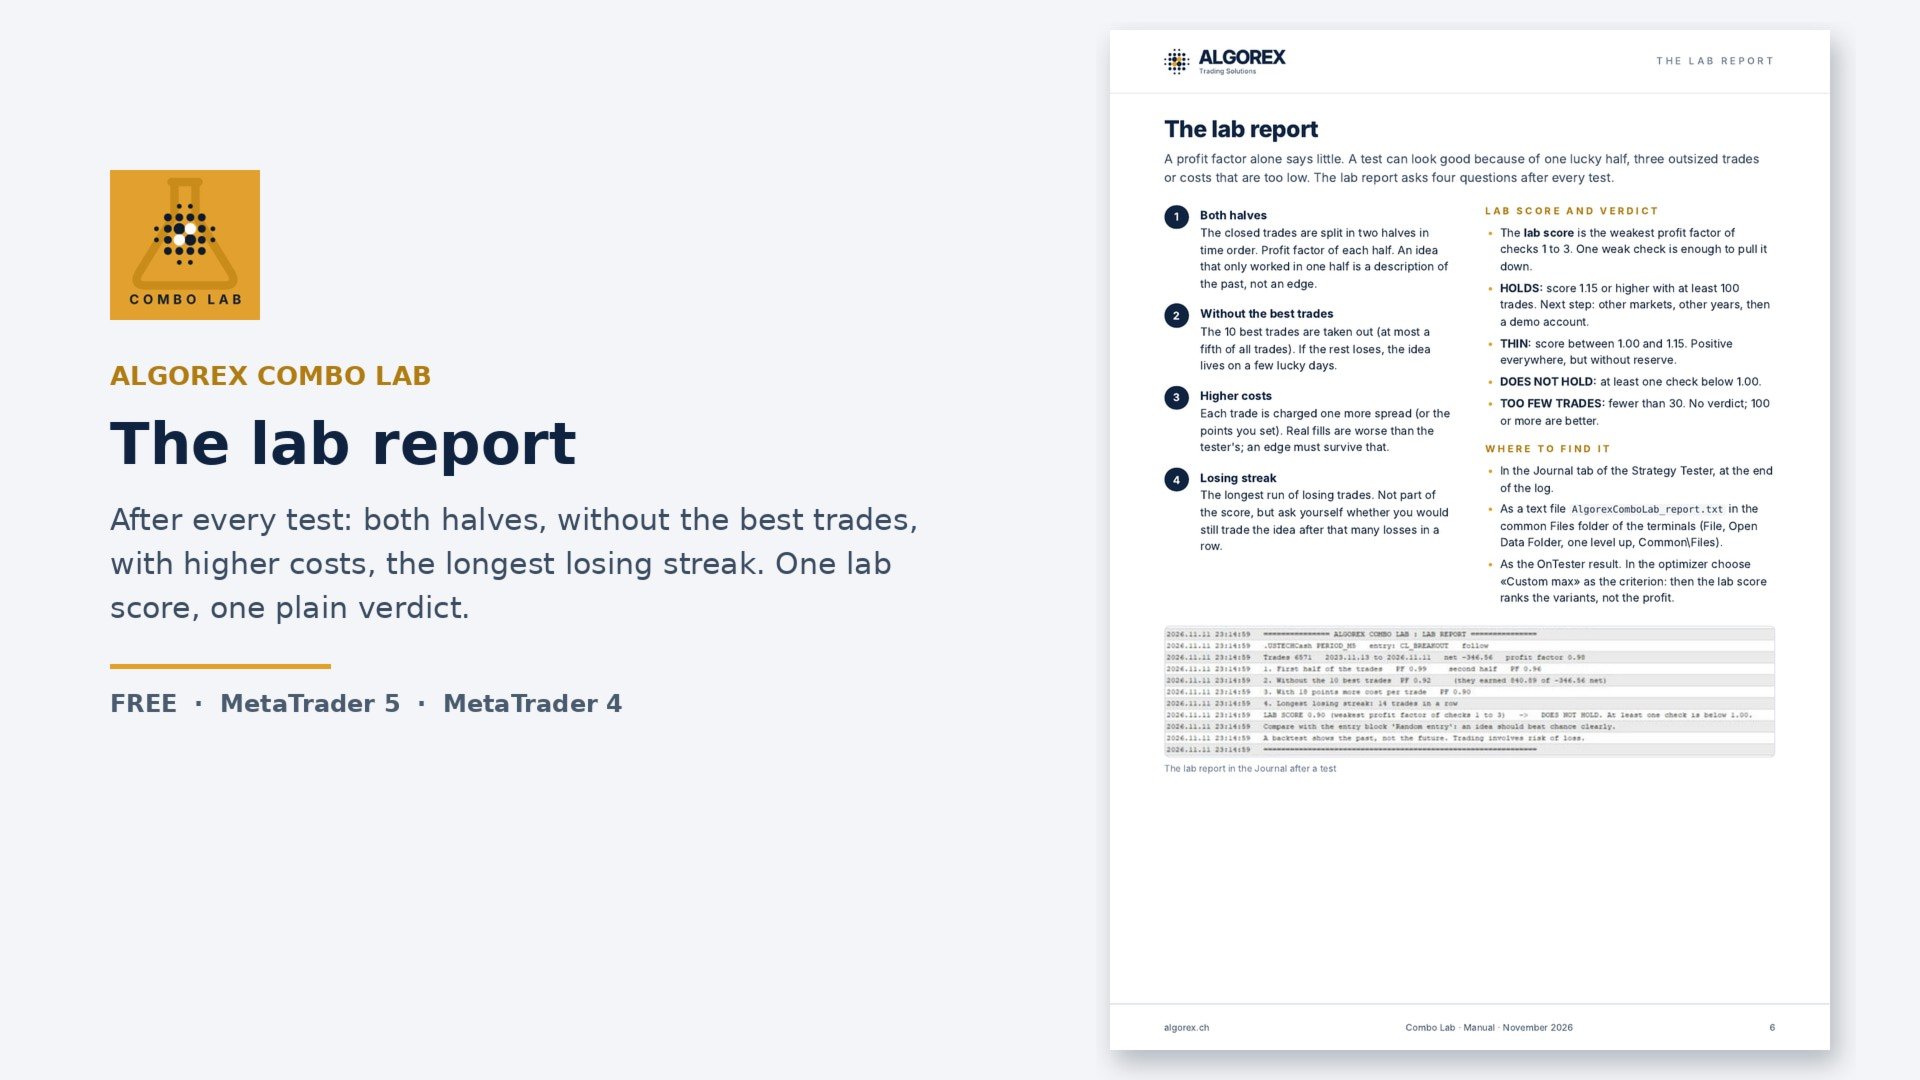
After every test the Journal shows four checks: the profit factor of both halves of the test, the result without the 10 best trades, the result with one more spread of cost per trade, and the longest losing streak. The weakest profit factor of the first three is the lab score, with a plain verdict: HOLDS, THIN, DOES NOT HOLD YET or TOO FEW TRADES. The report is also written to a text file and returned as the custom optimisation criterion, so the optimizer ranks variants by robustness, not by profit.
The scoreboard
All eight entry blocks run side by side in every test, with the same filters, exits and costs, and are ranked by lab score in the panel (button Scoreboard) and at the end of the lab report. Switch on a filter or change an exit and one run shows which idea it helps. Where to start: one question per block, for example whether a breakout carries further with the higher-timeframe trend, or whether the opening range works better long or short. The manual has eight such starting points.
How to use it
- Open the Strategy Tester and choose Algorex Combo Lab.
- Pick one entry block and run the test (MT5: 1 minute OHLC; MT4: every tick).
- Read the lab report at the end of the Journal.
- Change one thing at a time and compare, always against the random entry.
One position at a time. Signals on the close of a bar, entry at the open of the next bar, no look-ahead. Control panel with status, filters, position and statistics; English or German.
A laboratory for testing ideas, not a finished system. No setting is a recommendation, and the default settings are a starting point. A backtest shows the past, not the future. Trading involves risk of loss.