
You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register
Fernando,
your approach looks quite amazing - even though it is not was I was interested in.
So I did it my self with a surprising and so does it look:
The original BB is Tomato the BBema is Green and calculated as
//remark for all buffer the empty value is set to 0.0!
double alpha = 2.0/((double)(BandsPeriod+1));
for(i=0; i<limit; i++) {
MovingBuffer2[i]=iMA(NULL,0,BandsPeriod,BandsShift,MODE_EMA,PRICE_CLOSE,i);
diff = (Close[i] - MovingBuffer2[i]);
DeviBuffer2[i] = DeviBuffer2[i+1]==0.0? diff*diff : (1.0-alpha)*( DeviBuffer2[i+1] + alpha*diff*diff);
UpperBuffer2[i] = MovingBuffer2[i] + sqrt( DeviBuffer2[i] );
LowerBuffer2[i] = MovingBuffer2[i] - sqrt( DeviBuffer2[i] );
}
Am I doing something wrong?
@ Musgni: Read Chapter 9 "Exponentially-weighted mean and variance" - that's about the ema.
So I did it my self with a surprising and so does it look:
The original BB is Tomato the BBema is Green and calculated as
Am I doing something wrong?
Don't mix the iMA with the other equation. Calculate both the "Moving Average" and the "Moving Variance" with the use of the equations in the PDF, namely and I quote:
Don't mix the iMA with the other equation. Calculate both the "Moving Average" and the "Moving Variance" with the use of the equations in the PDF, namely and I quote:
Isn't it that what I did?
I only used the build-in ema = mean = iMa(..., MODE_EMA, ..) - that shouldn't be the problem but (almost) the same!
mean = iMA(...);
x = Close[i];
diff = x-mean;
diff*incr = (Close[i]-iMa(..,i)*alpha*(Close[i]-iMA(..,i) ) = alpha * diff²;
Isn't it that what I did?
I only used the build-in ema = mean = iMa(..., MODE_EMA, ..) - that shouldn't be the problem but (almost) the same!
mean = iMA(...);
x = Close[i];
diff = x-mean;
diff*incr = (Close[i]-iMa(..,i)*alpha*(Close[i]-iMA(..,i) ) = alpha * diff²;
Why use the iMA when the equation for the EMA is much faster and with less rounding errors?
Try it both ways and see for yourself to see if you get the same results.
Also, I repeat, if you are trying to make it superimpose on the original Bollinger, it will never happen - one is based on SMA and the other is based on EMA. They will never be the same.
I know it will never be the same but I haven't expected such a big difference!
The normal (incremental) ema is quite similar to the sma (no interest in that as already proved!) but the variance isn't and that is surprising to me! It looks as if the smoothing is wrong.
I know it will never be the same but I haven't expected such a big difference!
The normal (incremental) ema is quite similar to the sma (no interest in that as already proved!) but the variance isn't and that is surprising to me! It looks as if the smoothing is wrong.
I will take my version of the indicator and remove all the extra stuff and leave just the standard EMA Bollinger bands and send it to you later today, so you can use it as a basis of comparison!
I will take my version of the indicator and remove all the extra stuff and leave just the standard EMA Bollinger bands and send it to you later today, so you can use it as a basis of comparison!
Fernando,
Don't worry about this!! I don't want to blame your indicator (in contrary) - I just wanted to get a feeling about the variance calculated acc. to the article and I am very much surprised about the difference which is a lot bigger that the difference between ema and sma.
Fernando,
Don't worry about this!! I don't want to blame your indicator (in contrary) - I just wanted to get a feeling about the variance calculated acc. to the article and I am very much surprised about the difference which is a lot bigger that the difference between ema and sma.
I have found my problem:
double alpha = 2.0/((double)(BandsPeriod+1));
i = limit;
while(i-->0) { // sorry I took parts of someone else code and didn't check that i has to go from the past to present!
MovingBuffer2[i]=iMA(NULL,0,BandsPeriod,BandsShift,MODE_EMA,PRICE_CLOSE,i);
diff = (Close[i] - MovingBuffer2[i]);
DeviBuffer2[i] = DeviBuffer2[i+1]==0.0? diff*diff : (1.0-alpha)*( DeviBuffer2[i+1] + alpha*diff*diff);
UpperBuffer2[i] = MovingBuffer2[i] + sqrt( DeviBuffer2[i] );
LowerBuffer2[i] = MovingBuffer2[i] - sqrt( DeviBuffer2[i] );
}
Now it looks like:
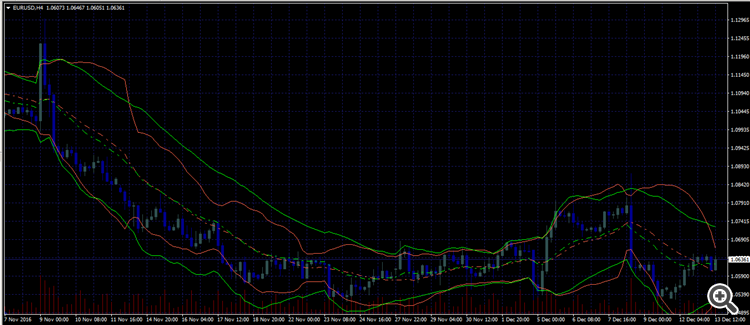
Green are the EMA-Bands Tomato the original BB.