 Все заказы
 Правила
Работа завершена
Техническое задание
i have a simple and specific requirement to modify an indicator. This indicator has 10 buffers for colour as below:
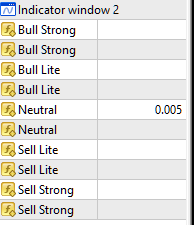
i would like to delete the duplicate buffers for use in EA lab which has a maximum of 8 allowed.
The code is below:
//+------------------------------------------------------------------+
//| iRimbab_1.mq4 |
//| Copyright 2019, MetaQuotes Software Corp. |
//| https://www.mql5.com |
//+------------------------------------------------------------------+
#property copyright "Copyright 2019, MetaQuotes Software Corp."
#property link "https://www.mql5.com"
#property version "1.00"
#property strict
#property indicator_separate_window
#property indicator_buffers 10
#property indicator_label1 "Bull Strong"
#property indicator_color1 clrBlue
#property indicator_type1 DRAW_HISTOGRAM
#property indicator_width1 4
#property indicator_label4 "Bull Lite"
#property indicator_color4 clrBlue
#property indicator_type4 DRAW_HISTOGRAM
#property indicator_width4 4
#property indicator_label6 "Neutral"
#property indicator_color6 clrGray
#property indicator_type6 DRAW_HISTOGRAM
#property indicator_width6 4
#property indicator_label7 "Sell Lite"
#property indicator_color7 clrRed
#property indicator_type7 DRAW_HISTOGRAM
#property indicator_width7 4
#property indicator_label9 "Sell Strong"
#property indicator_color9 clrRed
#property indicator_type9 DRAW_HISTOGRAM
#property indicator_width9 4
//---
enum E_MODE
{
MOD_RSI =0, //RSI
MOD_STO =1, //STOCHASTIC
MOD_ADX =2 //ADX
};
//---
enum E_TYPE
{
TYP_ALMA =0, //ALMA
TYP_EMA =1, //EMA
TYP_WMA =2, //WMA
TYP_SMA =3, //SMA
TYP_SMMA =4, //SMMA
TYP_HMA =5 //HMA
};
//+------------------------------------------------------------------+
//| |
//+------------------------------------------------------------------+
input int Length =6; //Period of Evaluation
input int Smooth =1; //Period of Smoothing
input ENUM_APPLIED_PRICE Source =PRICE_CLOSE; //Source
input E_MODE Mode =MOD_RSI; //Indicator Method
input E_TYPE Type =TYP_WMA; //MA
input double Offset =0.85; //* Arnaud Legoux (ALMA) Only - Offset Value
input double Sigma =6.0; //* Arnaud Legoux (ALMA) Only - Sigma Value
input int MaxBar =1000; //Max Bars
//+------------------------------------------------------------------+
//| |
//+------------------------------------------------------------------+
#include <MovingAverages.mqh>
//---
double BS[];
double BSZ[];
double BL[];
double BLZ[];
double Nt[];
double NtZ[];
double SL[];
double SLZ[];
double SS[];
double SSZ[];
double MA[];
double Bull[];
double Bear[];
double Temp[];
double Price[];
double AvBull[];
double AvBear[];
double SmBull[];
double SmBear[];
double W[];
//+------------------------------------------------------------------+
//| Custom indicator initialization function |
//+------------------------------------------------------------------+
int OnInit()
{
Comment("");
IndicatorBuffers(19);
int cnt=0;
SetIndexBuffer(cnt,BS,INDICATOR_DATA);
SetIndexEmptyValue(cnt,NULL);
cnt++;
SetIndexBuffer(cnt,BSZ,INDICATOR_DATA);
SetIndexEmptyValue(cnt,NULL);
cnt++;
SetIndexBuffer(cnt,BL,INDICATOR_DATA);
SetIndexEmptyValue(cnt,NULL);
cnt++;
SetIndexBuffer(cnt,BLZ,INDICATOR_DATA);
SetIndexEmptyValue(cnt,NULL);
cnt++;
SetIndexBuffer(cnt,Nt,INDICATOR_DATA);
SetIndexEmptyValue(cnt,NULL);
cnt++;
SetIndexBuffer(cnt,NtZ,INDICATOR_DATA);
SetIndexEmptyValue(cnt,NULL);
cnt++;
SetIndexBuffer(cnt,SL,INDICATOR_DATA);
SetIndexEmptyValue(cnt,NULL);
cnt++;
SetIndexBuffer(cnt,SLZ,INDICATOR_DATA);
SetIndexEmptyValue(cnt,NULL);
cnt++;
SetIndexBuffer(cnt,SS,INDICATOR_DATA);
SetIndexEmptyValue(cnt,NULL);
cnt++;
SetIndexBuffer(cnt,SSZ,INDICATOR_DATA);
SetIndexEmptyValue(cnt,NULL);
cnt++;
SetIndexBuffer(cnt,MA,INDICATOR_CALCULATIONS);
SetIndexEmptyValue(cnt,NULL);
cnt++;
SetIndexBuffer(cnt,Bull,INDICATOR_CALCULATIONS);
SetIndexEmptyValue(cnt,NULL);
cnt++;
SetIndexBuffer(cnt,Bear,INDICATOR_CALCULATIONS);
SetIndexEmptyValue(cnt,NULL);
cnt++;
SetIndexBuffer(cnt,Temp,INDICATOR_CALCULATIONS);
SetIndexEmptyValue(cnt,NULL);
cnt++;
SetIndexBuffer(cnt,Price,INDICATOR_CALCULATIONS);
SetIndexEmptyValue(cnt,NULL);
cnt++;
SetIndexBuffer(cnt,AvBull,INDICATOR_CALCULATIONS);
SetIndexEmptyValue(cnt,NULL);
cnt++;
SetIndexBuffer(cnt,AvBear,INDICATOR_CALCULATIONS);
SetIndexEmptyValue(cnt,NULL);
cnt++;
SetIndexBuffer(cnt,SmBull,INDICATOR_CALCULATIONS);
SetIndexEmptyValue(cnt,NULL);
cnt++;
SetIndexBuffer(cnt,SmBear,INDICATOR_CALCULATIONS);
IndicatorSetInteger(INDICATOR_DIGITS,_Digits+1);
IndicatorSetString(INDICATOR_SHORTNAME,
MQLInfoString(MQL_PROGRAM_NAME)+" ("+
IntegerToString(Length)+", "+
IntegerToString(Smooth)+", "+
StringSubstr(EnumToString(Source),StringLen("PRICE_"))+", "+
StringSubstr(EnumToString(Mode),StringLen("MOD_"))+", "+
StringSubstr(EnumToString(Type),StringLen("TYP_"))+", "+
DoubleToString(Offset,2)+", "+
DoubleToString(Sigma,2)+")");
return(INIT_SUCCEEDED);
}
//+------------------------------------------------------------------+
//| Custom indicator iteration function |
//+------------------------------------------------------------------+
int OnCalculate(const int rates_total,
const int prev_calculated,
const datetime &time[],
const double &open[],
const double &high[],
const double &low[],
const double &close[],
const long &tick_volume[],
const long &volume[],
const int &spread[])
{
int limit=rates_total-prev_calculated;
if(limit>1)
{
limit=fmin(MaxBar,rates_total)-Length-2;
for(int i=0; i<rates_total; i++)
PlotZ(i);
if(Type==TYP_ALMA)
{
ArrayResize(W,Length);
double m=floor(Offset*(Length-1));
double s=Length/Sigma;
double wSum=0;
double t=(2*s*s);
for(int i=0; i<Length; i++)
{
W[i]=exp(-((i-m)*(i-m))/((t==NULL) ?1.0 :t));
wSum+= W[i];
}
for(int i=0; i<Length; i++)
W[i]=W[i]/wSum;
}
}
else
limit++;
for(int i=limit; i>=0; i--)
{
PlotZ(i);
Price[i]=Price(Source,i,open[i],high[i],low[i],close[i]);
switch(Type)
{
case TYP_HMA:
Temp[i]=iMA(_Symbol,PERIOD_CURRENT,(int)floor(Length/2),0,MODE_LWMA,Source,i)*2-iMA(_Symbol,PERIOD_CURRENT,Length,0,MODE_LWMA,Source,i);
break;
}
}
for(int i=limit; i>=0; i--)
{
MA[i]=iMA(_Symbol,PERIOD_CURRENT,1,0,MODE_SMA,Source,i);
switch(Mode)
{
case MOD_STO:
Bull[i]=MA[i]-MA[ArrayMinimum(MA,Length,i)];
Bear[i]=MA[ArrayMaximum(MA,Length,i)]-MA[i];
break;
case MOD_RSI:
Bull[i]=0.5*(fabs(MA[i]-MA[i+1])+(MA[i]-MA[i+1]));
Bear[i]=0.5*(fabs(MA[i]-MA[i+1])-(MA[i]-MA[i+1]));
break;
case MOD_ADX:
Bull[i]=0.5*(fabs(high[i]-high[i+1])+(high[i]-high[i+1]));
Bear[i]=0.5*(fabs(low[i+1]-low[i])+(low[i+1]-low[i]));
break;
}
AvBull[i]=MA(Bull,Length,i);
AvBear[i]=MA(Bear,Length,i);
}
for(int i=limit; i>=0; i--)
{
SmBull[i]=MA(AvBull,Smooth,i);
SmBear[i]=MA(AvBear,Smooth,i);
double dif=fabs(SmBull[i]-SmBear[i]);
if(dif>SmBull[i])
{
if(SmBear[i]<SmBear[i+1])
SS[i]=dif;
else
SL[i]=dif;
continue;
}
if(dif>SmBear[i])
{
if(SmBull[i]<SmBull[i+1])
BS[i]=dif;
else
BL[i]=dif;
continue;
}
Nt[i]=dif;
}
return(rates_total);
}
//+------------------------------------------------------------------+
//| |
//+------------------------------------------------------------------+
double MA(double &vBuf[],const int vLen,const int vxPos)
{
double sum=0.0;
switch(Type)
{
case TYP_SMA:
return(iMAOnArray(vBuf,0,vLen,0,MODE_SMA,vxPos));
case TYP_EMA:
return(iMAOnArray(vBuf,0,vLen,0,MODE_EMA,vxPos));
case TYP_SMMA:
return(iMAOnArray(vBuf,0,vLen,0,MODE_SMMA,vxPos));
case TYP_WMA:
return(iMAOnArray(vBuf,0,vLen,0,MODE_LWMA,vxPos));
case TYP_HMA:
return(iMAOnArray(vBuf,0,(int)floor(sqrt(vLen)),0,MODE_LWMA,vxPos));
case TYP_ALMA:
for(int i=0; i<vLen; i++)
sum+=vBuf[vxPos+(vLen-1-i)]*W[i];
return(sum);
}
return(NULL);
}
//+------------------------------------------------------------------+
//| |
//+------------------------------------------------------------------+
double Price(const ENUM_APPLIED_PRICE vApp,const int vxPos,const double vOp,const double vHi,const double vLo,const double vCl)
{
switch(vApp)
{
case PRICE_CLOSE:
return(vCl);
case PRICE_HIGH:
return(vHi);
case PRICE_LOW:
return(vLo);
case PRICE_OPEN:
return(vOp);
case PRICE_MEDIAN:
return((vHi+vLo)/2.0);
case PRICE_TYPICAL:
return((vHi+vLo+vCl)/3.0);
case PRICE_WEIGHTED:
return((vHi+vLo+vCl+vCl)/4.0);
}
return(NULL);
}
//+------------------------------------------------------------------+
//| |
//+------------------------------------------------------------------+
void PlotZ(int vxPos)
{
BS[vxPos]=NULL;
BSZ[vxPos]=NULL;
BL[vxPos]=NULL;
BLZ[vxPos]=NULL;
Nt[vxPos]=NULL;
NtZ[vxPos]=NULL;
SL[vxPos]=NULL;
SLZ[vxPos]=NULL;
SS[vxPos]=NULL;
SSZ[vxPos]=NULL;
MA[vxPos]=NULL;
Bull[vxPos]=NULL;
Bear[vxPos]=NULL;
Temp[vxPos]=NULL;
Price[vxPos]=NULL;
AvBull[vxPos]=NULL;
AvBear[vxPos]=NULL;
SmBull[vxPos]=NULL;
SmBear[vxPos]=NULL;
}
//+------------------------------------------------------------------+
//---
//---
//+------------------------------------------------------------------+
//| |
//+------------------------------------------------------------------+
//---