October 26, 2026 – October 30, 2026
The 5.05% Yield Surge and the $3,880 Golden Flush: Fed-ECB Collision, Big Tech Capex Skepticism, and the 1.1110 Euro Bear Trap
Forex: The Euro’s 1.1110 Double-Bottom Trap and the Transatlantic Central Bank Squeeze
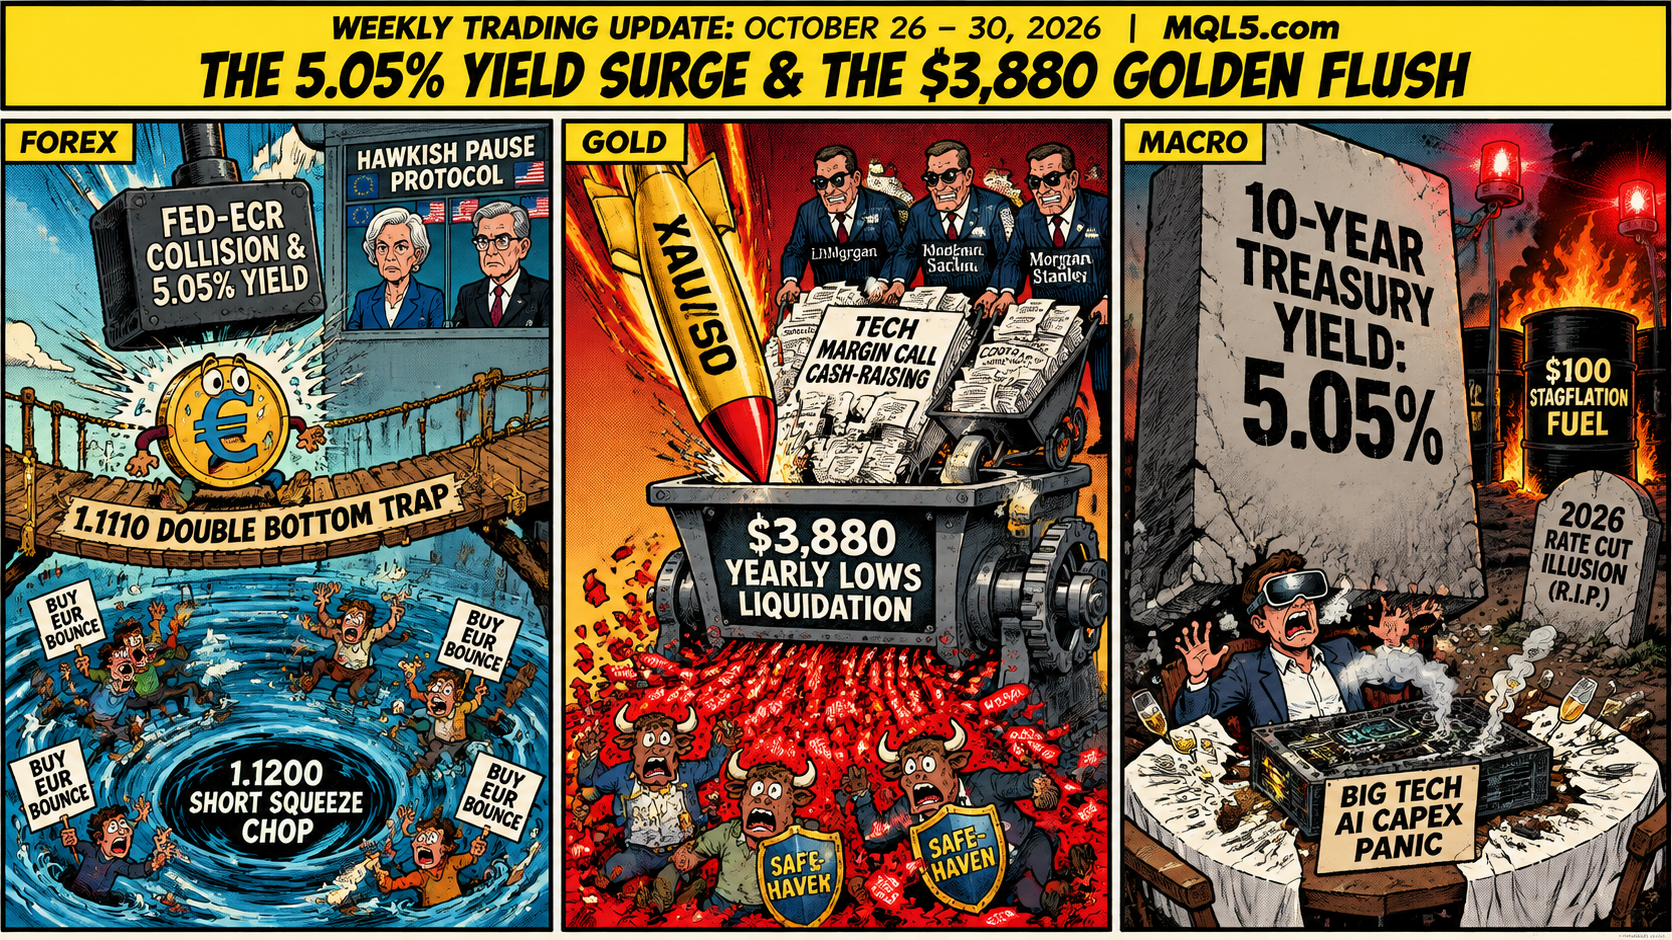
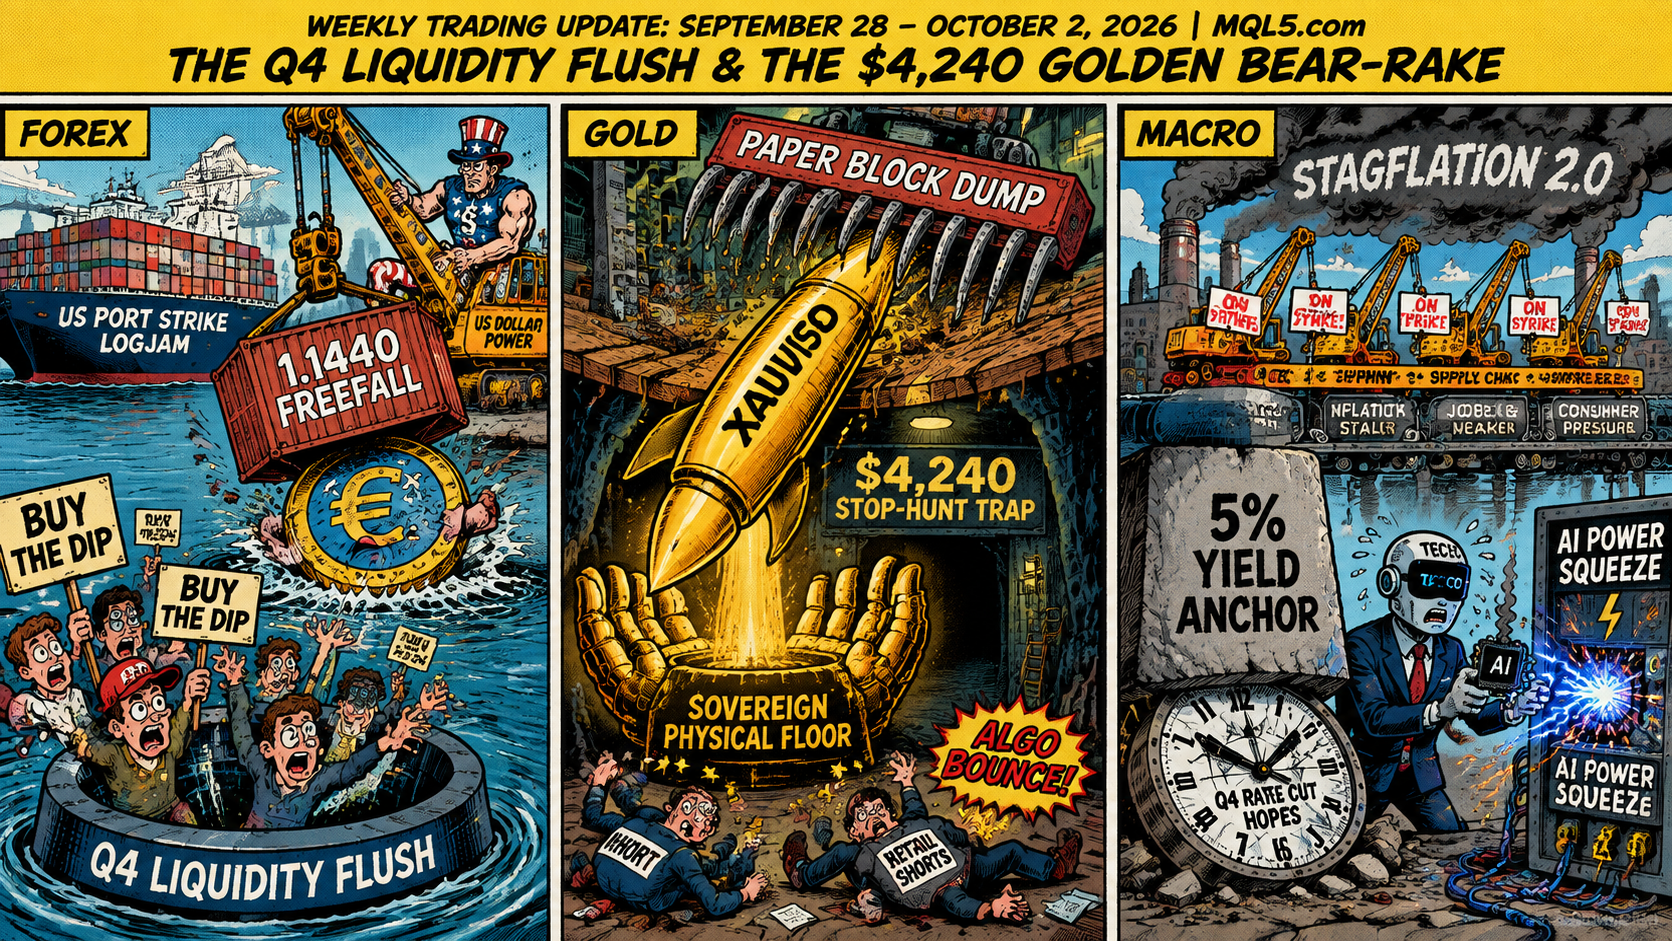
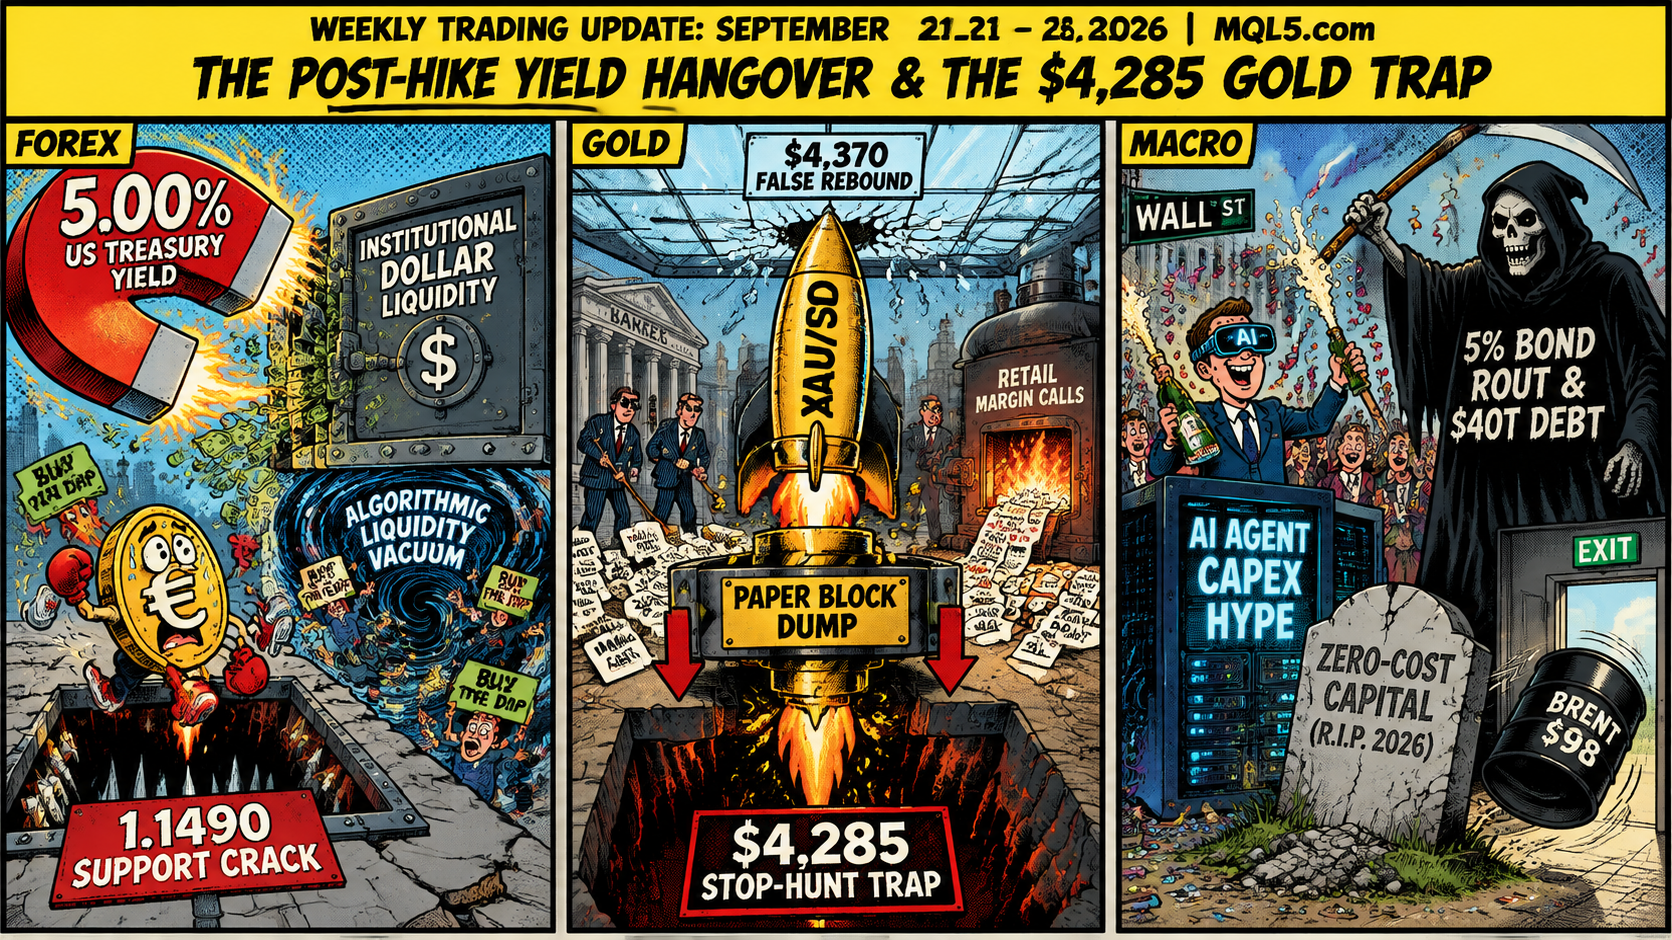
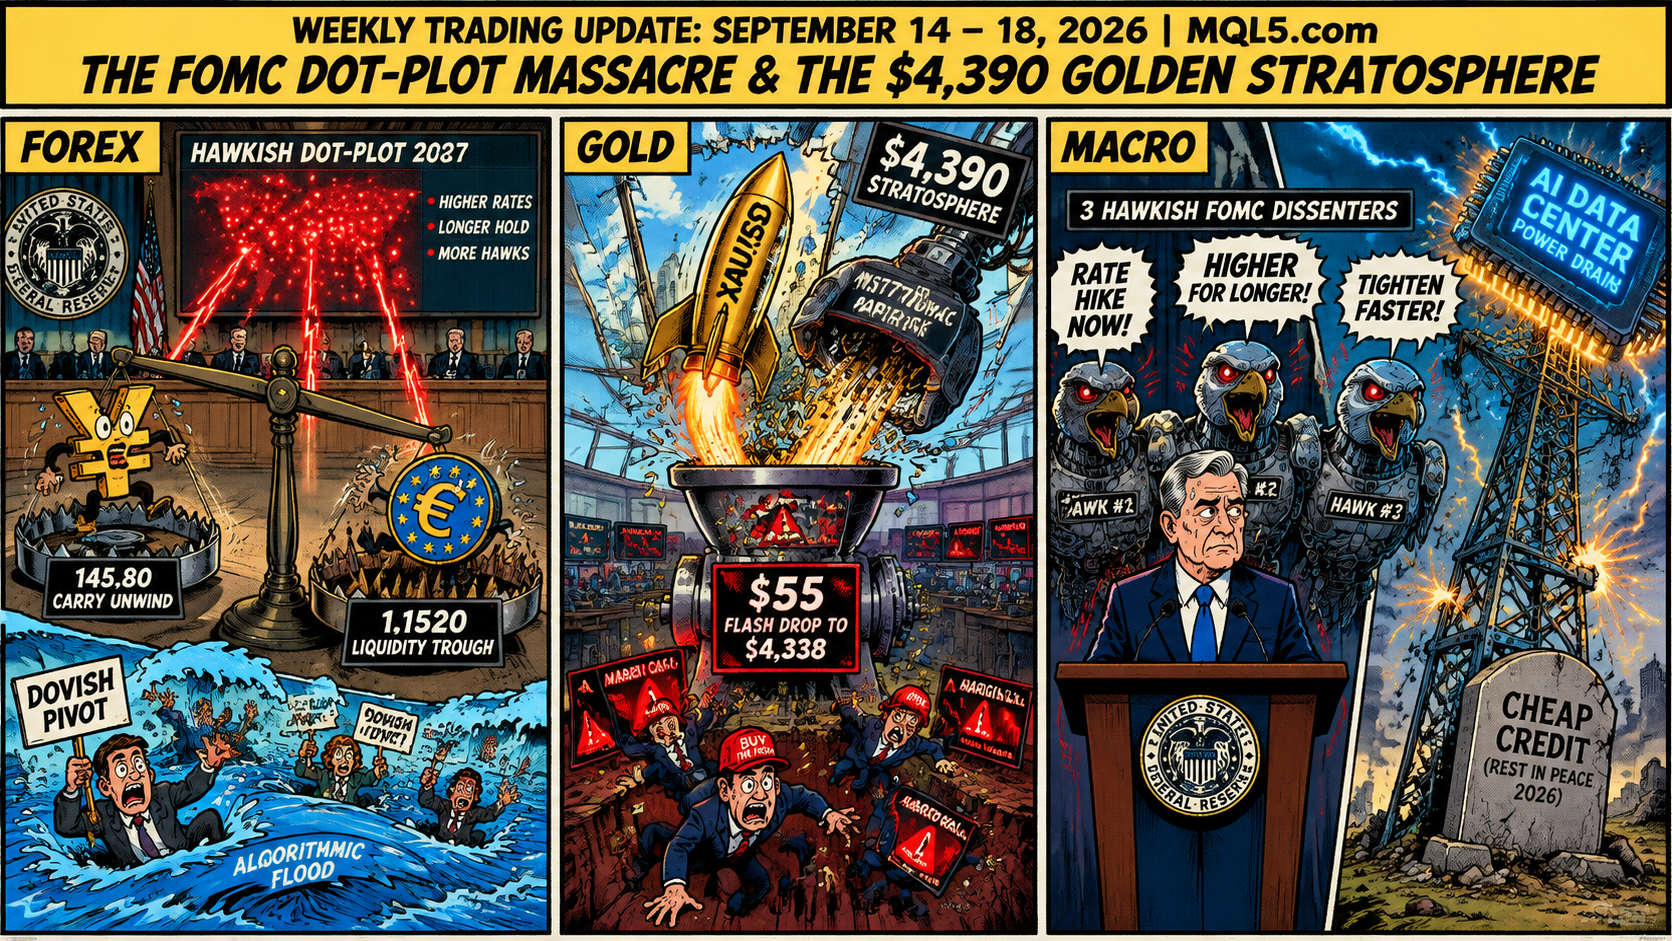
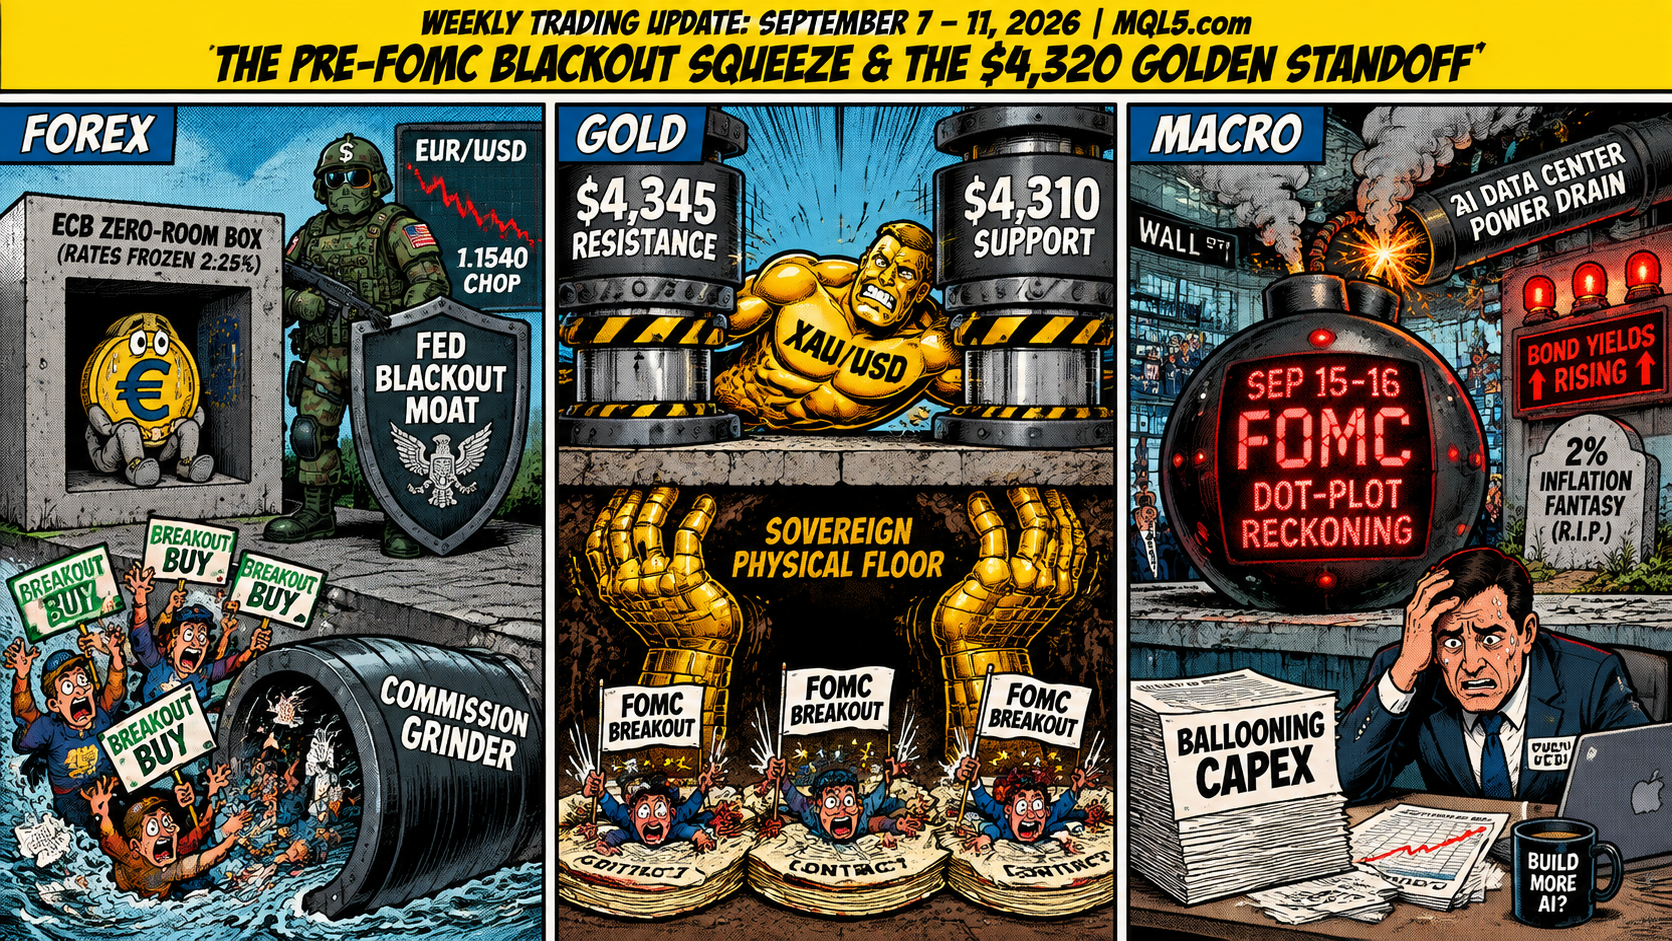
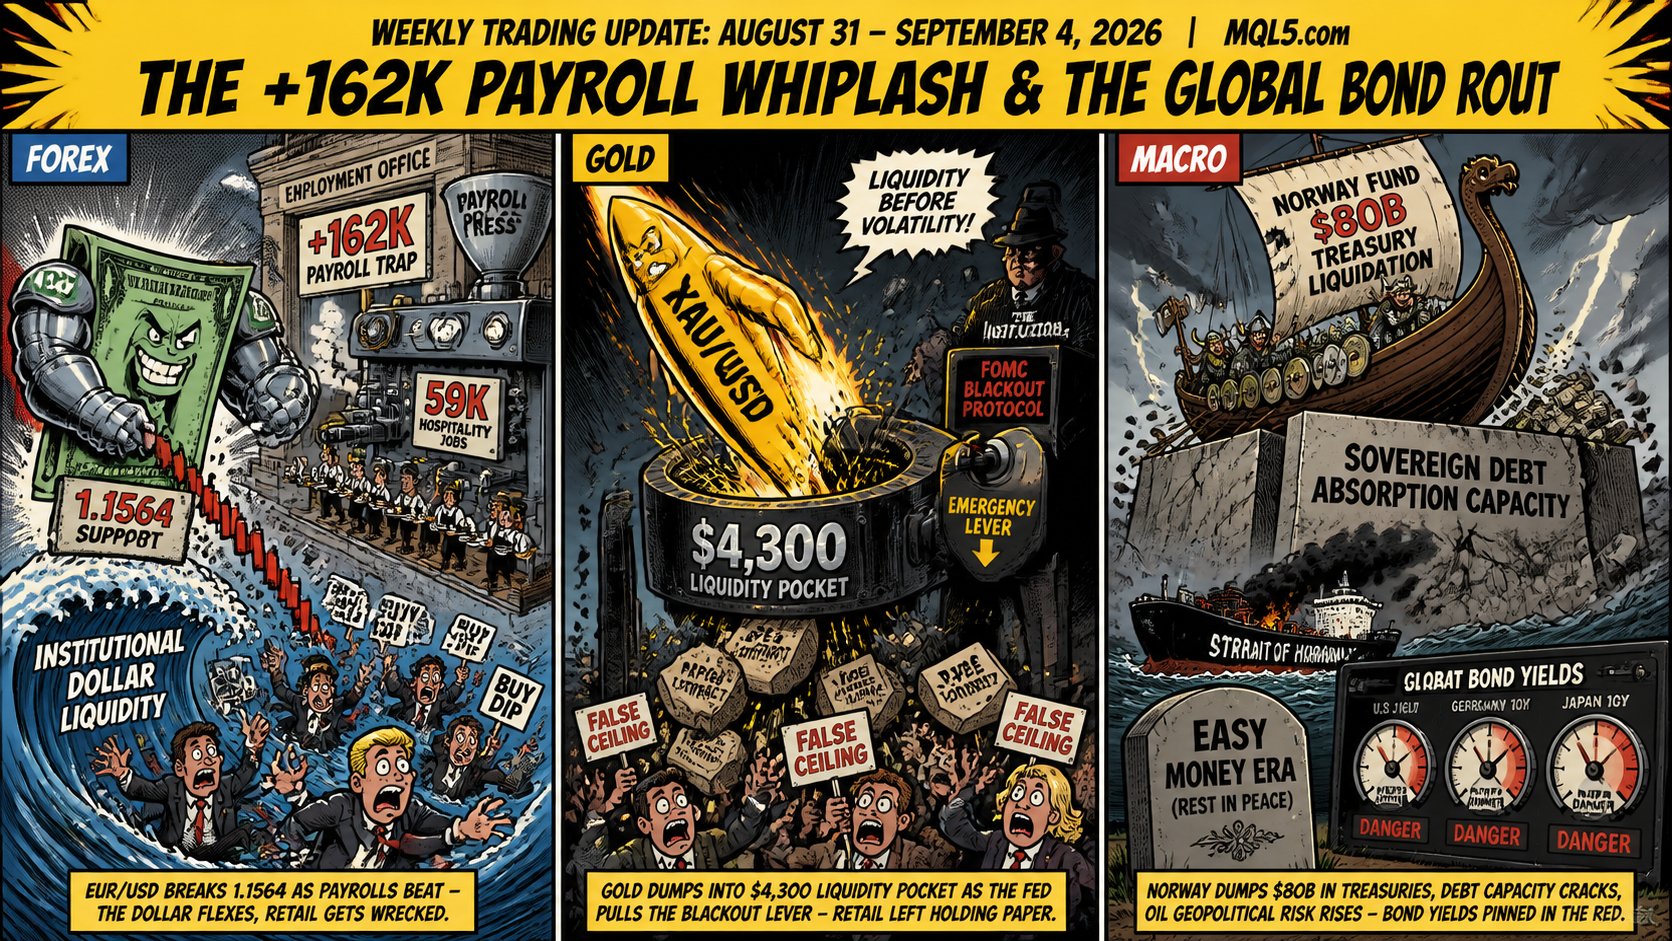
The foreign exchange complex functioned as a high-frequency slaughterhouse for counter-trend retail traders this week, proving yet again that trying to call bottoms on European currencies during a synchronized central bank collision is merely an expedited transfer of equity to interbank liquidity books. The week began with EUR/USD slicing straight through the 1.1200 equilibrium handle on Monday and Tuesday, collapsing to test a precarious multi-month floor at 1.1110/1.1126. Retail accounts aggressively front-ran a "double bottom" bounce ahead of Thursday's European Central Bank decision, expecting Christine Lagarde to halt the bleeding. Institutional algorithms promptly punished the herd. The ECB delivered an uninspiring, boxed-in policy hold, confirming that structural European manufacturing stagnation offers zero room to maneuver while energy import costs remain pinned above $100 per barrel. Meanwhile, Wednesday’s Federal Reserve rate decision delivered a fresh gut punch to dollar bears: the FOMC held benchmark rates at 3.75%–4.00% in a contentious 10–2 split, but two vocal hawkish dissenters explicitly demanded an immediate rate hike, while the statement officially upgraded US economic growth. Benchmark 10-year US Treasury yields blasted straight back through the 5.05% mark. While EUR/USD staged a frantic, short-squeeze scramble back toward 1.1200 on Friday as late shorts took profit, the move was pure mechanical order flow rather than a fundamental turnaround. Over in Tokyo, USD/JPY held near multi-month highs as the Bank of Japan remained completely handcuffed against 5% US yields. If your Expert Advisor traded major pairs without a dynamic yield-spread filter, its margin balance was liquidated into the interbank spread.
Gold (XAU/USD): The $3,880 Golden Meat Grinder and the Equity Contagion Flush
Gold’s tape delivered an absolute masterclass in forced institutional liquidation and predatory stop-hunting, driving precious metals into their steepest multi-month rout of the year. After breaking down below $4,000 late last week, spot gold spent Monday attempting a fragile consolidation around $3,990. Retail dip-buyers, armed with textbook RSI oversold readings and safe-haven theories, eagerly piled into leveraged long contracts. The institutional trapdoor swung open on Wednesday and Thursday. As the 10-year Treasury yield surged above 5.05% and Big Tech earnings from Alphabet reignited broader capex and valuation panics on the Nasdaq, multi-asset hedge funds faced cascading margin calls. Gold was ruthlessly transformed into an emergency cash-raising vehicle. COMEX paper blocks were dumped into the New York open, triggering automated stop-loss runs that drove December futures and spot contracts into an agonizing flush toward $3,880 – $3,976. Even as prices attempted a late Friday technical reflex back toward the $3,980 support pocket, retail margin accounts were left completely hollowed out. The smart money didn’t panic; they used the equity contagion to flush retail leverage out of the order book and reload off-exchange sovereign books at multi-month discounts.
Macro: The 5.05% Bond Sledgehammer, Tech Capex Reality, and the Stagflationary Standoff
In the macroeconomic arena, the financial media's desperate campaign to peddle a painless "soft landing" and late-2026 rate cuts officially died on the operating table. The Federal Reserve's split 10–2 hold sent an unmistakable signal: with structural energy volatility, $100 crude, and tariff shocks refusing to abate, borrowing costs are remaining pinned at cycle highs. The real story was the bond market's refusal to cooperate with corporate equity valuations. Benchmark 10-year Treasury yields pushing to 5.05% pulled the rug out from long-duration tech multiples. Hyperscalers spending tens of billions on unmonetized AI data center capacity faced severe earnings scrutiny, dragging equity indices into a defensive rotation. Meanwhile, global sovereign debt absorption capacity continues to buckle under record deficit supply, reinforcing a permanent floor under global capital costs. We do not trade mainstream commentary, corporate earnings spin, or backward-looking chart patterns. We exploit the cold mathematical divergence between 5% sovereign bond reality and retail complacency. Recalibrate your automated bots for elevated swap charges, widen your volatility parameters, or prepare to have your account balance extracted by the machine.
The 5.05% Yield Surge and the $3,880 Golden Flush: Fed-ECB Collision, Big Tech Capex Skepticism, and the 1.1110 Euro Bear Trap
Forex: The Euro’s 1.1110 Double-Bottom Trap and the Transatlantic Central Bank Squeeze
The foreign exchange complex functioned as a high-frequency slaughterhouse for counter-trend retail traders this week, proving yet again that trying to call bottoms on European currencies during a synchronized central bank collision is merely an expedited transfer of equity to interbank liquidity books. The week began with EUR/USD slicing straight through the 1.1200 equilibrium handle on Monday and Tuesday, collapsing to test a precarious multi-month floor at 1.1110/1.1126. Retail accounts aggressively front-ran a "double bottom" bounce ahead of Thursday's European Central Bank decision, expecting Christine Lagarde to halt the bleeding. Institutional algorithms promptly punished the herd. The ECB delivered an uninspiring, boxed-in policy hold, confirming that structural European manufacturing stagnation offers zero room to maneuver while energy import costs remain pinned above $100 per barrel. Meanwhile, Wednesday’s Federal Reserve rate decision delivered a fresh gut punch to dollar bears: the FOMC held benchmark rates at 3.75%–4.00% in a contentious 10–2 split, but two vocal hawkish dissenters explicitly demanded an immediate rate hike, while the statement officially upgraded US economic growth. Benchmark 10-year US Treasury yields blasted straight back through the 5.05% mark. While EUR/USD staged a frantic, short-squeeze scramble back toward 1.1200 on Friday as late shorts took profit, the move was pure mechanical order flow rather than a fundamental turnaround. Over in Tokyo, USD/JPY held near multi-month highs as the Bank of Japan remained completely handcuffed against 5% US yields. If your Expert Advisor traded major pairs without a dynamic yield-spread filter, its margin balance was liquidated into the interbank spread.
Gold (XAU/USD): The $3,880 Golden Meat Grinder and the Equity Contagion Flush
Gold’s tape delivered an absolute masterclass in forced institutional liquidation and predatory stop-hunting, driving precious metals into their steepest multi-month rout of the year. After breaking down below $4,000 late last week, spot gold spent Monday attempting a fragile consolidation around $3,990. Retail dip-buyers, armed with textbook RSI oversold readings and safe-haven theories, eagerly piled into leveraged long contracts. The institutional trapdoor swung open on Wednesday and Thursday. As the 10-year Treasury yield surged above 5.05% and Big Tech earnings from Alphabet reignited broader capex and valuation panics on the Nasdaq, multi-asset hedge funds faced cascading margin calls. Gold was ruthlessly transformed into an emergency cash-raising vehicle. COMEX paper blocks were dumped into the New York open, triggering automated stop-loss runs that drove December futures and spot contracts into an agonizing flush toward $3,880 – $3,976. Even as prices attempted a late Friday technical reflex back toward the $3,980 support pocket, retail margin accounts were left completely hollowed out. The smart money didn’t panic; they used the equity contagion to flush retail leverage out of the order book and reload off-exchange sovereign books at multi-month discounts.
Macro: The 5.05% Bond Sledgehammer, Tech Capex Reality, and the Stagflationary Standoff
In the macroeconomic arena, the financial media's desperate campaign to peddle a painless "soft landing" and late-2026 rate cuts officially died on the operating table. The Federal Reserve's split 10–2 hold sent an unmistakable signal: with structural energy volatility, $100 crude, and tariff shocks refusing to abate, borrowing costs are remaining pinned at cycle highs. The real story was the bond market's refusal to cooperate with corporate equity valuations. Benchmark 10-year Treasury yields pushing to 5.05% pulled the rug out from long-duration tech multiples. Hyperscalers spending tens of billions on unmonetized AI data center capacity faced severe earnings scrutiny, dragging equity indices into a defensive rotation. Meanwhile, global sovereign debt absorption capacity continues to buckle under record deficit supply, reinforcing a permanent floor under global capital costs. We do not trade mainstream commentary, corporate earnings spin, or backward-looking chart patterns. We exploit the cold mathematical divergence between 5% sovereign bond reality and retail complacency. Recalibrate your automated bots for elevated swap charges, widen your volatility parameters, or prepare to have your account balance extracted by the machine.